Emergency Fund for Home Repairs and Maintenance
An emergency fund for home repairs and maintenance prevents surprise bills from becoming financial crises. Learn how much to save and where to keep it.
By ryanthompson Contributor
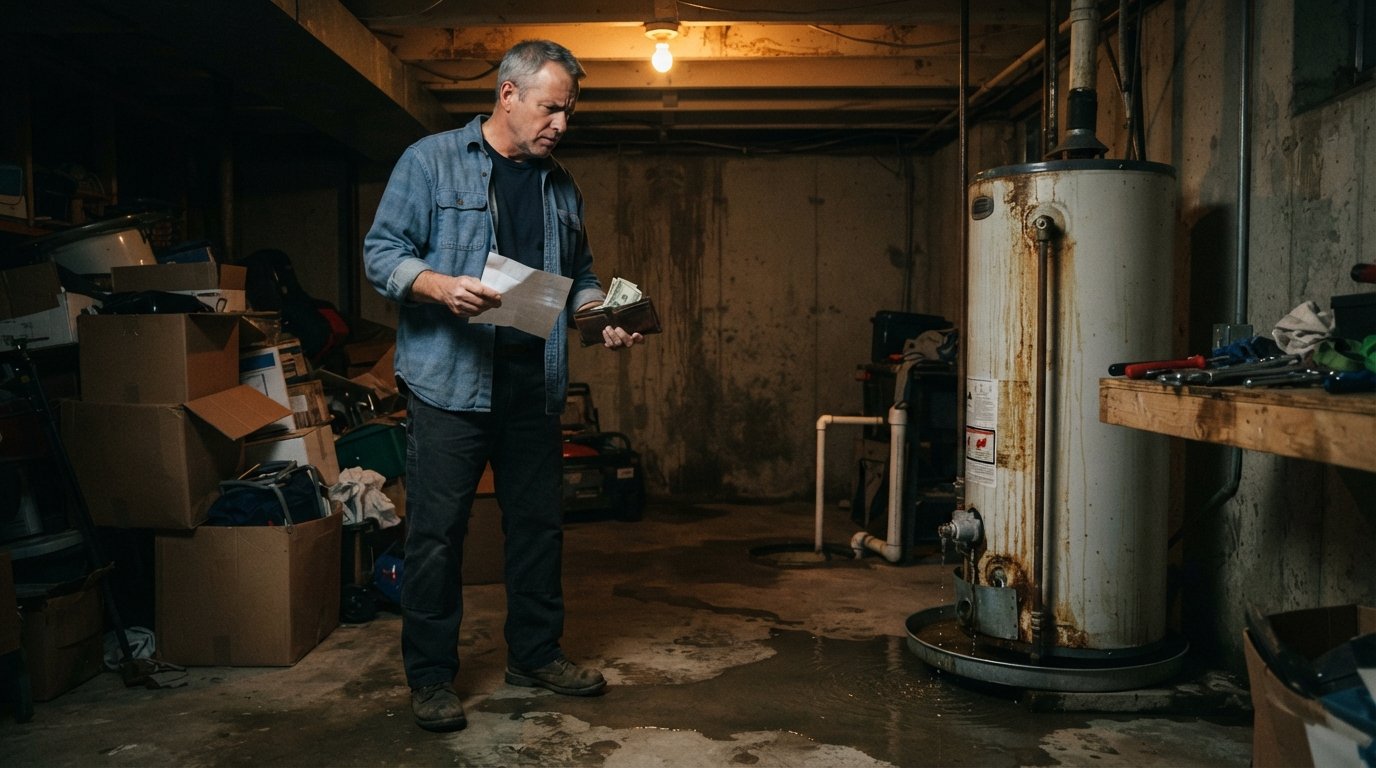
Your water heater dies on a Sunday night. The repair quote comes in at $1,800. Your emergency fund for home repairs and maintenance has $400 in it. This is the moment every homeowner dreads, and it happens more often than most people expect. According to home inspection data, the average U.S. homeowner spends between 1 and 4 percent of their home's value each year on maintenance and repairs. On a $350,000 house, that is $3,500 to $14,000 annually. Without a dedicated savings buffer, those costs land on credit cards, personal loans, or deferred maintenance that snowballs into bigger problems later.
Building a home repair emergency fund is not glamorous. It does not have the excitement of picking paint colors or the satisfaction of a finished renovation. But it is the single most reliable way to protect your home, your credit score, and your peace of mind. This guide breaks down how much to save, where to keep the money, and what to do when a repair bill exceeds what you have set aside.
Why a Dedicated Home Repair Fund Beats General Savings
Many homeowners lump all their savings into one account and call it an emergency fund. That approach works, but it has a flaw: it is hard to know whether you have enough. A general emergency fund might need to cover a job loss, a medical bill, a car repair, and a roof replacement all at once. When you separate home repair savings from other emergency money, you get clarity. You know exactly what is available for the house, and you stop borrowing from your home fund to pay for unrelated expenses.
A dedicated home maintenance fund also helps you plan for predictable costs. Your HVAC system has a lifespan of roughly 15 to 20 years. Your roof might last 20 to 30 years. Your water heater typically lasts 8 to 12 years. These are not surprises; they are timelines. When you track the age of major systems, you can estimate when replacements will hit and save accordingly. That turns a potential financial crisis into a planned expense.
There is also a psychological benefit. When you have money set aside specifically for home repairs, you are more likely to address small issues before they become big ones. A $200 plumbing fix today prevents a $2,000 water damage repair next year. Homeowners without a repair fund often delay maintenance, hoping the problem will go away. It rarely does.
How Much Should You Save for Home Repairs?
The standard recommendation is to save 1 to 3 percent of your home's purchase price each year for maintenance and repairs. On a $300,000 home, that is $3,000 to $9,000 per year. But that range is broad, and the right number depends on several factors.
Consider the age and condition of your home. A brand-new construction home may need very little beyond basic upkeep for the first few years. A 40-year-old house with original systems will demand more. Climate matters too. Homes in areas with harsh winters, high humidity, or frequent storms face more wear and tear. Finally, consider your own tolerance for risk. If you would rather have a larger cushion, aim for the higher end of the range.
Here is a simple framework for setting your target:
- Newer home (under 10 years old): Save 1 percent of home value annually, plus a starter fund of $2,000 to $5,000 for unexpected issues.
- Mid-age home (10 to 30 years old): Save 1.5 to 2 percent annually, with a target fund of $5,000 to $10,000.
- Older home (30+ years old): Save 2 to 3 percent annually, with a target fund of $10,000 to $20,000 or more depending on condition.
These numbers are starting points, not rigid rules. The key is to have a target and a timeline. If you need $10,000 and can save $400 per month, you will reach your goal in about two years. If that feels slow, look for ways to accelerate: tax refunds, side income, or redirecting money you were previously spending on non-essentials.
Where to Keep Your Home Repair Emergency Fund
Your home repair fund should be accessible but not too accessible. You want to earn some interest, but you also want to avoid the temptation to dip into it for everyday spending. A high-yield savings account is the most common choice. These accounts typically offer higher interest rates than standard savings accounts and keep your money liquid. You can transfer funds to your checking account within a day or two when a repair bill arrives.
Some homeowners use a separate savings account at a different bank than their primary checking account. This adds a small barrier to impulse withdrawals. Others use a money market account, which may offer slightly higher rates and check-writing privileges. Certificates of deposit (CDs) are another option, but they lock your money for a set term. That can be a problem if a repair pops up before the CD matures. If you use CDs, consider a ladder strategy where portions of your fund mature at different times.
What you should not do is keep your home repair fund in investments that can lose value. Stocks, bonds, and mutual funds are great for long-term goals, but they can drop 20 percent or more in a bad market. If your roof fails during a downturn, you do not want to sell investments at a loss to pay for it. Keep your emergency fund in cash-equivalent accounts that preserve principal.
What Counts as a Home Repair Emergency?
Not every home expense is an emergency. A broken dishwasher is inconvenient, but you can wash dishes by hand while you save for a replacement. A failed furnace in January is a genuine emergency. Knowing the difference helps you protect your fund for the expenses that truly cannot wait.
True home repair emergencies generally meet three criteria: they threaten your safety, they cause further damage if ignored, or they make the home uninhabitable. Examples include:
- Roof leaks or storm damage that lets water into the structure
- Burst pipes or significant plumbing failures
- Furnace or HVAC failure during extreme temperatures
- Electrical hazards such as sparking outlets or exposed wiring
- Sewer backups or septic system failures
- Mold discovery that requires immediate remediation
Non-emergencies that can be planned for include cosmetic updates, appliance replacements that are not urgent, landscaping projects, and voluntary renovations. For these, use a separate home improvement savings fund or consider financing options if the project adds value to your home.
When in doubt, ask yourself: if I wait three months, will this cost more or cause additional damage? If the answer is yes, it is probably an emergency. If the answer is no, you have time to save.
When Your Emergency Fund Is Not Enough
Even the best-laid plans can fall short. A major repair like a foundation issue or a full HVAC replacement can cost $10,000 or more. If your emergency fund covers only part of the bill, you have several options. The key is to choose the one that minimizes long-term financial damage.
One option is a home equity loan or home equity line of credit (HELOC). These products let you borrow against the value of your home, often at lower interest rates than personal loans or credit cards. A HELOC works like a credit line you can draw on as needed, while a home equity loan provides a lump sum with fixed payments. Both can be smart choices for repairs that increase your home's value. To compare current rates and understand how these products fit your situation, you can use RateChecker to explore real-time mortgage and home equity rate options.
A personal loan is another possibility. Personal loans are unsecured, meaning they are not tied to your home. They typically have fixed rates and predictable monthly payments. Interest rates may be higher than home equity products, but the application process is often faster. If you have decent credit, a personal loan can bridge the gap between your emergency fund and the total repair cost.
Credit cards should be a last resort for large repairs. Interest rates on credit cards are often 20 percent or higher, and carrying a balance can damage your credit score. If you must use a credit card, look for a 0 percent introductory APR offer and pay off the balance before the promotional period ends.
Before borrowing, always get multiple quotes for the repair work. Prices can vary widely, and a few phone calls can save you hundreds or thousands of dollars. Also, check whether the repair is covered by your homeowner's insurance. Sudden damage from storms, fires, or burst pipes is often covered, while wear-and-tear is not.
Building Your Fund: A Step-by-Step Plan
If you are starting from zero, do not be overwhelmed. Building a home repair emergency fund is a process, and every dollar you save is progress. Here is a practical plan to get started.
- Set a target. Use the percentage guidelines above to estimate how much you need. Write it down and review it annually.
- Open a dedicated account. Choose a high-yield savings account and name it something clear, like "Home Repair Fund."
- Automate your savings. Set up a recurring transfer from your checking account on payday. Even $50 or $100 per month adds up over time.
- Add windfalls. Direct tax refunds, bonuses, or gifts toward your fund until you reach your target.
- Track home system ages. Keep a simple spreadsheet of when your roof, HVAC, water heater, and other major systems were installed or last replaced.
- Review and adjust. Once a year, check your fund balance and your home's condition. Increase your savings rate if you are behind.
Consistency matters more than speed. A homeowner who saves $200 per month for five years has $12,000 plus interest, enough to cover most mid-range repairs. The habit of saving becomes easier over time, and the peace of mind is worth the effort.
How Your Emergency Fund Affects Your Financing Options
A healthy home repair emergency fund does more than cover unexpected bills. It also strengthens your position when you apply for financing. Lenders look at your savings as a sign of financial stability. If you are applying for a mortgage refinance or a home equity loan, having reserves can improve your approval odds and may even help you qualify for better rates.
On the flip side, a lack of savings can limit your options. If you have no emergency fund and a major repair hits, you may be forced to accept whatever loan terms you can get. That could mean higher interest rates, larger fees, or a longer repayment period. Building your fund now gives you leverage later.
If you are considering a refinance or home equity product to fund a repair or renovation, it is wise to compare offers from multiple lenders. Rates and terms vary significantly, and even a small difference in interest rate can save you thousands over the life of the loan. Educational resources and rate comparison tools can help you see what is available without pressure. Remember that submitting an online application typically means you consent to be contacted by phone or email by network members, so read the terms carefully.
Common Mistakes to Avoid
Even homeowners who understand the importance of an emergency fund sometimes make mistakes that undermine their efforts. Here are a few to watch for.
First, do not invest your emergency fund in volatile assets. The stock market is not a safe place for money you might need next month. Second, do not use your home repair fund for non-home expenses. It is tempting to dip into it for a vacation or a new car, but that defeats the purpose. Third, do not ignore small maintenance tasks. A $50 annual furnace tune-up can prevent a $500 repair. Fourth, do not assume your homeowner's insurance covers everything. Most policies exclude wear-and-tear and require you to pay a deductible. Finally, do not wait until you have a problem to start saving. The best time to build your fund is before you need it.
Another mistake is setting your target too low. A $1,000 fund might cover a minor plumbing issue, but it will not help with a roof replacement or a foundation repair. Aim for a realistic number based on your home's age, condition, and your local labor costs. If you are unsure, err on the side of saving more.
Finally, do not forget to replenish your fund after you use it. If you spend $3,000 on a new water heater, make a plan to build that money back. Otherwise, you will be caught short the next time something breaks.
Protecting Your Home and Your Financial Future
An emergency fund for home repairs and maintenance is not just a financial buffer. It is a tool for protecting your most valuable asset. When you have money set aside, you can address problems quickly, maintain your home's value, and avoid the high-interest debt that comes with scrambling for funds. You also gain confidence. You know that when the unexpected happens, you are ready.
Start small if you must, but start today. Open a savings account, set a target, and automate whatever you can afford. Review your progress each year and adjust as needed. Over time, your fund will grow, and so will your peace of mind. Your home will thank you, and so will your future self.