
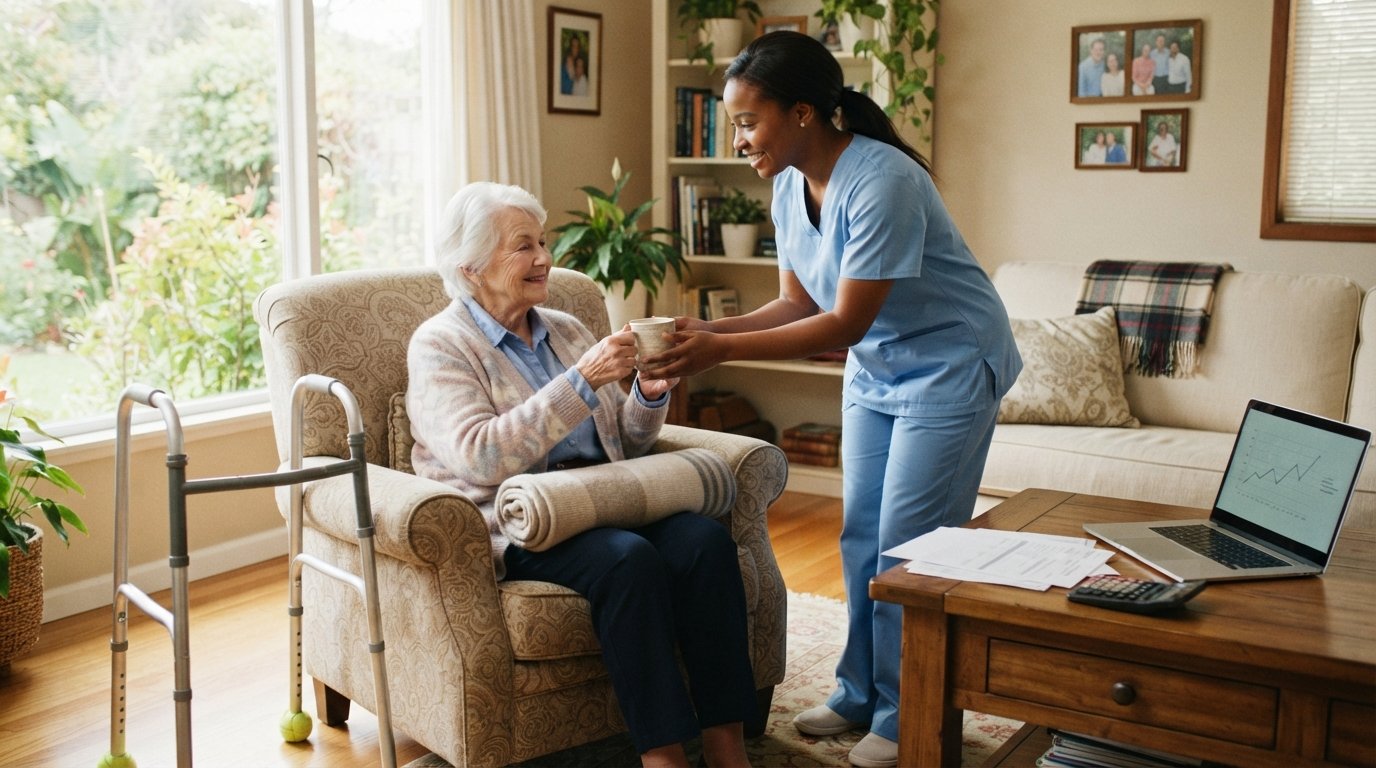
Funding Long Term Care With a Reverse Mortgage: 2026 Guide
Funding long term care with a reverse mortgage lets homeowners 62+ tap equity, skip monthly payments, and stay in the home while covering care costs.
By Owen Young
Long term care costs keep climbing, and many retirees watch their savings shrink faster than expected. A private room in a nursing home can exceed $100,000 per year in some states, while in-home care runs $30 or more per hour. Traditional health insurance and Medicare typically cover only limited skilled care, leaving families to bridge a massive gap. For homeowners aged 62 and older, a reverse mortgage can turn home equity into a practical funding source for long term care, without forcing an immediate sale or adding a monthly mortgage payment. This guide explains how the strategy works, what it costs, and how to decide whether it fits your situation.
Why Long Term Care Funding Feels Impossible for Many Families
The numbers tell a sobering story. According to long term care industry data, a semi-private nursing home room averages over $90,000 annually, assisted living communities run $50,000 to $70,000, and full-time home health aides can cost $60,000 or more per year. These figures rise 3 to 5 percent annually, outpacing many retirees' cost-of-living adjustments.
Medicare pays for skilled nursing care only under specific conditions and only for a limited time, typically up to 100 days following a hospital stay. It does not cover custodial care, which is the help with bathing, dressing, eating, and mobility that most long term care actually involves. Medicaid steps in only after a person has spent down most assets, and the rules vary widely by state. Private long term care insurance exists, but premiums have soared, and many policies sold decades ago have limited benefits or have been discontinued.
That leaves a gap that families often fill with savings, family contributions, or the sale of a home. A reverse mortgage offers a different path: it lets the homeowner stay in the house while converting equity into cash that can pay for care, whether that care happens at home or in a facility.
How a Reverse Mortgage Actually Works for Care Expenses
A reverse mortgage, most commonly a Home Equity Conversion Mortgage (HECM) insured by the FHA, allows homeowners aged 62 or older to borrow against their home equity. Unlike a traditional mortgage, you make no required monthly payments. The loan balance grows over time and is repaid when the last borrower moves out, sells the home, or passes away. The homeowner remains responsible for property taxes, homeowners insurance, and home maintenance.
The amount you can borrow depends on your age (older borrowers qualify for more), the appraised home value, current interest rates, and the FHA lending limit, which is $1,209,750 in 2026 for a HECM. You can receive the money as a lump sum, monthly payments, or a line of credit. The line of credit option is especially useful for long term care because the unused portion grows over time, giving you a larger reserve for future care needs.
For care funding, the flexibility matters. You might use a monthly draw to pay an in-home aide, or tap a lump sum to cover a deposit and first year at an assisted living community. If care needs change, you can adjust withdrawals. The loan does not restrict how you use the money, so it can cover medical bills, home modifications, or facility fees.
It is important to note that a reverse mortgage is not free money. Interest accrues on the balance, and closing costs and mortgage insurance premiums apply. But for homeowners who are house-rich and cash-poor, it can be the difference between receiving care at home and being forced to sell the house under pressure.
Reverse Mortgage Payout Options and How They Fit Care Needs
Choosing the right payout structure can make a significant difference in how well a reverse mortgage supports a long term care plan. Each option has trade-offs depending on whether you need steady income, a large upfront sum, or a growing reserve for future needs.
- Lump sum: Best for immediate, large expenses such as a facility buy-in, home accessibility renovations, or paying off existing debts to free up cash flow.
- Monthly payments (tenure or term): Provides predictable income for ongoing care costs like in-home aide hours, adult day care, or assisted living fees.
- Line of credit: Offers the most flexibility and growth potential. The unused balance increases over time, so it can serve as a growing emergency fund for care that may not be needed for years.
- Combination: Some borrowers take a small lump sum for immediate needs and leave the rest in a growing line of credit for future care.
For many families planning ahead, the line of credit is the most powerful tool. If you open a reverse mortgage at 62 but do not need care until 75, the available credit may have grown substantially, providing a larger pool of funds than a lump sum taken earlier would have allowed. That growth can help offset rising care costs.
If you are still exploring how reverse mortgage proceeds are treated for tax purposes, our guide on whether reverse mortgage payouts are taxable explains the general IRS treatment and why most borrowers receive funds tax-free. Understanding that can help you plan with more confidence.
Comparing Reverse Mortgage Costs to Other Funding Sources
No one funding source is perfect for long term care. A reverse mortgage competes with options like selling the home, using a traditional home equity loan or HELOC, tapping retirement accounts, or relying on family support. Each has distinct pros and cons.
Selling the home can generate cash, but it means giving up a place to live and possibly moving before you are ready. A traditional home equity loan or HELOC requires monthly payments, which can strain a fixed income when care costs are already high. Retirement account withdrawals may trigger taxes and deplete assets that could be needed later. Family support can help, but it is not a reliable long-term plan for most households.
A reverse mortgage stands out because it requires no monthly mortgage payments and lets you stay in the home. That can be critical if one spouse needs care while the other continues to live in the house. The loan becomes due only when the last borrower permanently leaves. For married couples, this protects the surviving spouse from losing the home while also funding care for the first spouse who needs it.
That said, reverse mortgages have higher upfront costs than HELOCs. Closing costs, origination fees, and initial mortgage insurance premiums can total thousands of dollars. Over a short horizon, those costs may outweigh the benefits. But for a long term care plan that may span 10 or more years, the ability to stay in the home and avoid monthly payments often justifies the expense.
Key Requirements and Protections for Reverse Mortgage Borrowers
To qualify for a HECM, all borrowers on title must be at least 62 years old. The home must be your primary residence, and you must meet with a HUD-approved counselor before closing. The counselor explains the loan terms, alternatives, and your obligations. You also need to demonstrate the financial capacity to pay property taxes, insurance, and basic maintenance, or set aside funds from the loan to cover those costs.
Several consumer protections apply. The loan is non-recourse, meaning you or your estate will never owe more than the home is worth when it is sold to repay the loan. If the sale proceeds are less than the balance, the FHA insurance covers the difference. You cannot be evicted simply because the loan balance grows, as long as you live in the home and meet your obligations.
If you are considering a reverse mortgage to fund care, it helps to compare rates and terms from multiple lenders. A platform like RateChecker can help you see current reverse mortgage rate offers and understand how different lenders price these products, which can save you thousands over the life of the loan.
Steps to Use a Reverse Mortgage for Long Term Care
Planning ahead makes the process smoother. If you or a loved one are considering this route, here is a practical sequence to follow.
- Assess your care needs and timeline. Estimate the type of care you may need, where you want to receive it, and roughly when. This helps determine how much funding you will require and whether a line of credit or monthly payments fit better.
- Review your finances and eligibility. Check your age, home value, existing mortgage balance, and ability to pay taxes and insurance. A lender can give you a preliminary estimate of how much you could borrow.
- Complete HUD-approved counseling. This is required for a HECM. The counselor will discuss alternatives like selling, downsizing, or using other assets, so you can make an informed choice.
- Compare offers and choose a payout option. Work with multiple lenders to compare rates, fees, and service. Decide whether a lump sum, monthly payments, a line of credit, or a combination best matches your care plan.
- Close and set up a care funding strategy. Once the loan closes, coordinate with family or a financial advisor to manage withdrawals and ensure care bills are paid on time.
Each step builds on the last. Skipping counseling or failing to compare lenders can lead to higher costs or a payout structure that does not align with your actual care needs. Taking the time upfront can make the difference between a smooth funding solution and a stressful financial burden.
Risks, Trade-Offs, and When to Think Twice
A reverse mortgage is not right for everyone. If you plan to move within a few years, the upfront costs may not be worth it. If your home needs major repairs, you may need to address those before qualifying, and the loan may not leave enough equity for other goals. If you have significant other assets, you might prefer to use those first to avoid depleting home equity that could be a legacy for heirs.
Heirs should understand that a reverse mortgage reduces the estate's value. When the home is sold to repay the loan, remaining equity goes to the estate, but the loan balance and accrued interest come out first. If leaving the home to children is a top priority, a reverse mortgage may conflict with that goal.
Interest rates also matter. A higher rate means the loan balance grows faster, reducing the equity left for you or your estate. Adjustable-rate HECMs can change over time, so you need to be comfortable with that variability. Fixed-rate options exist but typically require a lump sum, which may not suit a long term care plan that needs flexibility.
Finally, a reverse mortgage should not be the only piece of a care plan. It works best when combined with savings, insurance, and family support. If you are unsure, talk to a HUD-approved counselor and a financial advisor who understands both reverse mortgages and long term care costs.
Making the Decision With Confidence
Funding long term care with a reverse mortgage can be a smart move for homeowners who want to age in place, avoid monthly payments, and tap equity that would otherwise sit idle. It offers a way to pay for care without selling the home or draining other assets too quickly. But it is not a simple or cost-free solution. Weigh the fees, the long-term impact on your estate, and your care timeline before committing.
Start by getting educated, comparing lenders, and speaking with a counselor. With the right preparation, a reverse mortgage can become a reliable part of a broader long term care funding strategy, giving you and your family more options and less financial stress during a challenging time.