How Does a Home Equity Loan Affect Your Credit Score?
A home equity loan can impact your credit score in several ways. Learn how applications, payments, and loan type affect your credit and how to protect it.
By Hannah Reed
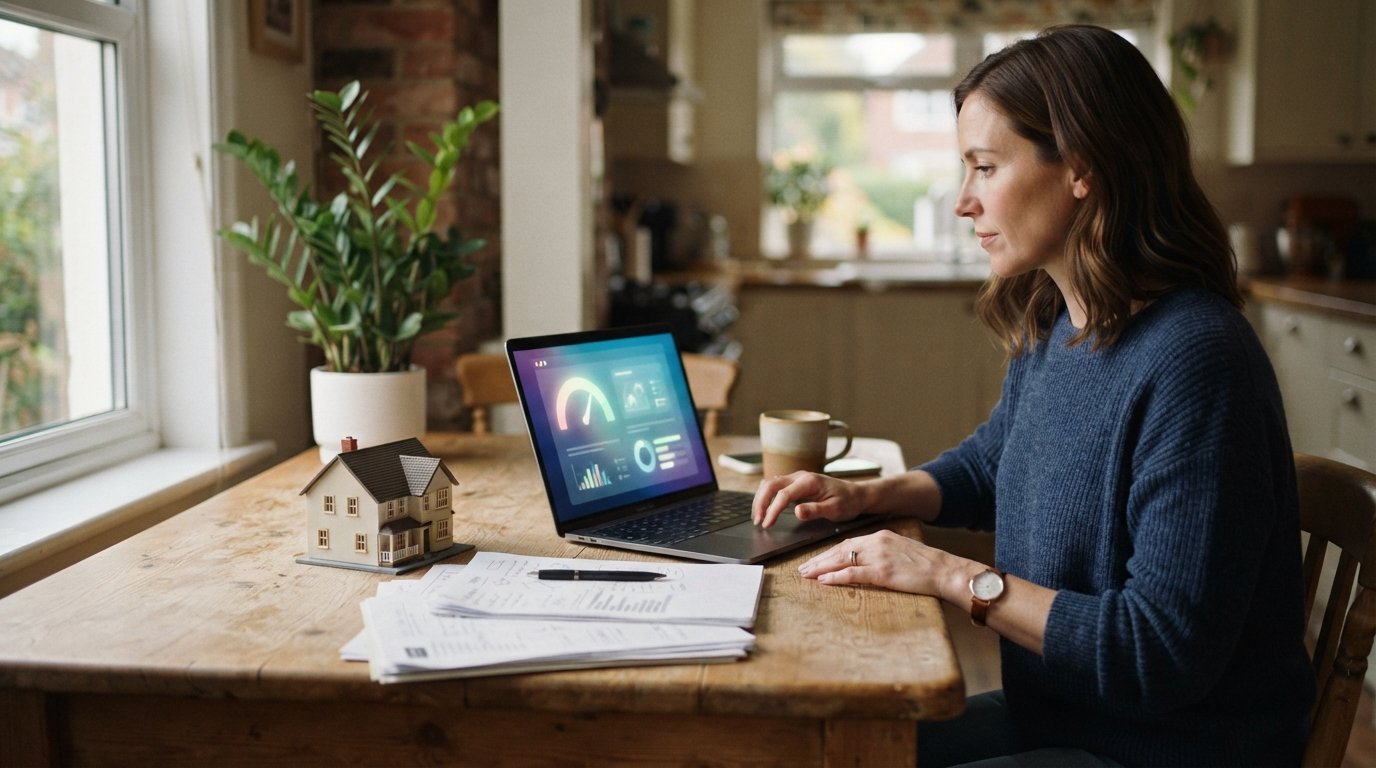
A home equity loan can feel like a lifeline when you need cash for a renovation, debt consolidation, or a major expense. But before you sign on the dotted line, you are probably wondering: how does a home equity loan affect your credit score? The answer is not a simple yes or no. It depends on how you manage the application, the loan itself, and your overall financial habits. In this guide, we break down the credit score impacts at every stage, from the initial inquiry to the final payment, so you can borrow with confidence and protect your credit health.
The Application Stage: Hard Inquiries and Temporary Dips
When you apply for a home equity loan, the lender will pull your credit report to assess your risk. This results in a hard inquiry, which typically causes a small, temporary drop in your credit score, usually around 5 to 10 points. The impact is generally short-lived and may be less significant if you have a strong credit history. However, multiple applications within a short window can compound the effect. To minimize damage, do your rate shopping within a focused period (typically 14 to 45 days, depending on the scoring model), as many scoring models treat multiple inquiries for the same type of loan as a single inquiry. This way, you can compare offers without multiplying the hit to your score.
It is also worth noting that the hard inquiry remains on your credit report for two years, but its effect on your score diminishes over time, often within a few months. So while you might see a slight dip initially, it is not a long-term penalty if you handle the rest of your credit obligations responsibly.
How the Loan Itself Affects Your Credit Mix and Utilization
A home equity loan is an installment loan, meaning you receive a lump sum and repay it in fixed monthly payments over a set term. This can actually help your credit mix, which is a factor in credit scoring. Lenders like to see that you can manage different types of credit, such as revolving accounts (credit cards) and installment loans. Adding a home equity loan can diversify your credit profile and potentially boost your score over time, provided you make payments on time.
Additionally, home equity loans are secured by your home, so they may be viewed differently than unsecured debt. The balance of the loan is not included in your credit utilization ratio (the amount of revolving credit you use compared to your limits), which is a major scoring factor. This means that taking out a home equity loan does not directly increase your utilization rate, unlike maxing out a credit card. However, the new monthly payment becomes part of your debt-to-income ratio, which lenders consider for future credit applications, even though it is not a direct scoring factor.
Home Equity Loan vs. HELOC: Different Credit Impacts
While both home equity loans and home equity lines of credit (HELOCs) allow you to tap into your home's equity, they affect your credit score differently. A HELOC is a revolving line of credit, similar to a credit card. When you draw funds from a HELOC, the outstanding balance counts toward your credit utilization ratio. If you use a large portion of your available credit, your utilization rate increases, which can lower your score. In contrast, a home equity loan is an installment loan, and its balance does not factor into utilization. This distinction is crucial if you are concerned about maintaining a low utilization rate. However, HELOCs often have variable interest rates, while home equity loans typically offer fixed rates, so consider both the credit and financial implications before choosing.
Another difference is that HELOCs may come with an annual fee and a draw period during which you can borrow, repay, and borrow again. The flexibility can be beneficial, but it also requires disciplined credit management to avoid overutilization. Home equity loans provide a predictable repayment schedule, which can be easier to budget for and may pose less risk to your credit score if you tend to carry balances.
Payment History: The Long-Term Impact
Your payment history is the most significant factor in your credit score, accounting for about 35% of your FICO score. Once you have a home equity loan, making on-time payments every month will gradually improve your credit score. Conversely, missing a payment can cause severe damage. A single late payment can drop your score by 50 to 100 points or more, depending on your starting score and the severity of the delinquency. Since a home equity loan is secured by your home, defaulting could lead to foreclosure, which would be catastrophic for your credit. Therefore, it is essential to set up automatic payments or reminders to ensure you never miss a due date.
During the repayment period, the loan balance decreases over time, which can positively affect your credit utilization if you also have revolving debts. However, the primary benefit comes from the consistent demonstration of responsible repayment behavior. Lenders view a history of on-time payments on a home equity loan as a strong sign of creditworthiness, which can help you qualify for better rates on future loans.
Protecting Your Credit Score When Shopping for Equity Products
If you are considering a home equity loan, you can take steps to shield your credit score from unnecessary damage. Start by checking your credit reports for errors and disputing any inaccuracies before applying. A clean report can improve your chances of approval and may lead to better terms. When shopping for rates, gather quotes from multiple lenders within a short timeframe to minimize the impact of hard inquiries. Also, avoid opening other new credit accounts or making large purchases on credit during the application process, as this can increase your debt-to-income ratio and make lenders nervous.
Consider using pre-qualification tools, which typically involve a soft inquiry that does not affect your score, to get an idea of the rates you might qualify for. Many lenders, including those in the LoanFinancing network, offer pre-qualification options. Finally, once you have the loan, prioritize building an emergency fund so you can cover unexpected expenses without relying on credit, which helps you maintain a healthy credit profile.
Strategies to Minimize Negative Credit Impacts
To keep your credit score in good shape, plan your home equity loan strategically. Avoid applying for multiple loans simultaneously, and do not max out your available credit if you choose a HELOC. Keep your overall debt load manageable by not borrowing more than you truly need. If you use the loan for debt consolidation, resist the temptation to run up balances on the paid-off credit cards, as this can lead to a cycle of debt and hurt your credit utilization. Set up a budget that accommodates the new monthly payment and stick to it. Regularly monitor your credit score and reports to catch any issues early. By being proactive, you can leverage your home equity without sacrificing your credit health.
If you are also considering other financing options, such as a bridge loan, it is wise to compare how each product affects your credit. For instance, our article on bridge loan vs home equity loan explains the trade-offs in detail.
When to Consult a Professional
If you have a complex financial situation or are unsure how a home equity loan will impact your credit, consider speaking with a financial advisor or a housing counselor. They can help you evaluate your options and create a plan that aligns with your goals. Additionally, for comprehensive mortgage information and tools, you can visit RefinancingCo, which offers educational resources and calculators to guide your decisions. Remember, LoanFinancing is not a lender but a platform to connect you with potential lenders; always review offers carefully and choose the one that best fits your needs.
By understanding how a home equity loan affects your credit score at each stage, you can make informed choices and use this financial tool to your advantage. Whether you are consolidating debt or funding a home improvement, responsible borrowing and timely payments will help you maintain a strong credit profile.