How to Rebuild Credit After a Personal Loan Default
A personal loan default is not the end. Learn how to rebuild credit after a personal loan default with negotiation, secured cards, and steady payment habits.
By Rachel Turner
A personal loan default feels like a financial earthquake. One missed payment turns into several, the account gets charged off, and your credit score drops sharply. The shame and stress can be overwhelming, but a default is not a permanent life sentence. With a clear plan and steady effort, you can rebuild your credit and regain access to affordable financing. This guide walks you through the practical steps to recover after a personal loan default, from understanding the damage to negotiating with collectors and gradually restoring your creditworthiness.
Understanding the Damage: How Defaults and Collections Affect Your Credit
When you default on a personal loan, the lender typically reports the delinquency to the credit bureaus after 30 days. As the missed payments pile up, the impact on your credit score grows. After 120 to 180 days of nonpayment, the lender may charge off the debt, meaning they write it off as a loss. This charge-off is another negative mark that signals to future lenders that you failed to repay a debt. If the loan was unsecured, the lender might eventually sell the debt to a collection agency, which adds a separate collections entry to your credit report.
Both the original delinquency and any collection account can stay on your credit report for up to seven years from the date of first delinquency. During that time, they can significantly lower your credit score and make it harder to qualify for new credit, rent an apartment, or even get a job in some cases. The exact score drop depends on your overall credit profile, but a default can easily knock 100 points or more off a good score. The good news is that the impact diminishes over time, especially if you take proactive steps to address the debt and demonstrate responsible credit behavior going forward.
Step 1: Assess Your Credit Reports and the Debt
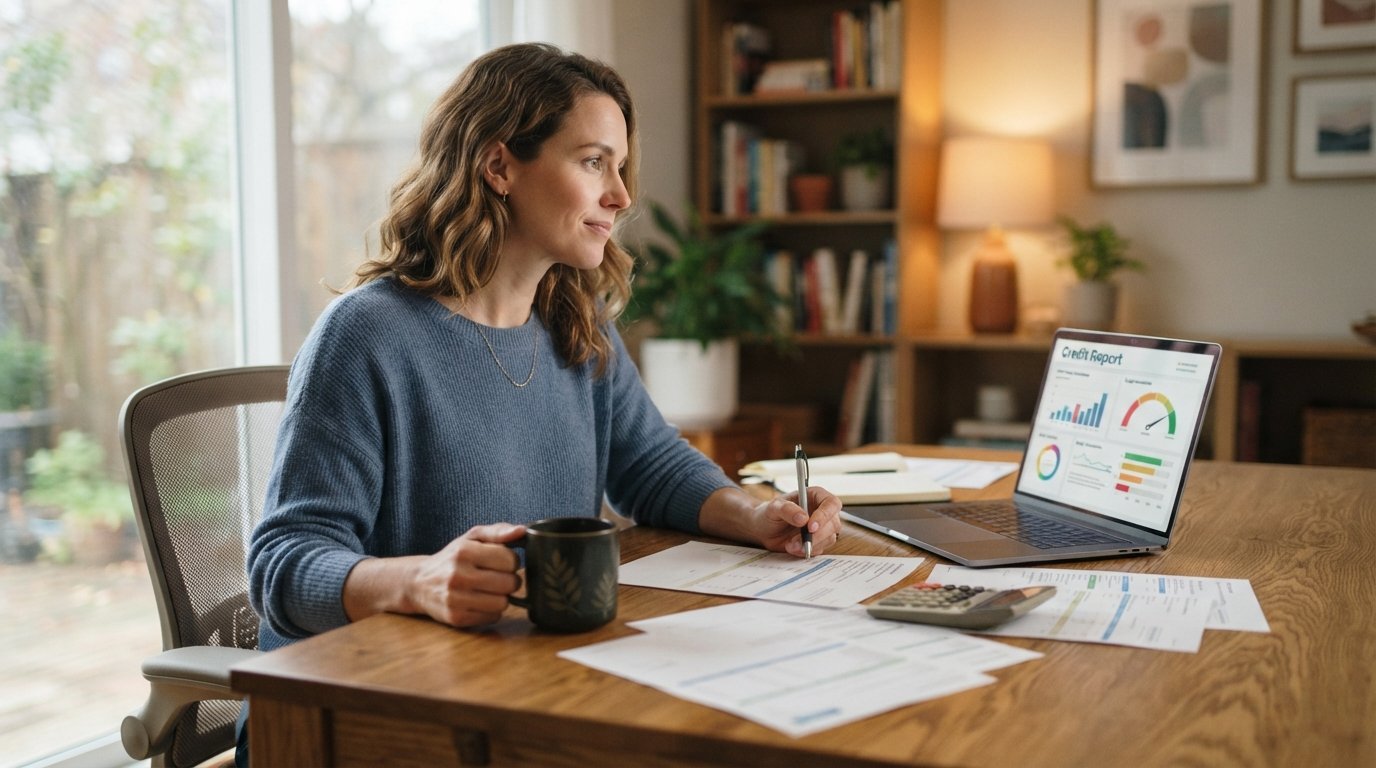
Before you can fix the problem, you need to know exactly what you are dealing with. Start by pulling your credit reports from all three major bureaus: Equifax, Experian, and TransUnion. You can get free reports weekly from AnnualCreditReport.com. Review each report carefully for the defaulted loan, any collection accounts, and any other negative items. Check for inaccuracies, such as wrong balances or duplicate entries, and dispute them if necessary.
Next, gather all documentation related to the defaulted loan, including the original loan agreement, payment history, and any correspondence with the lender or collector. Determine the current status of the debt: Is it still with the original lender, or has it been sold to a collection agency? Knowing who owns the debt is crucial for the next step, negotiation. Also, calculate how much you can realistically afford to put toward resolving the debt, whether through a lump sum or monthly payments.
Step 2: Negotiate a Repayment Plan or Settlement
Once you understand the debt, reach out to the lender or collection agency to discuss options. Many creditors are willing to work with borrowers who show a genuine willingness to repay. You might be able to set up a repayment plan that allows you to pay off the balance over time, often with reduced or waived fees and interest. Alternatively, you could negotiate a settlement for less than the full amount owed, especially if the debt has been sold to a collector who purchased it for pennies on the dollar.
When negotiating, be clear about your financial situation and what you can afford. Get any agreement in writing before making a payment. If you settle for less than the full balance, the forgiven amount may be reported as income to the IRS, so consult a tax professional. Also, ask the creditor to update your credit report to reflect the settled status or removal of the collection account in exchange for payment. While they are not obligated to do so, many will agree as part of the negotiation. For more strategies on managing bad credit, see our guide on bad credit personal loans.
Step 3: Reestablish Positive Payment History
Payment history is the most important factor in your credit score, so the key to rebuilding after a default is to demonstrate that you can consistently pay your bills on time. Start by ensuring all your current accounts, such as credit cards, utilities, and rent, are paid on time every month. If you have any accounts in collections, resolving them as described above will help, but the ongoing positive payment history on other accounts will gradually offset the negative information.
Consider opening a secured credit card or a credit builder loan to add positive tradelines. A secured card requires a cash deposit that serves as your credit limit, and it reports to the credit bureaus like a regular card. Use it for small purchases and pay the balance in full each month to avoid interest. A credit builder loan works differently: you make fixed payments into a savings account, and the lender reports those payments to the bureaus. Once the loan term ends, you receive the funds. Both options help you build a track record of on-time payments without the risk of running up debt.
Over 12 to 24 months, a consistent pattern of on-time payments can significantly improve your credit score. Be patient and avoid applying for multiple new credit accounts in a short period, as each application generates a hard inquiry that can temporarily lower your score. Instead, focus on managing the accounts you have responsibly and let time do its work.
Step 4: Use Secured Cards and Credit Builder Loans Wisely
Secured credit cards and credit builder loans are powerful tools for rebuilding credit, but they require discipline. With a secured card, it is easy to fall into the trap of spending more than you can repay, especially if you treat the deposit as available cash. Instead, use the card for a recurring expense like a streaming subscription or gas, and set up automatic payments to ensure the bill is paid on time and in full each month. Keep your credit utilization low, ideally below 30% of your credit limit, to avoid hurting your score.
Credit builder loans are similarly effective because they force you to save while building credit. However, they often come with fees or interest, so compare offers from different lenders, including local credit unions and online platforms. Make sure the lender reports to all three credit bureaus; otherwise, the loan will not help your credit. Also, be aware that some credit builder loans require a lump-sum deposit or have high origination fees, so read the terms carefully. When used correctly, these tools can be a stepping stone to better credit and eventually qualify you for unsecured credit cards and loans.
Step 5: Know When to Apply for New Credit
After a default, it is tempting to apply for a new loan or credit card as soon as your score ticks up a bit. However, applying too soon can backfire. Each hard inquiry stays on your report for two years and can lower your score by a few points. More importantly, if you are rejected, it adds another negative mark. A good rule of thumb is to wait at least 12 months after resolving the default and maintaining on-time payments before applying for new credit. For a mortgage, you may need to wait longer, typically two to four years after a major derogatory event, depending on the lender and loan program.
Before applying, check your credit score and reports to ensure everything is accurate and as positive as possible. Shop for rates from multiple lenders within a short window (14 to 45 days) to minimize the impact of inquiries. If you are considering a mortgage, you can get a free quote from ExpressMortgageQuotes to compare options from verified lenders. Also, be prepared to explain the default to underwriters; a written explanation showing that you have resolved the issue and learned from it can help your case.
Step 6: Monitor Progress and Stay Persistent
Rebuilding credit is a marathon, not a sprint. Set up a system to monitor your credit score and reports regularly, perhaps using free tools from Credit Karma or your bank. Watching your score improve can be motivating, and monitoring also helps you catch any errors or signs of identity theft early. Keep your credit utilization low, continue making all payments on time, and avoid closing old accounts, as the length of your credit history also matters.
If you have trouble managing payments, consider setting up automatic payments or reminders. Create a budget that prioritizes debt repayment and savings. Over time, the negative items will age off your report, and your positive payment history will carry more weight. Many people who default on a loan eventually recover and even achieve homeownership. The key is to stay persistent, learn from the experience, and make credit health a lifelong habit.
Rebuilding credit after a personal loan default requires patience and effort, but it is entirely possible. By understanding the damage, negotiating with creditors, and systematically building positive payment history, you can restore your creditworthiness and open doors to future financial opportunities. Start today with small, consistent steps, and you will see progress within months.