
Medical Debt Consolidation Options for Patients in 2026
Medical debt consolidation options for patients include negotiating bills, hospital payment plans, and personal loans. Learn how to reduce what you owe and protect your credit.
By Yara Adler
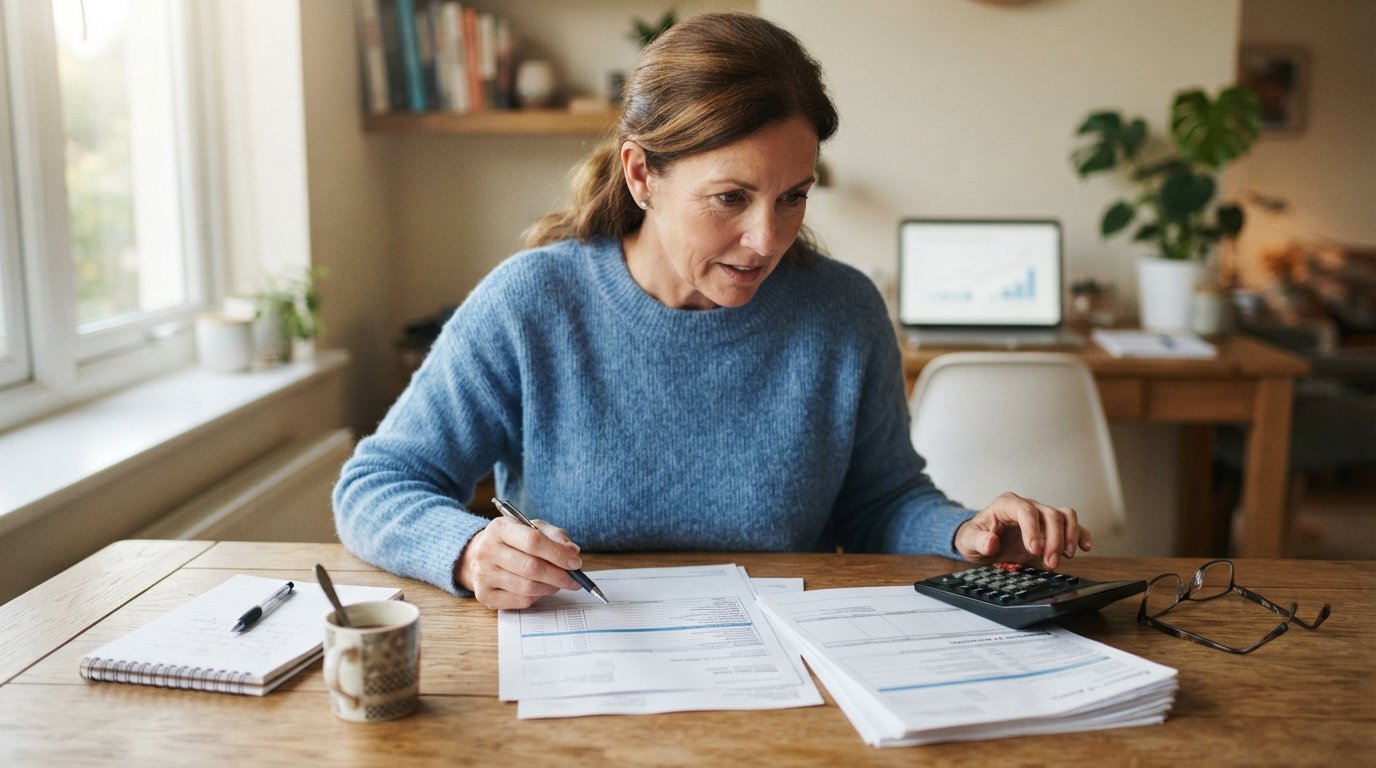
Hospital bills arrive with clinical precision, often stacked in a folder next to insurance explanation of benefits forms that seem written in another language. The balances can feel immovable, and the collection calls may start before you have even finished recovering. The good news is that you have more leverage than you might think. Medical debt is not like credit card debt. Providers often have flexibility that other creditors do not, and several consolidation paths exist that can lower your total out-of-pocket cost while protecting your credit score. This guide walks through the realistic medical debt consolidation options for patients, from negotiating itemized bills to using personal loans, so you can choose a strategy that fits your financial situation and your health needs.
Start with the Bill Itself: Itemize, Audit, and Negotiate
Before you consider any consolidation product, you need to know exactly what you owe and to whom. Medical billing errors are common. A 2024 study in a major medical journal found that nearly half of hospital bills contained at least one error. That is why the first step in any medical debt strategy is requesting an itemized bill. An itemized statement lists every single charge, from the cost of a bandage to the fee for each specialist who walked into your room. A summary bill only shows a lump sum, which makes it impossible to spot duplicate charges, incorrect procedure codes, or services you never received.
Once you have the itemized bill, compare it against your insurance explanation of benefits. Look for charges that your insurer already paid, services that were supposed to be covered under your plan, and any line items that seem out of proportion. If you find discrepancies, call the hospital's billing department and ask for a formal review. You can also ask for the billing codes and check them against the standard rates for your region. Many hospitals will reduce the balance if you point out errors, and some will offer a prompt-pay discount if you can pay a portion upfront.
Negotiation is not a confrontation. It is a conversation. Hospitals prefer to collect something rather than send a bill to collections, where they typically receive only a fraction of the original amount. When you call, be polite but firm. Ask about financial assistance programs, charity care, and any sliding-scale discounts based on income. Nonprofit hospitals are required by federal law to have financial assistance policies, and many for-profit hospitals offer similar programs. If you qualify, you could see a significant portion of your bill erased outright.
Interest-Free Hospital Payment Plans and Zero-Interest Medical Credit Cards
If you cannot pay the remaining balance in full, the next step is to ask about an interest-free payment plan directly through the hospital. Most hospitals offer internal payment plans that break the balance into manageable monthly installments without charging interest. These plans are often more flexible than outside financing because the hospital is not trying to profit from interest. You can typically negotiate the monthly amount and the length of the plan. The key is to get the agreement in writing, including the exact payment schedule and a statement that no interest will accrue.
Another option that gets a lot of attention is the medical credit card, often marketed as a zero-interest card for health care expenses. These cards typically offer a promotional period of 6 to 24 months with no interest, but the devil is in the details. If you do not pay the full balance before the promotional period ends, you may be charged deferred interest, which means interest accrues retroactively from the date of purchase. That can turn a $2,000 bill into a much larger debt. Medical credit cards can also have high regular interest rates after the promo period, and they may not report to credit bureaus in a way that helps your score. They can be useful if you are absolutely certain you can pay off the balance within the promotional window, but for most patients, they carry more risk than benefit.
Before signing up for any medical credit card, read the terms carefully. Look for the regular APR, the length of the deferred interest period, and whether the card reports to the major credit bureaus. If the card does not report positive payment history, it will not help you build credit, and if you miss a payment, it could hurt you. In many cases, a hospital payment plan or a personal loan is a safer bet.
When a Personal Loan Makes Sense for Medical Balances
A personal loan can be a smart consolidation tool for medical debt, but it is not right for everyone. The main advantage is that you can combine multiple medical bills into one monthly payment, often at a lower interest rate than what you would pay on a credit card. Personal loans are unsecured, meaning you do not have to put up collateral like a car or home. They also have fixed terms, so you know exactly when the debt will be paid off. That predictability can be a relief when you are juggling several bills from different providers.
However, personal loans come with their own risks. You are converting a medical debt, which often has flexible repayment options and may not be reported to credit bureaus in the same way, into a standard consumer debt. That means if you fall behind, it can damage your credit score more severely. You also lose the ability to negotiate directly with the hospital, because the loan is paid off and the hospital is out of the picture. Before you take out a personal loan, make sure you have exhausted the hospital's own financial assistance and payment plan options. If you have already negotiated the bill down and still need a manageable way to pay, a personal loan can be a practical solution.
When comparing personal loans, focus on the annual percentage rate (APR), which includes both the interest rate and any fees. Also check the loan term, the monthly payment, and whether there are prepayment penalties. Credit unions and online lenders often offer competitive rates for borrowers with good credit. If your credit score is lower, you may still qualify, but the interest rate could be high. In that case, it may be better to stick with a hospital payment plan or seek help from a nonprofit credit counseling agency. For those who are also exploring broader debt consolidation, our guide on best debt consolidation loans explains how to compare offers and avoid common pitfalls.
Protecting Your Credit While Medical Debt Is Disputed
Medical debt can appear on your credit reports, but recent changes by the major credit bureaus have reduced its impact. As of 2023, the three national credit bureaus no longer include medical collections under $500 on credit reports, and they have extended the waiting period before unpaid medical bills appear. However, larger medical debts can still show up and affect your score. If you are disputing a bill, you have rights under the Fair Credit Reporting Act. You can file a dispute with the credit bureaus and directly with the collection agency. While the dispute is open, the collection agency must mark the account as disputed, and you should keep records of all communication.
One of the most important steps is to avoid letting a disputed bill go to collections in the first place. If you are actively negotiating with the hospital, ask them to hold off on sending the account to collections while you work out a payment plan. Get this agreement in writing. If the bill does end up in collections, you can still negotiate. Collection agencies often accept less than the full amount, especially if you can pay a lump sum. You can also ask them to delete the collection from your credit report in exchange for payment, though they are not required to agree. Always get any agreement in writing before you pay.
If you are struggling with medical debt and your credit score is already damaged, you may need to rebuild it over time. Paying your other bills on time, keeping credit card balances low, and avoiding new credit applications can help. If you are considering a mortgage or refinancing in the future, medical debt can affect your debt-to-income ratio, so reducing it before you apply is wise. For homeowners, a cash-out refinance or home equity loan can be used to pay off medical debt, but this converts unsecured debt into debt secured by your home, which carries its own risks. If you are exploring that route, resources like RefinancingCo provide educational tools and calculators to help you understand your options.
Steps to Take If You Are Facing Medical Debt Right Now
If you are feeling overwhelmed, it helps to have a clear plan. Here is a step-by-step approach that you can follow:
- Request an itemized bill and review it for errors. Compare it to your insurance explanation of benefits and your policy coverage. This is the foundation of any negotiation.
- Contact the hospital's financial assistance office. Ask about charity care, sliding-scale discounts, and interest-free payment plans. Nonprofit hospitals are required to offer financial assistance, and many for-profit hospitals do as well.
- Negotiate the remaining balance. If you find errors or cannot afford the bill, ask for a reduction. Be prepared to provide documentation of your income and expenses.
- Consider consolidation only after you have exhausted other options. If you have multiple medical bills and need one manageable payment, compare personal loans, but be aware of the risks.
- Protect your credit. Keep records of all disputes and agreements. If a bill goes to collections, negotiate and get any deletion agreement in writing.
This sequence matters because it prioritizes the least expensive and least risky solutions first. Many patients jump straight to a credit card or loan without realizing that the hospital itself may be willing to reduce the bill or offer a zero-interest plan. By working through these steps, you can avoid unnecessary interest and fees.
Another often overlooked option is hiring a medical billing advocate. These professionals work on your behalf to negotiate with hospitals and insurance companies. They typically charge a percentage of the savings or an hourly fee. For complex bills or denied insurance claims, an advocate can be worth the cost. You can also seek help from a nonprofit credit counseling agency, which can help you create a budget and negotiate with creditors. Be wary of for-profit debt settlement companies that charge high fees and may not deliver results.
Finally, remember that medical debt is not a moral failing. It is a financial circumstance that millions of Americans face. You have rights, and you have options. By taking a proactive, informed approach, you can reduce what you owe and protect your financial future. Whether you negotiate directly, set up a payment plan, or use a personal loan to consolidate, the key is to act before the debt snowballs.
If you are considering a personal loan or refinancing to manage medical debt, start by gathering quotes from multiple lenders. LoanFinancing.com offers a free quote comparison tool that connects you with national lenders, so you can see rates and terms side by side. It is an educational resource, not a lender, but it can help you understand what is available. Taking the time to compare offers can save you hundreds or even thousands of dollars over the life of the loan.