
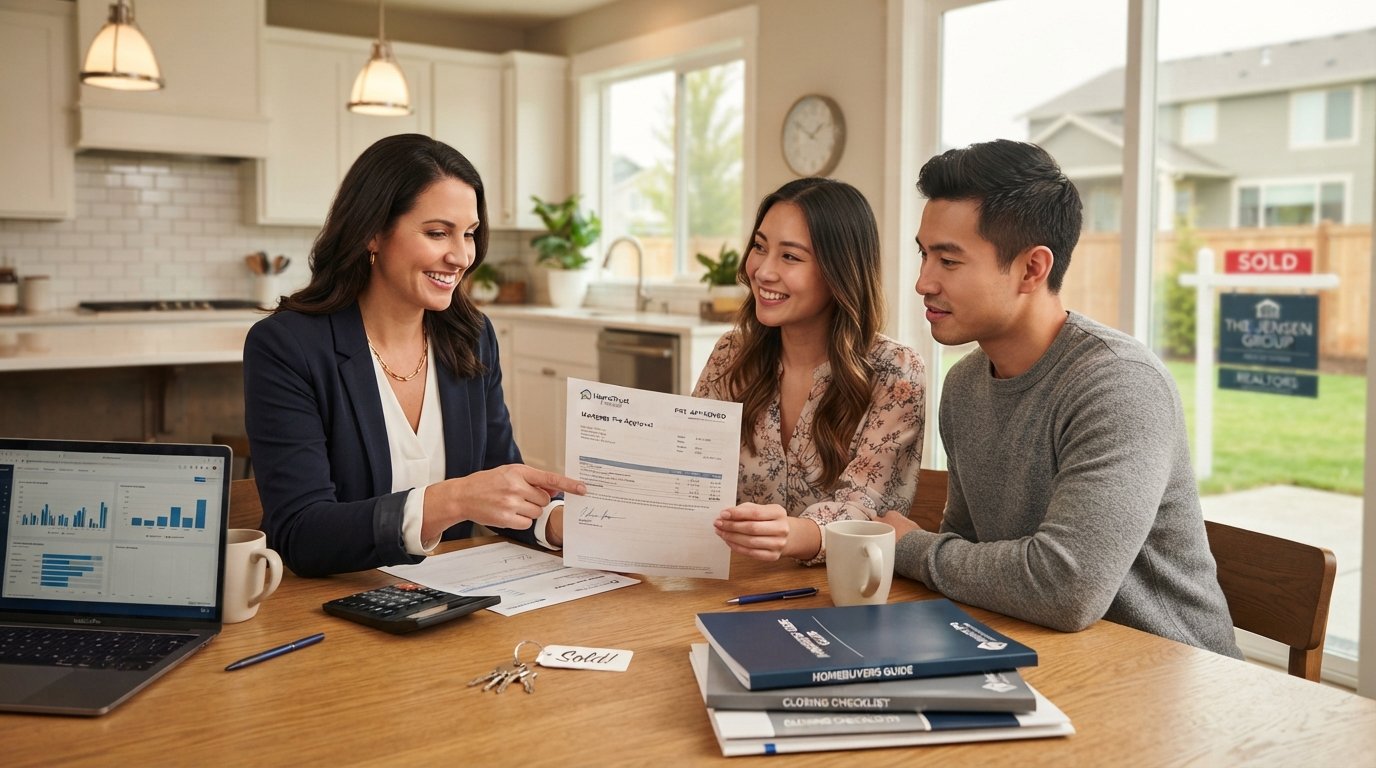
Mortgage Application Process from Pre-Approval to Closing
Master the mortgage application process from pre-approval to closing with our step-by-step guide. Learn how to avoid delays and secure your best rate.
By Hannah Reed
Buying a home is one of the most significant financial decisions you will ever make, and the mortgage application process from pre-approval to closing can feel like a complex maze of paperwork, deadlines, and financial scrutiny. Understanding each stage before you start can transform a stressful ordeal into a manageable, predictable journey. Whether you are a first-time buyer or a seasoned homeowner looking to refinance, knowing what lenders expect and how to prepare will save you time, money, and frustration. This guide walks you through every milestone, from the initial pre-approval letter to the final closing disclosure, so you can move forward with confidence.
Understanding Pre-Approval: Your Financial Foundation
Pre-approval is the first serious step in the mortgage application process from pre-approval to closing. Unlike pre-qualification, which is a quick, informal estimate based on self-reported information, pre-approval involves a lender verifying your income, assets, debts, and credit history. This verification typically requires submitting pay stubs, W-2s, tax returns, bank statements, and authorization for a hard credit pull. The result is a conditional commitment from the lender stating how much they are willing to lend you, subject to final underwriting and property appraisal.
Why does pre-approval matter so much? Sellers and real estate agents take you seriously when you have a pre-approval letter in hand. It signals that a lender has already scrutinized your finances and believes you are a low-risk borrower. In competitive markets, buyers without pre-approval often lose out to those who have it. Moreover, pre-approval gives you a clear budget range, preventing you from falling in love with homes you cannot afford.
To get pre-approved, you will need to gather several documents. Lenders typically ask for:
- Recent pay stubs covering the last 30 days
- W-2 forms from the past two years
- Federal tax returns for the past two years (including schedules)
- Bank and investment account statements for the last two to three months
- Proof of identity (driver's license or passport)
- Information on existing debts, including car loans, student loans, and credit card balances
Once submitted, the lender runs a hard credit inquiry and reviews your debt-to-income ratio (DTI). A DTI below 43% is generally preferred, though some loan programs allow higher ratios with compensating factors. If everything checks out, you receive a pre-approval letter that is typically valid for 60 to 90 days. Remember, pre-approval is not a guarantee; it is conditional on the property appraisal, title search, and final underwriting. Still, it is the essential first milestone in the mortgage application process from pre-approval to closing.
During this stage, it helps to compare offers from multiple lenders. Even a small difference in interest rate can translate into tens of thousands of dollars over the life of the loan. Using a platform like RateChecker can give you real-time rate comparisons and financial tools to see how different scenarios affect your monthly payment. For a broader walkthrough of the entire loan application journey, including personal loans and other financing types, see our guide on navigating the loan application process.
House Hunting and Making an Offer
With pre-approval secured, you can begin house hunting with a clear price ceiling. Your real estate agent will help you identify properties that fit your budget and lifestyle. When you find a home you love, you make an offer. The offer includes not just the purchase price but also contingencies, such as financing, inspection, and appraisal contingencies. These contingencies protect you if something goes wrong during the process.
Once the seller accepts your offer, you enter the contract phase. At this point, you typically submit a formal mortgage application to your chosen lender. This is a more detailed version of the pre-approval application, and it locks in the specific property you intend to purchase. The clock starts ticking on your loan processing timeline, which usually takes 30 to 45 days from contract to closing.
Formal Mortgage Application: The Paperwork Intensifies
The formal mortgage application is the heart of the mortgage application process from pre-approval to closing. You will complete a standardized form (often the Uniform Residential Loan Application, or URLA) that captures your employment history, income, assets, liabilities, and other financial details. Your loan officer will guide you through the required disclosures, including the Loan Estimate, which outlines your estimated interest rate, monthly payment, and closing costs.
Within three business days of receiving your application, the lender must provide a Loan Estimate. This document is critical for comparing offers and understanding the total cost of borrowing. It includes:
- Loan amount and interest rate
- Monthly principal and interest payment
- Estimated taxes, insurance, and assessments
- Closing costs, including origination fees, appraisal fees, and title charges
- Annual percentage rate (APR), which reflects the true cost of the loan
Review the Loan Estimate carefully. If you see charges that seem high or unclear, ask your loan officer for an explanation. This is also the time to decide whether to lock your interest rate. A rate lock protects you from market fluctuations for a specified period, typically 30 to 60 days. If rates are rising, locking can provide peace of mind; if they are falling, you might choose to float your rate and hope for a better deal.
Processing and Underwriting: The Behind-the-Scenes Work
After you submit your formal application, your file moves to the processing stage. A loan processor verifies all the information you provided, orders the appraisal, requests a title search, and assembles a complete loan package. The processor acts as a liaison between you, the lender, and third parties such as appraisers and title companies.
The appraisal is a key component. An independent appraiser evaluates the property to determine its fair market value. The lender will not lend more than the appraised value (or a certain percentage of it), so if the appraisal comes in low, you may need to renegotiate the purchase price or bring more cash to the table. Similarly, the title search ensures there are no liens or ownership disputes that could jeopardize the lender's investment.
Once the file is complete, it goes to underwriting. Underwriters are the decision-makers who assess risk. They review your credit history, income stability, debt load, and the property's value. They may request additional documentation, such as letters of explanation for gaps in employment or large deposits. Responding promptly to these requests is crucial to avoid delays.
Underwriting can take anywhere from a few days to a couple of weeks, depending on the complexity of your file and the lender's workload. If the underwriter approves your loan with conditions, you must satisfy those conditions before final approval. Common conditions include proof of homeowner's insurance, a clear termite inspection, or updated pay stubs.
Final Approval and Closing Preparation
Once underwriting gives the green light, you receive a final approval (also called a clear-to-close). This means the lender is ready to fund the loan. At this point, you will receive a Closing Disclosure, which is a five-page document that details the final terms of your loan, including the exact interest rate, monthly payment, and closing costs. You should compare the Closing Disclosure to your initial Loan Estimate to ensure there are no unexpected changes. If there are significant differences, ask your lender to explain them before you proceed.
Before closing day, you will need to arrange a cashier's check or wire transfer for your down payment and closing costs. You should also conduct a final walk-through of the property to confirm it is in the agreed-upon condition. Any repairs negotiated during the inspection should be completed, and the home should be free of debris and personal belongings.
Closing day itself is a formal meeting where you sign the final paperwork. You will sign the promissory note, the deed of trust (or mortgage), and other legal documents. Once signed, the lender disburses the funds, and the title is transferred to your name. Congratulations, you are now a homeowner!
Common Pitfalls and How to Avoid Them
The mortgage application process from pre-approval to closing is not without potential obstacles. One of the most common mistakes is making major financial changes during the process. Changing jobs, taking on new debt, or making large purchases can derail your approval. Lenders verify your financial situation right up to closing, so it is best to keep everything stable.
Another pitfall is failing to respond to lender requests promptly. Underwriters often need additional documents, and delays in providing them can push back your closing date. Stay in close contact with your loan officer and processor, and check your email regularly.
Finally, do not ignore the fine print. The Loan Estimate and Closing Disclosure are not just formalities; they contain important details about your loan's costs and terms. If something does not look right, speak up. A reputable lender will be happy to clarify.
How LoanFinancing.com Can Help
Navigating the mortgage application process from pre-approval to closing requires reliable information and access to competitive rates. LoanFinancing.com is an educational resource and quote-comparison platform that connects you with a network of national lenders. You can use their free mortgage calculator to estimate payments, read expert articles on home purchase, refinance, and home equity options, and request personalized quotes from multiple lenders. While LoanFinancing.com does not originate loans, it provides the tools and knowledge you need to make informed decisions. Submitting an online application through their platform implies consent to be contacted by phone or email by network members, so you can compare offers at your convenience.
By understanding each stage and preparing thoroughly, you can turn the mortgage application process from pre-approval to closing into a smooth, successful experience. Take your time, ask questions, and use trusted resources to guide you every step of the way.