Personal Loan APR vs Interest Rate: What Is the Difference?
The interest rate covers the cost of borrowing, but the APR includes fees. Knowing the personal loan APR vs interest rate difference can save you hundreds.
By Sloane Parker
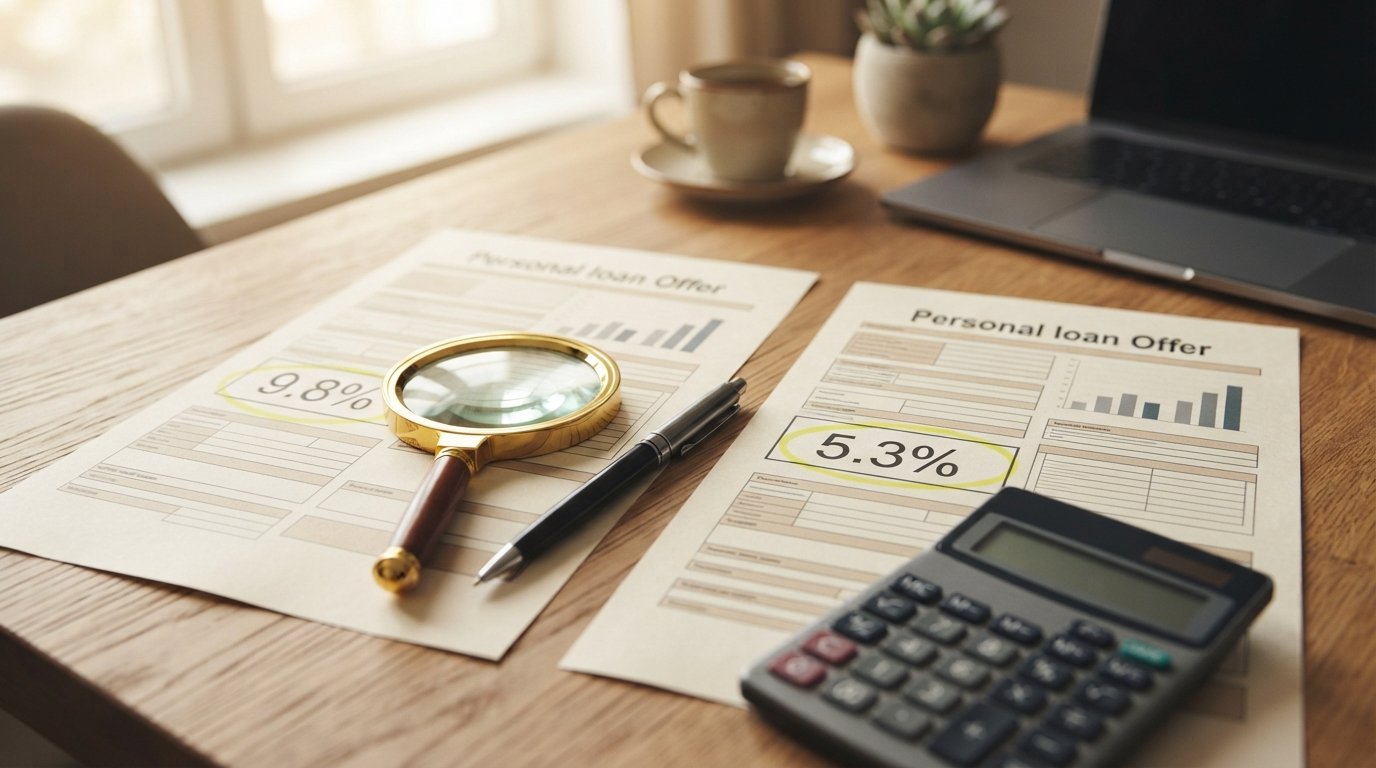
You spot two personal loan offers side by side. One advertises a 6.99% rate, the other 7.49%. The lower number seems like the obvious winner, until you notice the first loan carries a 5% origination fee while the second has no fee at all. Suddenly, the cheaper-looking option may not be cheaper once you sign. That gap between the advertised rate and the real cost is exactly where the personal loan APR vs interest rate question becomes practical, not academic. Understanding the difference helps you compare offers accurately, avoid surprise costs, and choose a loan that fits your budget over the full repayment term.
Interest Rate vs APR: The Core Definitions
The interest rate is the price a lender charges for borrowing the principal balance. It is the percentage applied to your outstanding loan amount to calculate the finance charge you pay each period. If you borrow $10,000 at a 7% interest rate over five years, the rate determines how much of each monthly payment goes toward interest versus principal. The rate does not include fees; it is purely the cost of renting the money.
The annual percentage rate, or APR, is a broader measure. It expresses the total cost of credit as a yearly rate, folding in both the interest rate and certain upfront costs such as origination fees, documentation fees, and closing costs. Because those fees are spread across the loan term and expressed as an annual rate, the APR is almost always higher than the interest rate. When borrowers ask about personal loan APR vs interest rate, the short answer is this: the interest rate tells you what the money costs, while the APR tells you what the loan costs.
This distinction matters because lenders are required to disclose the APR under the Truth in Lending Act, giving you a standardized number to compare offers. However, the APR is not a perfect tool in every situation. It assumes you keep the loan for the full term and make every payment on schedule. If you repay early or refinance, the actual cost may differ from the advertised APR. Still, for most borrowers comparing fixed-rate personal loans, the APR is the single most useful number on the disclosure.
What Each Number Actually Includes
To see why two offers with identical interest rates can carry different APRs, it helps to break down what each figure captures. The interest rate is narrow and simple: it is the annual cost of the principal, set by the lender based on your credit profile, income, debt-to-income ratio, and the loan term. The APR is cumulative and includes several components that vary by lender and loan product.
Here is what typically gets baked into each figure:
- Interest rate: The base cost of borrowing, applied to the principal balance over the life of the loan. It does not include fees.
- APR: The interest rate plus origination fees, documentation fees, and other finance charges, expressed as a single annualized percentage.
- Excluded from APR: Late payment fees, optional insurance products, and other contingent charges that may or may not apply to your situation.
- Term sensitivity: A longer loan term spreads fees over more years, which can lower the APR slightly even though you pay more total interest.
Because the APR includes fees that the interest rate ignores, it gives you a more complete picture of the loan's cost. But it also means the APR can be manipulated by extending the loan term or adjusting fee structures. A lender offering a slightly higher interest rate with no fees may actually deliver a lower APR than a competitor with a lower rate and a hefty origination fee. That is why comparing APRs, not just rates, is the smarter move when shopping for a personal loan.
How Origination Fees Get Folded Into APR
Origination fees are the most common reason the APR on a personal loan offer exceeds the advertised interest rate. These fees compensate the lender for processing and underwriting the loan, and they typically range from 1% to 8% of the loan amount, depending on the lender, your creditworthiness, and the loan term. On a $15,000 loan, a 5% origination fee equals $750, which is deducted from the amount you receive or added to the balance you repay.
The APR calculation spreads that $750 across the loan term and converts it into an annual rate. On a three-year loan, the fee adds roughly 2.5 to 3 percentage points to the APR, depending on how the fee is structured. On a five-year loan, the same fee adds less per year because it is spread over a longer period. This is why a loan with a 7% interest rate and a 5% origination fee might show an APR of 10.5%, while a no-fee loan at 8.5% interest shows an APR of 8.5%. The no-fee loan is the better deal, even though its interest rate is higher.
Not all fees are treated the same. Prepaid finance charges, such as origination fees and documentation fees, are included in the APR. Third-party fees, such as appraisal costs (rare for personal loans) or optional credit insurance, may be excluded. Always read the loan estimate or disclosure carefully to see which fees are included in the APR and which are not. If a lender advertises a low rate but charges a large origination fee, the APR will reveal the true cost.
Why Two Offers With the Same Rate Can Have Different APRs
Imagine two lenders both quoting you a 9% interest rate on a $20,000 five-year personal loan. Lender A charges a 2% origination fee ($400) and no other fees. Lender B charges a 6% origination fee ($1,200) but offers a slightly lower interest rate of 8.75%. At first glance, Lender B's lower rate looks attractive, but its APR will be significantly higher because of the larger fee. This scenario plays out constantly in the personal loan market, and it is the reason the Consumer Financial Protection Bureau encourages borrowers to compare APRs rather than rates alone.
Several factors can cause APRs to diverge even when interest rates are identical:
- Origination fee size: A 1% fee versus a 6% fee can shift the APR by several percentage points.
- Loan term: A longer term spreads fees over more years, often lowering the APR slightly, but you pay more total interest.
- Fee structure: Some lenders deduct fees from the principal (reducing the amount you receive), while others add fees to the balance (increasing what you repay).
- Prepayment penalties: Though rare on personal loans, penalties can affect the effective cost if you plan to repay early.
The lesson is straightforward: never compare personal loans using interest rates alone. Always look at the APR, and then dig into the fee breakdown to understand why the APR is what it is. A loan with a slightly higher interest rate but no fees may save you hundreds of dollars over the life of the loan.
If you are exploring personal loan options, understanding eligibility rules can help you anticipate which offers you qualify for and how your credit profile affects both the rate and the APR. Our guide on personal loan eligibility rules for fast approval walks through the key criteria lenders use, from income verification to debt-to-income ratios.
How to Use APR When Comparing Personal Loan Offers
The APR is your best single tool for comparing personal loan offers, but it works best when you use it alongside other factors. Start by gathering loan estimates from at least three lenders. Each estimate should clearly show the interest rate, the APR, the origination fee, and the total finance charge over the life of the loan. With those numbers in hand, you can compare apples to apples.
Follow this practical framework when evaluating offers:
- Compare APRs first: Rank offers by APR, not interest rate. The lowest APR usually represents the lowest total cost, assuming you keep the loan for the full term.
- Check the fee breakdown: Identify which fees are included in the APR and which are not. A low APR with hidden fees is not a good deal.
- Calculate total repayment: Multiply your monthly payment by the number of payments to see the total amount you will repay. This reveals the real cost in dollars.
- Consider your repayment plan: If you plan to repay early, ask whether the lender charges prepayment penalties and how early repayment affects the total cost.
- Evaluate the lender's reputation: A slightly higher APR from a lender with strong customer service and transparent terms may be worth more than a rock-bottom APR from a lender with poor reviews.
After you rank the offers, factor in convenience and flexibility. Some lenders offer fast funding, flexible payment dates, or hardship programs. These features do not show up in the APR, but they affect the overall value of the loan. The goal is to find the lowest-cost loan that also meets your practical needs.
For homeowners who are also considering mortgage financing, it helps to understand how APR works in that context as well. Resources like MortgageZone provide educational tools and calculators that explain mortgage APRs, closing costs, and lender comparisons, which can be useful if you are weighing a personal loan against a home equity option.
When the Interest Rate Alone Is the Better Comparison Metric
There are situations where the interest rate is the more relevant number. If you are comparing two loans with identical fee structures (for example, both have no origination fee), the interest rate and APR will be nearly the same, and the rate is easier to interpret. Similarly, if you plan to repay the loan very quickly, the upfront fee has less time to affect the APR, and the interest rate may better reflect your actual cost.
Short-term borrowers should pay close attention to fees. If you borrow $5,000 for six months and pay a 3% origination fee ($150), that fee represents a significant portion of the total cost, even though the APR calculation spreads it over a year. In this case, comparing the total dollar cost of fees plus interest is more meaningful than comparing APRs. The same logic applies to borrowers who expect to refinance or repay early: the APR assumes a full-term repayment, so it may overstate or understate your actual cost.
Additionally, some lenders offer rate discounts for autopay or loyalty programs. These discounts affect the interest rate but may or may not be reflected in the APR. If you qualify for a discount, compare the adjusted rates and APRs to see the true impact. The key is to use the APR as your default comparison tool, but switch to the interest rate or total dollar cost when fees are uniform, the term is very short, or you plan to repay ahead of schedule.
Common Misconceptions About APR and Interest Rate
One widespread misconception is that the APR is always the number you pay. In reality, the APR is a standardized measure designed for comparison, not a precise prediction of your cost. It assumes you make every payment on time and keep the loan for the full term. If you miss a payment, incur late fees, or repay early, your actual cost will differ. Another misconception is that a lower interest rate always means a better deal. As the earlier example showed, a loan with a lower rate but high fees can cost more than a loan with a higher rate and no fees.
Borrowers also sometimes confuse the APR with the monthly payment. The APR does not tell you what you will pay each month; it tells you the annualized cost of the loan. Your monthly payment depends on the loan amount, interest rate, and term. Two loans with the same APR can have very different monthly payments if their terms differ. Always calculate the monthly payment and total repayment amount before committing.
Finally, some borrowers assume that because the APR includes fees, it is always the most accurate number. That is true for most fixed-rate personal loans, but not for every product. Adjustable-rate loans, for example, may have an APR that assumes a rate that changes over time, making it less reliable. For personal loans, which are typically fixed-rate, the APR is generally reliable, but it is still worth reading the fine print to confirm which fees are included.
Putting It All Together: A Smarter Borrowing Strategy
Understanding the personal loan APR vs interest rate difference gives you a practical advantage when shopping for a loan. Use the APR as your primary comparison tool, but do not stop there. Request loan estimates from multiple lenders, review the fee breakdown, calculate the total repayment amount, and consider how long you plan to keep the loan. If you are comparing offers with identical fee structures, the interest rate may be sufficient, but if fees vary, the APR is essential.
Before you apply, check your credit report for errors, gather your income documentation, and use prequalification tools to see estimated rates without a hard credit pull. Prequalification can help you narrow the field and focus on lenders that are likely to offer competitive APRs. Once you have offers in hand, compare them side by side using the framework outlined above, and do not let a low advertised rate distract you from a high APR.
The bottom line is simple: the interest rate tells you what the money costs, and the APR tells you what the loan costs. When you compare personal loans, the APR is usually the more honest number because it captures fees that the interest rate hides. By focusing on the APR and understanding its components, you can avoid surprise costs and choose a loan that genuinely fits your budget.