
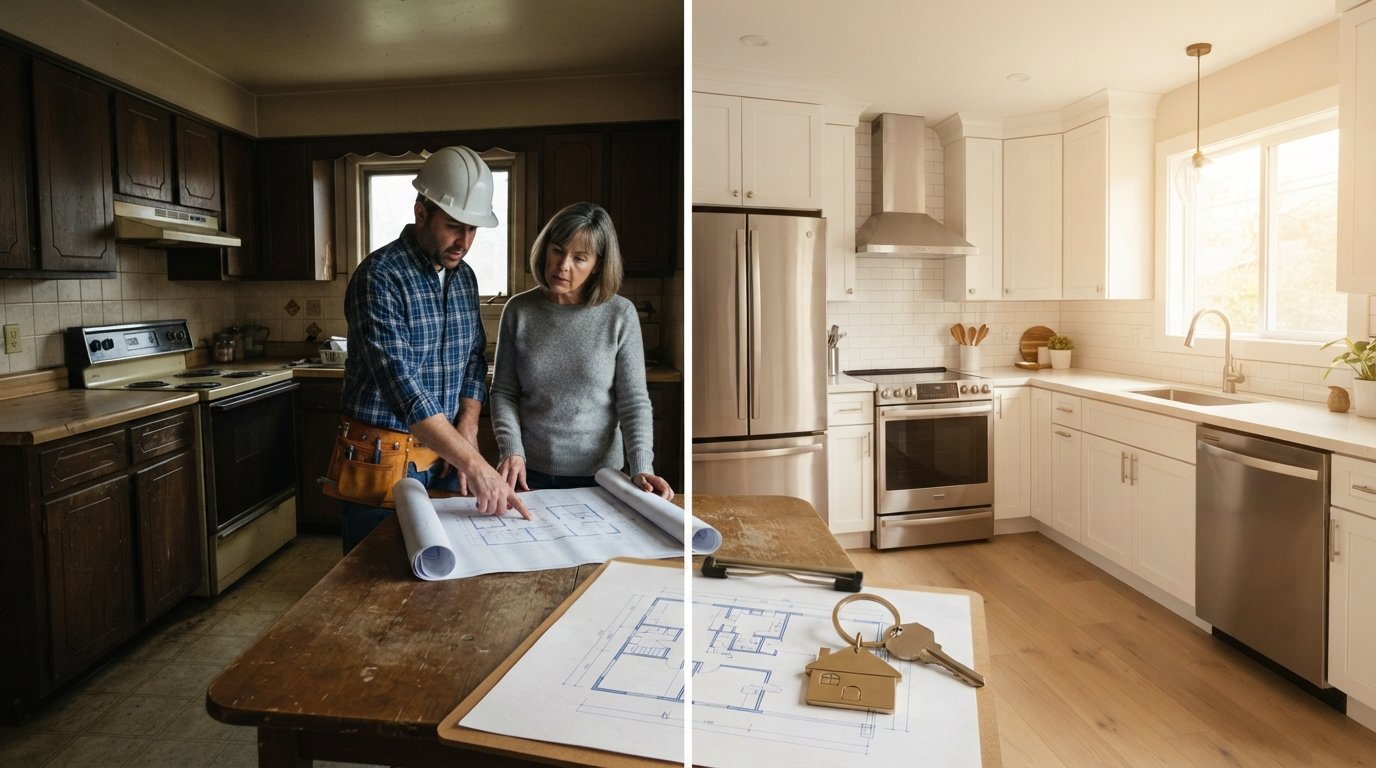
Renovation Mortgage vs Fixer Upper With a Conventional Loan
Compare a renovation mortgage to buying a fixer upper with a conventional loan, including draw schedules, cash reserves, and total project cost.
By Yara Adler
You have found the perfect neighborhood and a house with good bones, but the kitchen is stuck in 1985 and the roof is older than you are. Now you face a choice that trips up even seasoned buyers: should you roll the purchase and the repairs into one renovation mortgage, or buy the place as-is with a conventional loan and renovate later? The answer depends on your cash reserves, your tolerance for construction dust, and how the lender views a home that needs work. This guide breaks down both paths so you can compare total project cost, timing, and risk before you make an offer.
How Renovation Loans Bundle Purchase and Improvement Costs
A renovation mortgage, often called a 203(k) or a HomeStyle loan, lets you finance the purchase price plus the cost of repairs in a single loan. The lender bases the loan amount on the home's projected value after the work is complete, not the current condition. That means you can buy a distressed property and borrow for the upgrades without needing a separate construction loan or a second closing. The appeal is obvious: one application, one closing, and one monthly payment covering both the house and the improvements.
These loans typically require a detailed scope of work and a licensed contractor. The lender orders an appraisal that includes the as-is value and the after-improved value, then holds back a portion of the funds in an escrow account. As the work progresses, the contractor requests draws, and the lender releases money in stages after inspecting the completed work. This protects the lender from paying for unfinished jobs, but it also means you cannot simply hand a contractor a lump sum and hope for the best. The process is more structured than a standard purchase, and that structure is both a safeguard and a source of frustration for buyers who want speed.
One major advantage is that the renovation budget is set before you close. You know the total cost of the project upfront, and the lender's appraisal confirms the value supports the investment. If you are buying a home with a low credit score, a renovation loan may still be an option, but you will need to meet the lender's credit and income requirements, which can be stricter than a conventional loan. In our guide on loan financing for a low credit score, we explain how to assess your eligibility before you apply. The key takeaway is that renovation loans are not a magic workaround for poor credit; they are a financing tool that rewards borrowers with stable income and a realistic budget.
Another benefit is that the renovation costs are financed over the life of the loan, often 30 years, rather than paid out of pocket or charged to a high-interest credit card. That can make a major remodel more affordable on a monthly basis. However, you will pay interest on the renovation funds, and the lender may require a contingency reserve of 10 to 20 percent of the repair budget to cover surprises. That reserve is not free money; it is added to your loan balance and must be justified if you use it. If you do not use it, it may be applied to your principal, but you still borrowed it.
Conventional Financing on a Home Needing Repairs and Appraisal Conditions
A conventional loan is not designed for a house that needs significant work. The lender's appraisal is based on the home's current condition, and appraisers are required to note any health and safety issues, structural problems, or items that affect marketability. If the appraiser flags a leaking roof, peeling paint, or a broken furnace, the lender may condition the loan on those repairs being completed before closing. In a competitive market, that condition can kill the deal, because sellers rarely want to make repairs for a buyer's lender.
Conventional loans also have minimum property standards. The home must be safe, sound, and structurally intact. Cosmetic issues like outdated kitchens or worn carpet are usually acceptable, but anything that affects the home's habitability or value can become a sticking point. If the appraisal comes in lower than the purchase price because of the needed repairs, you may need to bring more cash to the table or renegotiate. This is why buying a fixer upper with a conventional loan works best when the repairs are truly cosmetic and the home is already livable. If the house needs a new roof or foundation work, a conventional lender will likely require those repairs to be completed before you close, which puts you in the position of paying for them out of pocket or walking away.
That said, a conventional loan can be a smart choice if you have cash reserves and want to renovate on your own timeline. You buy the home as-is, move in, and tackle projects as your budget allows. You are not bound by a lender's draw schedule or contractor approval process. You can do some of the work yourself, choose your own materials, and change your mind mid-project without asking a loan servicer for permission. The trade-off is that you bear all the risk and all the upfront cost, and you may face higher interest rates on any secondary financing you use to fund the renovations.
Another consideration is that conventional loans often have lower fees and faster closing times than renovation loans. If the home is in decent shape and you have a clear plan for the upgrades, a conventional loan plus a home equity line of credit after closing can be a flexible way to finance improvements. You can tap the equity you build through the purchase and then use a HELOC to fund the work. This approach requires you to have enough equity after closing, and it means two separate loan products, but it gives you more control over the renovation process. For buyers who are handy and patient, this can be the more cost-effective route.
Draw Schedules and Contractor Requirements
Renovation loans come with a draw schedule, which is a timeline for releasing funds as work is completed. The lender typically requires an initial draw at closing to cover materials and startup costs, then subsequent draws after inspections confirm progress. The contractor must be licensed, insured, and approved by the lender. You cannot hire your cousin who does odd jobs on the weekend unless he meets the lender's requirements, which usually include a valid license, liability insurance, and a written contract. This is a common source of friction for buyers who want to use a friend or a small independent contractor.
The draw schedule also affects your timeline. Each draw requires an inspection, and inspections take time. If the contractor is slow to submit a draw request or the inspector is backed up, the project can stall. You may also be responsible for paying the contractor for work that has been completed but not yet reimbursed by the lender, depending on the contract terms. That means you need a cash buffer to cover gaps between draws. The lender will typically require a contingency reserve, but that reserve is for unexpected costs, not for cash flow gaps. You need to plan for both.
Conventional loans do not have draw schedules or contractor approval requirements. You can hire anyone you want, pay them however you want, and work at your own pace. You can also do the work yourself if you are capable. That flexibility is a major advantage for buyers who want to save money on labor or who have a specific contractor in mind. However, you also lose the lender's oversight, which means you are solely responsible for ensuring the work is done correctly and that the contractor is reputable. If something goes wrong, you have no lender-backed recourse.
Cash Reserves and Contingency Budgeting for Overruns
Both paths require cash reserves, but the amounts and purposes differ. With a renovation loan, the lender will require a contingency reserve of 10 to 20 percent of the repair budget. This reserve is included in the loan amount and is held in escrow. If the project goes over budget, you can request a release from the reserve, but you must provide documentation and the lender must approve. If the reserve is not enough, you will need to cover the overage out of pocket. Lenders also typically require you to have cash reserves for mortgage payments, usually two to six months of principal, interest, taxes, and insurance, after closing. That is separate from the contingency reserve.
With a conventional loan, you need cash for the down payment, closing costs, and the renovations themselves. If you are buying a fixer upper, you should budget at least 10 to 20 percent of the purchase price for repairs, and that is before you discover the hidden issues. Older homes often have surprises: outdated wiring, plumbing problems, or structural issues that are not visible during a walkthrough. A professional inspection can help, but it cannot catch everything. You should have a contingency fund of at least 20 percent of your renovation budget on top of the expected costs. If you do not have that cash, a renovation loan may be the safer choice because the contingency is built into the financing.
Here is a simple framework for comparing the cash required for each path:
- Renovation loan: down payment (typically 3 to 5 percent for a 203(k) or 5 to 20 percent for a HomeStyle), closing costs, contingency reserve (10 to 20 percent of repair budget, financed), and proof of cash reserves for two to six months of mortgage payments.
- Conventional loan: down payment (as low as 3 percent for qualified buyers), closing costs, full renovation budget in cash or via a second loan, and a personal contingency fund of at least 20 percent of the renovation budget.
The renovation loan requires less upfront cash for the repairs because they are financed, but it requires more documentation and a longer timeline. The conventional loan requires more cash upfront but gives you more flexibility and a faster closing. Your choice should depend on how much liquid cash you have and how much risk you are willing to carry.
Comparing Total Project Cost Across Both Paths
To compare total project cost, you need to look beyond the interest rate. A renovation loan often has a slightly higher interest rate than a conventional loan because it is a more complex product. You will also pay for the appraisal, which includes the as-is and after-improved values, and you may pay a supplemental fee for the draw inspections. The lender may also charge an origination fee and closing costs similar to a conventional loan. The total cost of the renovation loan includes the interest on the renovation funds over the life of the loan, which can add thousands of dollars compared to paying cash for the repairs.
A conventional loan plus a home equity line of credit or a second mortgage has its own cost structure. The conventional loan may have a lower interest rate, but the HELOC will have a variable rate that can rise over time. You will pay closing costs on both loans, and you may pay an annual fee on the HELOC. If you use a credit card to fund renovations, the interest rate will be much higher, and the debt will be unsecured. The cheapest path depends on how long you plan to stay in the home and how quickly you can pay off the renovation debt.
Consider a hypothetical example. You are buying a $300,000 home that needs $50,000 in repairs. With a renovation loan, you might borrow $350,000 at 6.5 percent, with a contingency reserve of $10,000 included. Your monthly payment (principal and interest) would be about $2,212. With a conventional loan, you might borrow $300,000 at 6 percent, with a monthly payment of about $1,798, and then take out a $50,000 HELOC at 8 percent, with an interest-only payment of about $333. Your total monthly outlay would be about $2,131, which is lower than the renovation loan. However, the HELOC rate is variable, and you would need to pay down the principal eventually. Over 30 years, the renovation loan would cost more in interest, but it would be fully amortized, while the HELOC might have a balloon payment or a shorter repayment term.
The comparison is not just about monthly payments. You also need to factor in the time value of money, the cost of renting while the renovation is underway, and the potential for the home's value to increase. A renovation loan lets you buy a home that you might not otherwise be able to afford, and it lets you include the cost of repairs in the purchase price, which can be beneficial if the market is rising. A conventional loan gives you more control and potentially lower costs, but it requires more cash and more risk. If you are exploring refinancing options after you own the home, a resource like RefinancingCo offers educational tools and lender comparisons that can help you understand the process. You can also use a mortgage calculator to estimate payments and compare scenarios before you commit.
One more factor to consider is the appraisal. With a renovation loan, the appraisal is based on the after-improved value, which can help you avoid a low appraisal that kills the deal. With a conventional loan, the appraisal is based on the current condition, and if the appraiser notes needed repairs, the lender may require them to be completed before closing. That can delay the closing or force you to renegotiate the price. If the home is in poor condition, a renovation loan may be the only way to get financing, because conventional lenders are not willing to take on the risk of a property that does not meet minimum standards.
Which Path Fits Your Situation?
If you have limited cash and the home needs major repairs, a renovation mortgage is often the better choice. It allows you to finance the repairs over time, and the lender's contingency reserve protects you from some unexpected costs. You will need to work with a licensed contractor and follow the draw schedule, but you get a move-in ready home without draining your savings. If you have significant cash reserves, are handy, and want to renovate on your own timeline, a conventional loan plus a home equity line of credit may be more cost-effective. You will have more flexibility and potentially lower total interest costs, but you bear the risk of overruns and surprises.
Before you decide, get pre-approved for both options. A lender can tell you how much you qualify for and what the monthly payments would look like. Compare the total cost of each path, including interest, fees, and contingency reserves. And do not forget to factor in the intangible costs: the stress of managing a renovation, the time it takes to complete the work, and the disruption to your daily life. The best financing choice is the one that fits your budget and your tolerance for risk, not just the one with the lowest interest rate.
Whichever path you choose, start with a clear understanding of your credit and your cash position. If you are working to improve your credit before you buy, our guide on loan financing for a low credit score can help you identify steps to strengthen your application. And if you are ready to compare mortgage options, request a free quote from a network of lenders to see what you qualify for. The right financing can turn a fixer upper into the home of your dreams, but only if you go in with your eyes open and your budget in hand.