Reverse Mortgage Eligibility Requirements for Seniors 2026
Reverse mortgage eligibility requirements for seniors 2026 include age 62+, homeownership, and a financial assessment. Learn how to qualify and access tax-free cash.
By Sloane Parker
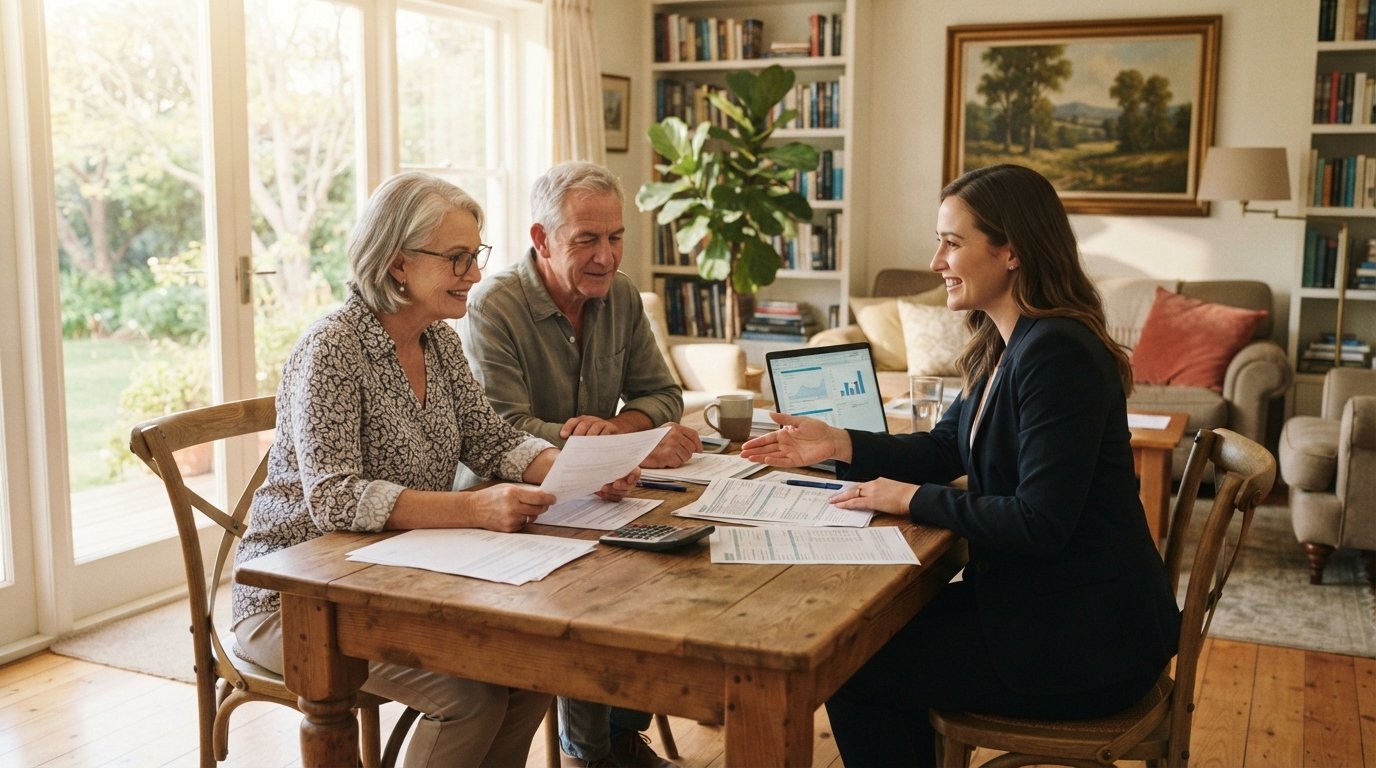
Turning 62 opens a new door in retirement planning: your home equity can become a source of tax-free cash without a required monthly mortgage payment. But before you picture a more comfortable budget, you need to know whether you actually qualify. The rules for reverse mortgages are specific, and they have been updated for 2026. Lenders look at your age, the type of home you own, how much equity you have, and your ability to keep up with property taxes and insurance. Miss any one of these, and the loan will not move forward. This guide walks you through every reverse mortgage eligibility requirement for seniors in 2026, step by step, so you can decide if this option fits your retirement plan.
Who Qualifies: The Core Reverse Mortgage Eligibility Requirements for Seniors 2026
At its heart, a reverse mortgage is a loan available to homeowners aged 62 and older that lets you convert part of your home equity into cash. You keep the title, you stay in the home, and you are not required to make monthly mortgage payments. Instead, the loan balance grows over time and is repaid when you move out, sell the home, or pass away. Because the loan is designed for older borrowers, the eligibility rules are different from those for a traditional forward mortgage.
For 2026, the basic eligibility checklist includes the following items. Most lenders apply these standards consistently across the Home Equity Conversion Mortgage (HECM) program, which is the most common type of reverse mortgage and is insured by the Federal Housing Administration (FHA).
- Age: All borrowers on the title must be at least 62 years old. If a younger spouse is on the deed, special protections may apply, but the younger spouse cannot be a borrower until they turn 62.
- Homeownership: You must own the home outright or have a low remaining mortgage balance that can be paid off at closing using proceeds from the reverse mortgage.
- Primary Residence: The home must be your principal residence, meaning you live there for more than half the year.
- Property Type: Eligible properties include single-family homes, FHA-approved condominiums, townhouses, and some manufactured homes. Investment properties and most second homes do not qualify.
- Financial Assessment: You must demonstrate the ability to pay property taxes, homeowners insurance, and other ongoing costs. Lenders will review your credit history, income, and assets to confirm you can meet these obligations.
- Counseling: Before closing, you must complete a counseling session with a HUD-approved counselor. This is a free or low-cost service designed to ensure you understand the loan's costs and consequences.
These requirements are not just bureaucratic hurdles; they protect both you and the lender. The financial assessment, in particular, was added after the 2008 housing crisis to reduce foreclosures among seniors who fell behind on property charges. In 2026, this assessment remains a critical step. If you have a history of missed tax payments or insurance lapses, you may need to set aside funds in a escrow account or show a plan to catch up. Lenders want to see that you can handle the ongoing costs of homeownership, even without a monthly mortgage payment.
Property and Occupancy Rules You Must Meet
Your home itself has to meet certain standards. The property must be in good condition and meet FHA minimum property requirements. If the home needs repairs, the lender may require them to be completed before or shortly after closing. In some cases, a portion of the loan proceeds can be set aside to pay for those repairs. This is common with older homes that may have roof issues, plumbing problems, or safety hazards.
Occupancy is equally important. You must live in the home as your primary residence. If you move out for more than 12 months for any reason, the loan becomes due. This includes moving to a nursing home or assisted living facility. However, if you are temporarily in a hospital or rehab center, the clock may be paused. You must also keep the home insured and pay property taxes on time. Failure to do so can trigger a default and eventually foreclosure.
For condos, the property must be in an FHA-approved project. If your condo is not approved, you may still qualify for a proprietary reverse mortgage (a private loan not backed by the FHA) that has different rules. Proprietary loans often have higher lending limits and more flexible property standards, but they may come with higher interest rates. In 2026, more lenders are offering proprietary options, which can be a good fit for higher-value homes.
Financial Assessment: Showing You Can Pay Taxes and Insurance
The financial assessment is where many applicants stumble. Lenders will pull your credit report, review your income sources (Social Security, pension, investments), and look at your assets. They want to see a pattern of responsible financial behavior. A history of late payments on property taxes or insurance is a red flag. So is a recent bankruptcy or foreclosure. That does not automatically disqualify you, but it may mean the lender requires a larger set-aside from your loan proceeds to cover future property charges.
If your income and assets are limited, the lender may require you to set aside a portion of the loan proceeds in an escrow account. This account is used to pay your property taxes and insurance on your behalf. This reduces the amount of cash you receive upfront but ensures you stay current on obligations. Alternatively, you may be able to show a documented plan to pay these costs from other sources. The key is to prove you can handle the ongoing expenses of homeownership.
For many seniors, the financial assessment feels intrusive. But it is a necessary part of the process. If you are unsure whether you meet the criteria, consider speaking with a HUD-approved counselor before applying. They can review your situation and help you understand your options. You can also use a mortgage calculator to estimate your potential loan proceeds, though it will not tell you if you qualify. For a deeper look at general loan eligibility requirements, including credit and income benchmarks, see our guide on Loan Eligibility Requirements.
How Much Can You Borrow in 2026? Key Factors and Limits
The amount you can borrow depends on several factors: your age, the appraised value of your home, current interest rates, and the lending limit. In 2026, the FHA HECM lending limit is $1,209,750, up slightly from 2025. That means if your home is worth more than that, only the first $1,209,750 is used to calculate your loan amount. For homes valued above the limit, a proprietary reverse mortgage may allow you to access more equity.
Your age is a major factor. The older you are, the more you can borrow because the loan is expected to last a shorter time. For example, a 62-year-old might qualify for about 40 percent of the appraised value, while an 80-year-old might qualify for 60 percent or more. The exact percentage also depends on interest rates. When rates are higher, lenders offer less. In 2026, with rates expected to remain moderate, most borrowers can expect to access between 40 and 60 percent of their home's value.
You can choose how to receive the money: a lump sum, monthly payments, a line of credit, or a combination. A line of credit is often the most flexible because it grows over time, giving you access to more funds later. If you want to compare current reverse mortgage rates and see how they affect your payout, RateChecker provides real-time rate comparisons and financial tools that can help you run the numbers before you commit.
Steps to Apply and Secure Your Reverse Mortgage in 2026
Applying for a reverse mortgage involves several steps, and it is important to know what to expect. The process typically takes 30 to 60 days, sometimes longer if repairs are needed. Here is a simple framework to follow.
- Get educated: Attend a HUD-approved counseling session. This is required for all HECM loans and will help you understand the pros and cons.
- Get quotes: Compare offers from multiple lenders. Rates and fees can vary significantly, so shopping around is essential. You can request free quotes through LoanFinancing.com to connect with top national lenders.
- Complete the application: Provide documentation for income, assets, and property information. The lender will order an appraisal and a title search.
- Underwriting and financial assessment: The lender reviews your finances and the property. If repairs are needed, you will need to complete them or set aside funds.
- Closing: Sign the final documents. You have a three-day right of rescission to cancel if you change your mind.
After closing, you can access your funds according to the payment plan you selected. Remember that you are still responsible for property taxes, insurance, and home maintenance. If you fail to meet these obligations, the loan can become due. It is also important to keep the lender informed if you change your address or plan to be away for an extended period.
Potential Pitfalls and How to Avoid Them
While reverse mortgages can be a lifeline for seniors, they are not without risks. One common mistake is not budgeting for property taxes and insurance. Even though you no longer make mortgage payments, these costs remain. If you fall behind, you could face foreclosure. Another pitfall is taking a lump sum and spending it too quickly. It is often smarter to take a line of credit or monthly payments to ensure the money lasts.
Another issue is the impact on your heirs. When you pass away, your heirs must repay the loan or sell the home. If the home is worth less than the loan balance, FHA insurance covers the difference for HECM loans, but your heirs will not receive any remaining equity. If the home is worth more, they keep the difference. It is important to discuss your plans with your family so there are no surprises.
Finally, be wary of scams. Some unscrupulous companies target seniors with high-pressure sales tactics. Only work with FHA-approved lenders and HUD-approved counselors. If an offer sounds too good to be true, it probably is. Take your time, ask questions, and never sign anything you do not fully understand.
Frequently Asked Questions About Reverse Mortgage Eligibility in 2026
Can I qualify if I have bad credit?
Yes, but it is harder. The financial assessment will look at your credit history, but a low score does not automatically disqualify you. You may need to set aside more funds to cover property charges. A counselor can help you understand your options.
What if my spouse is under 62?
If your spouse is under 62 and not on the loan, they can still live in the home after you pass away, but they may need to pay off the loan or sell the home. Some lenders offer protections for non-borrowing spouses, but you should discuss this with a counselor.
Can I get a reverse mortgage on a mobile home?
Yes, if the mobile home is classified as real property and meets FHA standards. It must be on a permanent foundation and you must own the land. Some manufactured homes qualify, but the rules are strict.
How much does a reverse mortgage cost?
Costs include an origination fee, mortgage insurance premium, third-party closing costs, and servicing fees. These can be financed into the loan, so you do not need cash upfront. However, they reduce the amount of equity you can access.
Understanding the reverse mortgage eligibility requirements for seniors in 2026 is the first step toward making a confident decision. If you meet the age, property, and financial criteria, a reverse mortgage could provide the cash flow you need to enjoy your retirement years. To explore your options and compare quotes from multiple lenders, visit LoanFinancing.com today. Our platform connects you with top national lenders and provides free, no-obligation quotes so you can see what you qualify for. Take the next step toward financial security in retirement.