
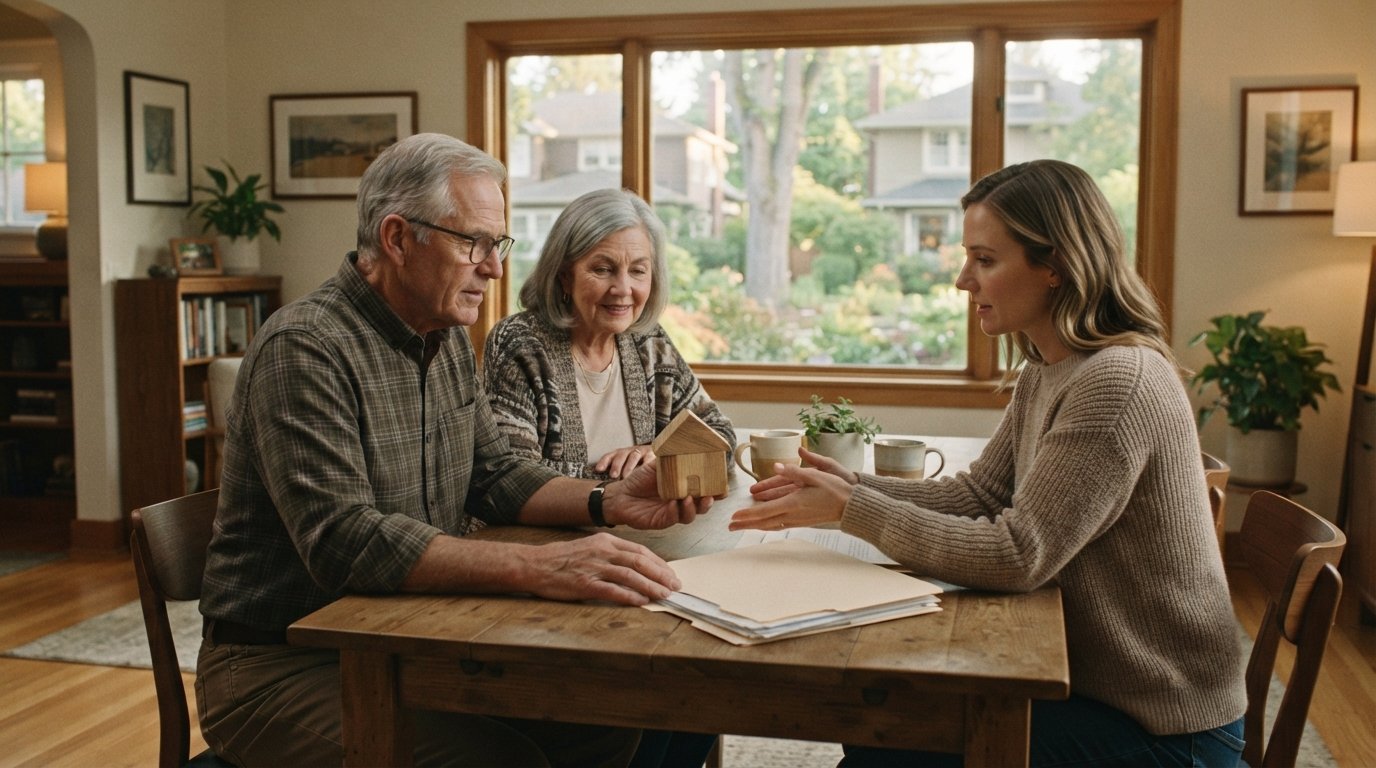
Reverse Mortgage Impact on Estate Planning and Heirs
A reverse mortgage can reduce inheritance and complicate estate settlement. Learn how to protect your heirs with proactive planning and clear communication.
By Wesley Miller
Imagine unlocking the equity in your home to fund retirement, only to discover that the loan could reshape the inheritance you leave behind. That is the tightrope many homeowners over 62 walk when they consider a reverse mortgage. Unlike a traditional mortgage, a reverse mortgage does not require monthly payments, but the loan balance grows over time. When the last borrower moves out or passes away, the loan becomes due, and the estate must settle the debt. The choices made today can determine whether heirs inherit a valuable asset or a financial headache. Understanding the reverse mortgage impact on estate planning and heirs is not just about numbers, it is about preserving family wealth and avoiding costly surprises. This article breaks down how these loans interact with your estate, what your heirs need to know, and how to plan ahead so your legacy stays intact.
How a Reverse Mortgage Works and Why It Matters for Your Estate
A reverse mortgage, most commonly a Home Equity Conversion Mortgage (HECM) insured by the FHA, allows homeowners aged 62 and older to convert a portion of their home equity into cash. The loan does not require monthly mortgage payments, but interest and fees accrue over time, increasing the total debt. The loan becomes due when the last borrower dies, sells the home, or permanently moves out. At that point, the estate or heirs must repay the loan, typically by selling the home or refinancing it. If the home is sold, the proceeds go first to the lender, and any remaining equity goes to the heirs. If the loan balance exceeds the home value, the FHA insurance covers the shortfall, and heirs are not personally liable. However, if heirs want to keep the home, they must pay off the loan, often by obtaining a new traditional mortgage. This structure means the reverse mortgage directly reduces the equity that would otherwise pass to heirs, making it a critical estate planning consideration.
The timing and size of the loan also matter. A large lump sum taken early can balloon the loan balance, leaving little equity for heirs. A line of credit or monthly payments may preserve more equity if the home appreciates. Heirs should also understand that a reverse mortgage is a non-recourse loan, meaning the lender cannot pursue them for more than the home is worth. Still, the emotional and financial burden of selling a family home can be significant. In our guide on are reverse mortgage payouts taxable in 2026, we explain how the proceeds are generally treated as loan advances, not income, which can affect estate accounting. That tax treatment is just one layer of the estate puzzle.
Key Impacts on Heirs and Inheritance
When a reverse mortgage borrower dies, the estate enters a settlement period. The lender typically allows up to six months (sometimes extendable) for the heirs to decide whether to repay the loan, sell the home, or deed the property back to the lender. During this time, the estate is responsible for property taxes, insurance, and maintenance. If heirs fail to act, the lender may foreclose. The most immediate impact is that the home is encumbered by a growing debt. Heirs cannot simply inherit the home free and clear; they must resolve the reverse mortgage first. If the home is worth more than the loan balance, the difference goes to the estate. If it is worth less, the FHA insurance absorbs the loss, but the heirs receive nothing from the home. This can create conflict among siblings who may have different desires for the property.
Another critical impact is the potential reduction in overall inheritance. If the reverse mortgage consumes a large share of home equity, other assets may need to be liquidated to pay debts or equalize inheritances. For example, if one child wants to keep the home and others want cash, the estate may need to sell other assets or take out a loan. Heirs should also be aware that a reverse mortgage can affect eligibility for needs-based benefits like Medicaid if funds are not spent down properly, though this is more a concern for the borrower than the heirs. Finally, the loan balance can be deducted from the estate's value for estate tax purposes, but most estates fall below the federal exemption threshold, so this is rarely a major factor.
To navigate these impacts, heirs and borrowers should consider the following steps well before the loan becomes due:
- Review the loan terms and current balance: Understand how much is owed and how the balance grows over time.
- Estimate the home's future value: Use conservative appreciation rates to see if equity will remain.
- Discuss intentions with heirs: Find out if anyone wants to keep the home and can afford to refinance.
- Explore alternatives: Compare a reverse mortgage with downsizing, a HELOC, or selling and renting.
- Consult an estate attorney: Integrate the reverse mortgage into a will or trust to avoid probate delays.
These steps can reduce uncertainty and help families make informed decisions. For instance, if heirs plan to sell, they should know that the sale process requires lender approval and may take time. If they plan to keep the home, they should get pre-approved for a new mortgage early. Without a plan, the default option is often a rushed sale that may not maximize value.
Estate Planning Strategies to Protect Your Legacy
Borrowers can take several proactive steps to minimize the negative impact of a reverse mortgage on their estate. First, consider taking a smaller lump sum or choosing a line of credit that you draw on only as needed. This slows the growth of the loan balance and preserves more equity. Second, set aside other assets, such as life insurance or investments, specifically to repay the reverse mortgage or to equalize inheritances. A life insurance policy with a death benefit that matches the expected loan balance can provide heirs with the cash to pay off the loan and keep the home. Third, use a trust or other estate planning tool to clarify ownership and streamline the settlement process. Placing the home in a living trust can avoid probate, but the lender must approve the trust as a borrower. Fourth, communicate openly with heirs about your plans and the likely outcome. Transparency reduces conflict and allows heirs to prepare financially.
Another strategy is to consider a reverse mortgage as part of a broader retirement income plan. If you use the loan to delay Social Security or to fund a Roth conversion, you may increase your overall wealth, which can offset the equity consumed by the loan. However, this requires careful modeling. For those exploring reverse mortgage options, comparing rates and terms is essential. You can use a RateChecker tool to see current reverse mortgage rates and understand how different scenarios affect your loan balance over time. RateChecker provides real-time mortgage rate comparisons and educational resources, which can help you make a more informed choice. Always remember that LoanFinancing.com is not a lender and does not provide personalized financial advice; consult a qualified advisor before making decisions.
Tax and Legal Considerations for Heirs
When heirs inherit a home with a reverse mortgage, they may face tax implications. The loan proceeds are generally not taxable to the borrower, but heirs who sell the home may owe capital gains tax on the difference between the sale price and the adjusted basis. The basis is typically the home's value at the time of the borrower's death, which can reduce the tax burden. However, if the home is sold for less than the outstanding loan balance, there is no capital gain, but also no inheritance. Heirs should consult a tax professional to understand their specific situation. Additionally, if the estate is insolvent, the reverse mortgage may consume all assets, leaving nothing for other beneficiaries. In some states, heirs may have personal liability for property taxes or homeowners association fees that accrue during the settlement period. It is crucial to review the loan documents and state law to avoid surprises.
Legal considerations also include the rights of non-borrowing spouses. Under HECM rules, a non-borrowing spouse may be able to remain in the home after the borrowing spouse dies, provided certain conditions are met. This protects the surviving spouse but can delay the settlement for heirs. Heirs should also be aware that if the borrower had a reverse mortgage and also received Medicaid benefits, the state may seek recovery from the estate, including the home. Proper planning can help mitigate these risks. For example, setting up a Medicaid asset protection trust or using a life estate can shield some assets. Again, professional guidance is essential.
Comparing Reverse Mortgages to Other Equity-Release Options
Before committing to a reverse mortgage, homeowners should compare it with alternatives that may have less impact on their estate. A home equity loan or HELOC requires monthly payments but does not consume equity as quickly if you pay it down. A cash-out refinance replaces your existing mortgage with a larger one, also requiring payments. Selling the home and downsizing frees up equity but means moving. Each option has trade-offs. A reverse mortgage offers no monthly payments and allows you to stay in the home, but it reduces the inheritance. A HELOC may be better if you can afford payments and want to preserve equity. A cash-out refinance might offer lower interest rates but requires income qualification. For those who want to age in place and have limited income, a reverse mortgage can be a lifeline, but it should be a last resort after exploring other avenues.
Heirs should also be part of the conversation. If they are expected to inherit the home, they may prefer that you choose an option that preserves more equity, even if it means you have less cash flow. Conversely, if they have no interest in the home, a reverse mortgage may be a good way to unlock cash without worrying about the inheritance. The key is to align your choice with your estate goals. LoanFinancing.com offers a mortgage calculator and educational resources to help you compare scenarios, but it does not provide personalized advice. Use these tools to facilitate discussions with your family and advisors.
Steps to Take Now to Mitigate the Impact
If you already have a reverse mortgage or are considering one, taking action now can protect your heirs. Start by reviewing your loan balance and projected growth. Then, assess your other assets and how they might be used to settle the loan. Consider setting up a dedicated savings or investment account for that purpose. Next, update your estate plan to reflect the reverse mortgage. This may include creating a trust, adding a transfer-on-death deed, or specifying which assets should be sold to repay the loan. Communicate your plan to your heirs and provide them with contact information for your lender and attorney. Finally, monitor your home's value and the loan balance annually. If equity is shrinking faster than expected, you may need to adjust your plan, perhaps by making partial repayments or refinancing to a traditional mortgage if possible. Remember, a reverse mortgage is not set in stone; you can change course if your circumstances change.
For those who are unsure, seeking advice from a HUD-approved counselor is a requirement for HECM loans and can provide valuable insights. Counselors can explain the long-term costs and alternatives. They can also help you understand the reverse mortgage impact on estate planning and heirs in plain language. While LoanFinancing.com does not provide counseling, it connects you with lenders and offers free quotes, which can be a starting point for comparing options. Always read the fine print and ask questions about fees, interest rates, and repayment terms. The more you know, the better you can protect your legacy.
Planning for a reverse mortgage is not just about today's cash flow; it is about tomorrow's inheritance. By understanding the mechanics, communicating with heirs, and integrating the loan into your estate plan, you can minimize the negative impact and ensure your family is prepared. Whether you decide to move forward or explore alternatives, informed decisions are the best way to safeguard your financial legacy.