
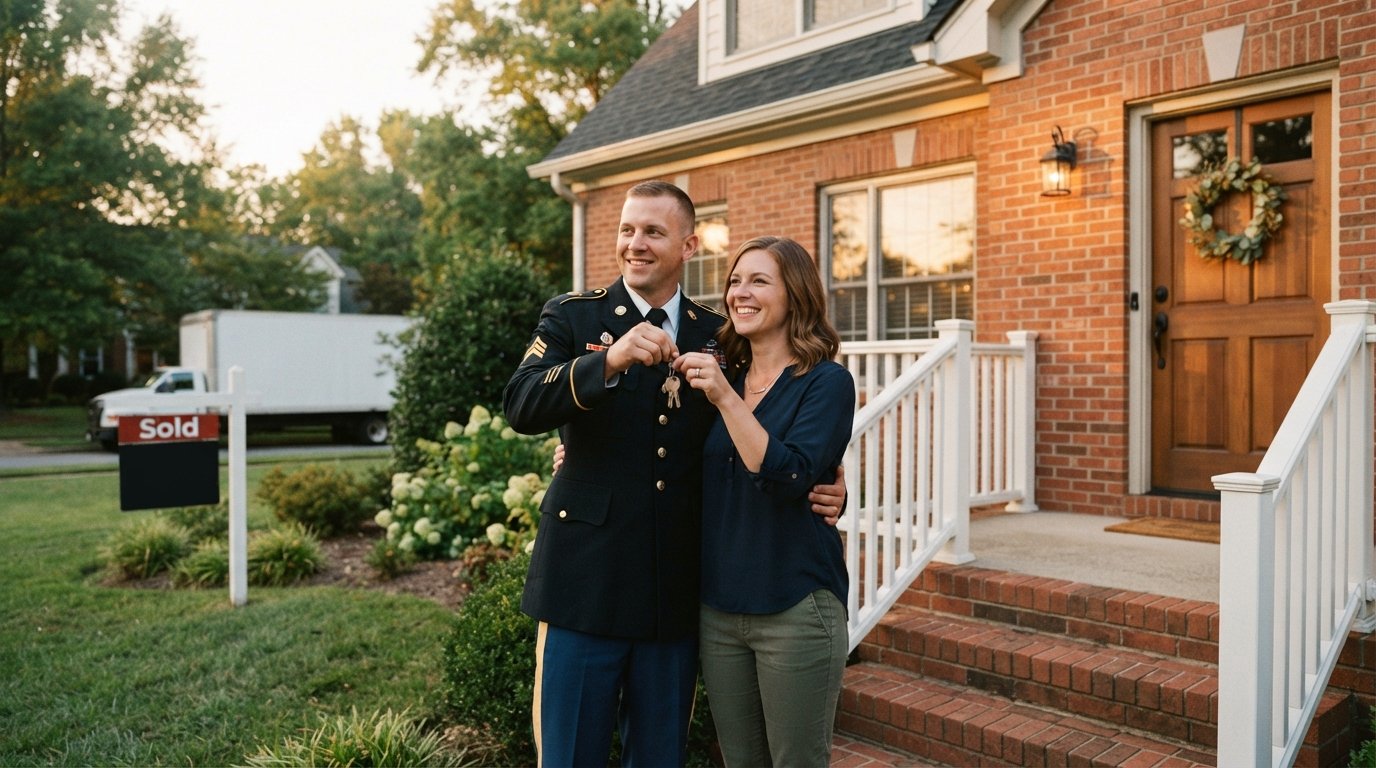
VA Loan Benefits for Military Homebuyers in 2026
The VA loan benefits for military homebuyers include zero down payment and no PMI, making homeownership more affordable for veterans and service members.
By Priya Ingram
For millions of active-duty service members, veterans, and surviving spouses, the path to homeownership is paved with a distinct financial advantage that most civilian buyers simply cannot access. The VA loan benefits for military homebuyers are not just minor perks; they represent one of the most powerful wealth-building tools available in the U.S. mortgage market. With the ability to purchase a home with zero down payment and competitive interest rates, eligible borrowers can secure their financial future without the burden of a massive upfront cash requirement. However, understanding the full scope of these benefits, from the funding fee structure to the nuances of the VA appraisal process, is essential for making informed decisions. Whether you are a first-time buyer or looking to refinance, leveraging these entitlements correctly can save you tens of thousands of dollars over the life of your loan.
Zero Down Payment and 100 Percent Financing
The most celebrated advantage of a VA loan is the ability to finance 100 percent of the home's purchase price. For conventional loans, buyers often need to save 5 to 20 percent of the home's value for a down payment. On a $400,000 home, that means coming up with $20,000 to $80,000 in cash before even paying closing costs. For many military families who move frequently or are early in their careers, saving that amount is a significant hurdle. The VA loan eliminates this barrier entirely, allowing you to preserve your savings for emergencies, investments, or home improvements.
This zero-down feature is not just about convenience; it is about accessibility. It allows service members to enter the housing market years earlier than they might otherwise be able to. Instead of renting and watching home prices rise, you can start building equity immediately. It is important to note that while the down payment is zero, you will still need to cover closing costs, though the seller can often be negotiated to pay these as part of the purchase agreement. This flexibility makes the VA loan benefits for military homebuyers a cornerstone of financial stability for the armed forces community.
Competitive Interest Rates and Lower Monthly Payments
VA loans typically offer lower interest rates than conventional loans. Because the loan is backed by the Department of Veterans Affairs, lenders assume less risk, and they pass those savings on to the borrower in the form of lower rates. Even a small difference in interest rate, such as 0.5 percent, can translate to tens of thousands of dollars saved over a 30-year mortgage. Lower rates also mean lower monthly payments, which improves your debt-to-income ratio and makes it easier to qualify for the loan in the first place.
To ensure you are getting the best possible rate, it is wise to compare offers from multiple lenders. Using a platform like RateChecker can help you see real-time rate comparisons and find the most competitive terms for your VA loan. Because the VA does not set the interest rate, shopping around is the best way to maximize this benefit. Lenders vary in their pricing, and a little research can result in significant savings over the life of the loan.
No Private Mortgage Insurance (PMI) Requirement
One of the most significant recurring costs for conventional borrowers is private mortgage insurance (PMI). This is typically required when a buyer puts down less than 20 percent of the home's purchase price. PMI protects the lender in case of default, but it costs the borrower money every month, often ranging from 0.3 percent to 1.5 percent of the loan amount annually. On a $300,000 loan, that could be an extra $150 to $375 per month, money that does not go toward paying down the principal or building equity.
VA loans do not require PMI, regardless of the down payment amount. This is a massive financial benefit that directly reduces your monthly housing costs. Over the life of a loan, the savings from avoiding PMI can easily amount to $50,000 or more. This allows military homebuyers to afford more house for the same monthly budget or to save that money for other financial goals. The absence of PMI is a key reason why VA loans are often the most affordable option for eligible buyers.
Limits on Closing Costs and Negotiable Fees
The VA imposes strict limits on the closing costs that lenders can charge veterans. This protection ensures that you are not taken advantage of during the loan process. The VA prohibits lenders from charging certain fees, such as attorney fees, and limits others. Furthermore, the VA allows sellers to pay up to 4 percent of the loan amount in concessions to cover closing costs, prepaid taxes, and insurance. This is a powerful negotiation tool that can significantly reduce the amount of cash you need to bring to the closing table.
Understanding these limits helps you negotiate a better deal. For example, if a seller is motivated, they may agree to cover all of your closing costs, allowing you to purchase a home with virtually no out-of-pocket expenses. The VA also requires that the lender provide a Loan Estimate and a Closing Disclosure, which outline all costs, ensuring transparency throughout the transaction.
Reusable and Flexible Entitlement
Many veterans worry that they can only use their VA loan once. This is a common myth. The VA loan entitlement is reusable, and you can use it multiple times over your lifetime. If you pay off your VA loan and sell the home, your full entitlement is restored, allowing you to use it again for a new purchase. Even if you still have an existing VA loan, you may be able to use your remaining entitlement to buy another home without selling the first one, subject to certain limits.
This flexibility is invaluable for military families who are frequently relocated. It means you can buy a home at each new duty station, build equity, and potentially turn your previous home into a rental property. The ability to reuse the VA loan benefit is a major advantage that supports long-term wealth accumulation. Additionally, if you are looking to refinance an existing VA loan, options like the Interest Rate Reduction Refinance Loan (IRRRL) make the process streamlined and cost-effective.
Additional Benefits: Surviving Spouses and Funding Fee Exemptions
Beyond the core financial advantages, there are specific provisions that extend the VA loan benefits for military homebuyers to surviving spouses and disabled veterans. Unmarried surviving spouses of veterans who died in service or from a service-connected disability may be eligible for the VA loan benefit. This provides a crucial safety net for families during difficult times.
Furthermore, veterans receiving disability compensation are often exempt from the VA funding fee, a mandatory fee that varies based on down payment and first-time use. This fee can range from 1.25 percent to 3.3 percent of the loan amount. For those who are exempt, this saves thousands of dollars at closing. Even for those who must pay the fee, it is typically lower than the PMI costs associated with conventional loans.
Steps to Maximize Your VA Loan Benefits
To fully leverage the VA loan benefits for military homebuyers, it is helpful to follow a structured approach. This ensures you are prepared and can navigate the process smoothly. Here are the key steps to consider:
- Obtain a Certificate of Eligibility (COE): This document proves to your lender that you qualify for the VA loan program. You can apply online through the VA website or through your lender.
- Gather Your Documents: Be ready with your DD-214, proof of income, tax returns, and bank statements. Having these ready speeds up the pre-approval process.
- Get Pre-Approved: A pre-approval letter shows sellers you are a serious buyer. It also helps you understand how much house you can afford based on your budget and the lender's criteria.
- Shop for a Home and Negotiate: Work with a real estate agent who understands VA loans. Negotiate seller concessions to cover closing costs and ensure the home meets VA property standards.
- Complete the VA Appraisal: The VA requires a specific appraisal to ensure the home is safe, sound, and sanitary. This protects you from buying a property with major defects.
Following these steps can help you navigate the process efficiently. It is also beneficial to consult educational resources to understand the nuances of the program. For instance, understanding the benefits of refinancing loan financing can help you decide if a future refinance makes sense to lower your rate or access equity. Being informed is your best strategy for a successful home purchase.
The VA loan program is a well-deserved benefit for those who have served the country. By understanding the zero down payment option, the absence of PMI, and the competitive interest rates, you can make the most of your entitlement. Take the time to get pre-approved and compare lenders to ensure you are getting the best possible deal. With careful planning, the VA loan benefits for military homebuyers can turn the dream of homeownership into a reality, providing a stable foundation for you and your family for years to come.