What Documents Does a Reverse Mortgage Require From Seniors?
Gather proof of age, home records, and financial statements to speed up your reverse mortgage application and avoid funding delays.
By Caleb Nguyen
If you are a homeowner aged 62 or older and considering a reverse mortgage, you have probably heard that the application process involves a fair amount of paperwork. That is true, but the paperwork is not busywork: each document serves a specific purpose in helping lenders verify your eligibility, protect your home, and ensure you can meet the loan obligations over time. Knowing exactly what will be requested before you apply can save you weeks of back-and-forth and reduce the stress of an already complex financial decision. This guide walks through the core documents a reverse mortgage requires from seniors, from proof of age and identity to trust paperwork and repair estimates, so you can arrive at the process organized and prepared.
It helps to understand why so many documents are needed. A reverse mortgage is a loan secured by your home, but unlike a traditional mortgage, it does not require monthly payments. Instead, the loan balance grows over time and is repaid when the last borrower leaves the home. Because the lender will not collect monthly payments, they need strong evidence that you can keep up with property taxes, homeowners insurance, and basic maintenance, which are the borrower's ongoing responsibilities. This is why the financial assessment and the documentation behind it are so central to the process. The paperwork is essentially a risk assessment and a protection plan rolled into one.
Proof of Age, Identity, and Social Security Numbers
The most fundamental requirement for a reverse mortgage is that all borrowers must be at least 62 years old. Lenders verify this with government-issued identification. For each borrower, expect to provide a valid driver's license or state-issued ID card, a passport, or another form of photo identification. The name on the ID must match the name on the home's title and on the Social Security card. If you have recently changed your name, you may need to provide a marriage certificate or court order to connect the names across documents.
Social Security numbers are required for all borrowers. Lenders use them to verify identity, check credit history, and confirm eligibility. You will typically provide a Social Security card or a document from the Social Security Administration that shows your number. Some lenders accept a W-2 or tax return that displays the number, but a Social Security card is the most straightforward option. If you do not have your card, you can request a replacement from the Social Security Administration before you apply.
In addition to age and identity, lenders may ask for proof of citizenship or legal residency. A U.S. passport, birth certificate, or permanent resident card can satisfy this requirement. This step is part of standard anti-money-laundering and borrower verification rules, and it applies to all borrowers on the loan. Gathering these documents early is simple, but it prevents delays later. Keep photocopies or scans in a secure folder, and never send sensitive documents through unsecured email without confirming the lender's preferred method.
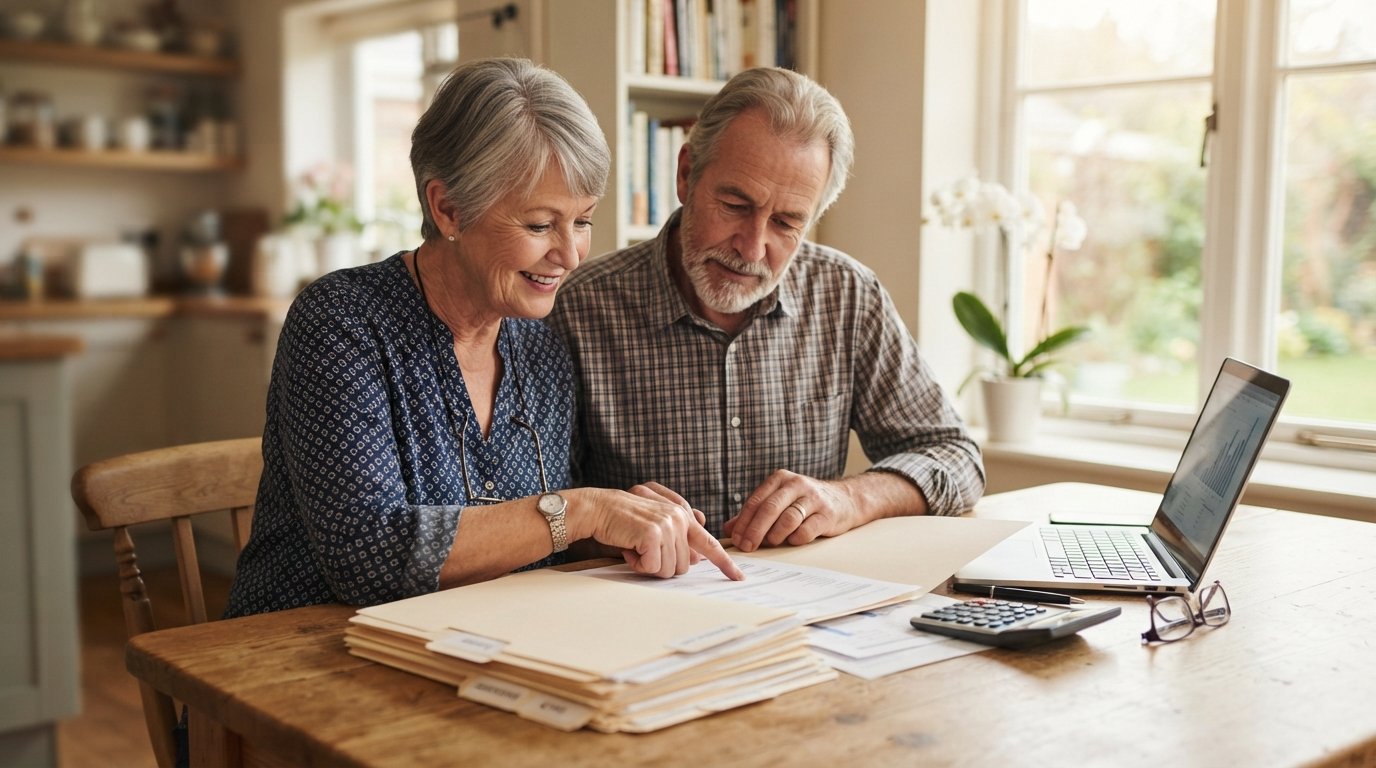
One practical tip: create a single folder, physical or digital, labeled "reverse mortgage documents" and place each item in it as you collect it. This habit makes it easy to spot missing items and to share information with a counselor or loan officer when requested. It also helps if you are applying with a spouse or co-borrower, since you can track whose documents are complete and whose are not.
Home Documentation: Deed, Insurance, and Tax Records
Because the home is the collateral for the loan, lenders need a clear picture of its ownership and condition. The first item is proof of ownership, typically a copy of the deed or title. If you do not have a copy, your county recorder's office can provide one, often for a small fee. The deed must show that all borrowers are on the title, and it must be free of certain encumbrances that could complicate the loan. If there is an existing mortgage, the lender will need a mortgage statement showing the current balance and payment history. Most reverse mortgage proceeds are first used to pay off any existing mortgage, so this statement is essential to the payoff calculation.
Homeowners insurance is another core requirement. Lenders require a current insurance policy that covers the home for its replacement cost. You will need to provide the declarations page, which shows the policy number, coverage amounts, and the property address. If your policy is set to renew soon, the lender may ask for updated proof once the renewal takes effect. Flood insurance may also be required if the home is in a designated flood zone; the lender will check this during the appraisal and will request a flood policy if needed.
Property tax records are used to confirm that taxes are current and to estimate future obligations. You can usually provide a recent property tax bill or a statement from the county assessor. Lenders also check for any tax liens or delinquencies, because unpaid taxes can jeopardize the lender's position. If you pay your taxes through an escrow account, a recent mortgage statement may show the tax payment history. If you pay directly, keep the receipts or canceled checks for the most recent year.
Beyond these basics, lenders may request documentation for homeowners association dues if you live in a condominium or planned community. A recent HOA statement or coupon book shows the monthly or annual obligation, which is factored into the financial assessment. If there are special assessments pending, the lender may ask for details. These records help the lender confirm that the home's carrying costs are manageable and that no unexpected liens are attached to the property. For a broader look at how reverse mortgage proceeds are treated at tax time, see our guide on whether reverse mortgage payouts are taxable in 2026.
Income and Asset Statements for the Financial Assessment
Since 2015, reverse mortgage lenders have been required to conduct a financial assessment. This is not a credit score test in the traditional sense; it is a review of your income, expenses, and assets to determine whether you can afford to pay property taxes, homeowners insurance, and basic maintenance over the life of the loan. If the assessment shows a shortfall, the lender may require a set-aside of funds from the loan proceeds to cover those costs, or may deny the application. The documents you provide here are central to that decision.
For income, expect to provide recent statements for Social Security benefits, pensions, annuities, and any employment income if you are still working. Bank statements for checking and savings accounts, typically the last two months, are also required. If you have investment accounts, brokerage statements or retirement account statements may be requested. The goal is to show a stable and verifiable income stream that covers your ongoing housing costs. Lenders may also ask for a written explanation if there are large or unusual deposits in your bank statements.
Asset documentation is equally important. This includes statements for savings accounts, certificates of deposit, retirement accounts, and any other liquid assets. If you own other real estate, you may need to provide mortgage statements or proof of equity for those properties. Lenders want to see that you have reserves to handle unexpected expenses. A useful way to think about it is that the financial assessment is asking, "If something goes wrong, can this borrower handle it without defaulting on the loan's ongoing obligations?" Your documents answer that question.
Here is a quick checklist of the income and asset documents most seniors are asked to provide:
- Social Security award letters or benefit statements
- Pension and annuity statements
- Recent bank statements for all checking and savings accounts
- Retirement account statements (IRA, 401(k), or similar)
- Tax returns for the most recent one or two years, if requested
- Documentation of any other income, such as rental income or part-time work
If you have a spouse who is under 62 and will continue living in the home, the lender will need documentation for that spouse as well, even if they are not a borrower. This is because the non-borrowing spouse's finances can affect the assessment and the loan's terms. Be prepared to provide identification, income, and asset information for a non-borrowing spouse if applicable. Some lenders may also require a signed statement acknowledging the non-borrowing spouse's status and the plan for the home after the borrower's death or departure.
Repair or Appraisal Paperwork That May Be Requested
Every reverse mortgage requires an appraisal, and sometimes the appraiser identifies repairs that must be completed before the loan can close. These are typically health and safety issues, such as a leaking roof, defective electrical wiring, or missing handrails. If repairs are required, the lender will ask for documentation showing that the work has been completed or that funds have been set aside to complete it. This might include contractor estimates, permits, or a final inspection report. The appraisal itself is ordered by the lender, but you may need to provide access and any relevant records, such as a prior inspection report or a list of recent renovations.
If you have made significant home improvements, gather receipts and permits. These documents can support the appraised value and show that the home has been maintained. In some cases, the lender may request a copy of a home inspection report if one was recently completed. If the home is in a flood zone, an elevation certificate may be required to determine flood insurance rates. These documents are not always mandatory, but having them ready can speed up the process and prevent surprises.
It is also wise to keep a record of any major repairs you have already completed, such as a new roof, HVAC system, or water heater. While not always required, this information can be helpful during the appraisal and may reduce the likelihood of a repair condition being added to your loan. The key is to be proactive: if you know your home has an issue that an appraiser might flag, address it before the appraisal or discuss it with your loan officer so there are no last-minute delays.
What to Do If Documents Are in a Trust or the Home Is Co-Owned
Many seniors hold their homes in a living trust to avoid probate and manage their estate. If your home is in a trust, the reverse mortgage process requires additional paperwork. You will need to provide the complete trust document, including all amendments and schedules, so the lender can review the trust's terms. The lender will check that the trust is valid, that the borrowers are the trustees or beneficiaries with the authority to encumber the property, and that the trust does not contain provisions that conflict with the loan terms. In some cases, the trust may need to be amended, or the home may need to be deeded out of the trust, before the loan can close. This is a situation where consulting an attorney who specializes in estate planning and real estate can be invaluable.
Co-ownership adds another layer. If the home is owned jointly by multiple people, all owners must be on the same page. For a reverse mortgage, all borrowers must be on the title, and all owners who are not borrowers may need to sign documents acknowledging the loan and its effect on their interest. If a co-owner is not a borrower and does not live in the home, the lender will need to review the ownership structure carefully. In some cases, a co-owner who is not a borrower may need to be removed from the title, which can have tax and legal consequences. Again, professional advice is recommended before making changes to the deed.
For co-owned homes where the co-owner is a spouse, the rules are more straightforward: the spouse can be a non-borrowing spouse, and the loan can proceed with proper documentation of the spouse's status. But if the co-owner is a sibling, adult child, or friend, the lender will want to see a clear plan for what happens if the borrower moves out or passes away. The documentation here might include a written agreement among co-owners, or a deed that reflects the intended ownership shares. The lender's goal is to ensure that the reverse mortgage does not create a legal dispute later.
When you are navigating these complex ownership and trust issues, it helps to work with a lender who is experienced in reverse mortgages and can guide you through the paperwork. LoanFinancing.com connects homeowners with a network of lenders who specialize in these products, and the site offers educational resources to help you compare options. You can also use the mortgage calculator to estimate proceeds and understand how the loan might fit your financial plan. For general mortgage information and tools, RefinancingCo is a useful resource that covers refinancing and reverse mortgage basics in plain language.
As you gather your documents, keep in mind that the list above is a starting point, not an exhaustive list. Every lender has its own requirements, and your situation may call for additional paperwork. The best approach is to ask your loan officer for a written checklist at the start and to review it with a HUD-approved reverse mortgage counselor, who can help you understand the financial assessment and the ongoing obligations of the loan. Counseling is required for most reverse mortgages, and it is a good opportunity to ask questions about the documents and the process.
Finally, organize your documents by category: identity, income, assets, home, and trust or co-ownership. Keep originals in a safe place and provide copies to the lender. If you are applying with a spouse or co-borrower, make a separate folder for each person. This simple system reduces stress and ensures nothing is overlooked. With the right paperwork in hand, you can move through the reverse mortgage process with confidence and focus on what matters most: using your home equity to support your retirement goals.