
How to Prepare Financially for a Reverse Mortgage Before 62
Preparing financially for a reverse mortgage before age 62 can increase your loan proceeds and reduce stress. Start with these key steps.
By Yara Adler
Most reverse mortgage guides start at age 62, but the smartest borrowers start years earlier. Preparing financially for a reverse mortgage before you hit the eligibility age can mean the difference between a smooth approval and a stressful scramble. Whether you are 55 and planning ahead or 61 and reviewing your options, the groundwork you lay now directly affects how much you can borrow, what it costs, and how well the loan serves your retirement. This article walks through the practical steps to get your finances, property, and expectations in order well before you apply.
Understand the Eligibility Rules Before You Plan
Before you can prepare, you need to know exactly what lenders and the federal government require. For a Home Equity Conversion Mortgage (HECM), the most common reverse mortgage, the youngest borrower on the loan must be at least 62 years old. The home must be your primary residence, and you must own it outright or carry a mortgage balance that can be paid off with the loan proceeds. The property must also meet minimum health and safety standards set by the U.S. Department of Housing and Urban Development (HUD).
Those requirements may sound straightforward, but the financial obligations attached to them are where preparation matters. You will still be responsible for property taxes, homeowners insurance, and home maintenance. Lenders assess whether you can afford those costs, and they can require set-asides from the loan proceeds to cover them. If you have let taxes or insurance lapse, or if your roof is failing, you will face hurdles. Understanding these rules early gives you time to fix problems while they are still small. For a broader look at alternatives if a reverse mortgage does not fit, see our guide on reverse mortgage alternatives for senior homeowners.
Credit history and other debts also come into play. While reverse mortgage lenders do not use a strict credit score cutoff like a forward mortgage, they do perform a financial assessment. They look at your credit history, your income, and your monthly obligations to determine whether you can keep up with taxes and insurance. A history of missed payments or excessive debt can lead to a requirement for a larger set-aside, which reduces the money available to you. Starting early lets you address these issues strategically.
Assess Your Property Condition and Fix Issues Early
Your home is the collateral for a reverse mortgage, so its condition matters. Lenders will order an appraisal, and the appraiser will note any deficiencies that affect safety, soundness, or structural integrity. Common problems include peeling paint, leaky roofs, broken steps, missing handrails, and outdated electrical or plumbing systems. These issues must be repaired before the loan can close, often at your expense.
If you are years away from applying, use that time to tackle deferred maintenance. Create a home maintenance checklist and budget for repairs. A pre-listing-style inspection, even if you are not selling, can reveal problems you might otherwise overlook. Addressing a failing roof or a wet basement now is far less stressful than scrambling to fix it during underwriting. It also protects your home's value, which directly influences how much you can borrow.
Keep in mind that some repairs may be required by the appraiser even if they seem minor. Peeling paint, for example, is a common flag because it can indicate moisture problems. If you live in an area with harsh weather, plan for seasonal upkeep. Setting aside a small monthly amount for maintenance creates a buffer and demonstrates financial responsibility, which can help during the lender's assessment.
Build a Plan for Ongoing Costs You Must Still Pay
A reverse mortgage eliminates monthly mortgage payments, but it does not eliminate the cost of owning a home. You remain responsible for property taxes, homeowners insurance, HOA dues, utilities, and general upkeep. Lenders will verify that you can afford these obligations. If your income is limited, they may require a set-aside from the loan proceeds to cover them for a period of time. That set-aside reduces the amount you can access, so planning ahead can preserve more of your equity.
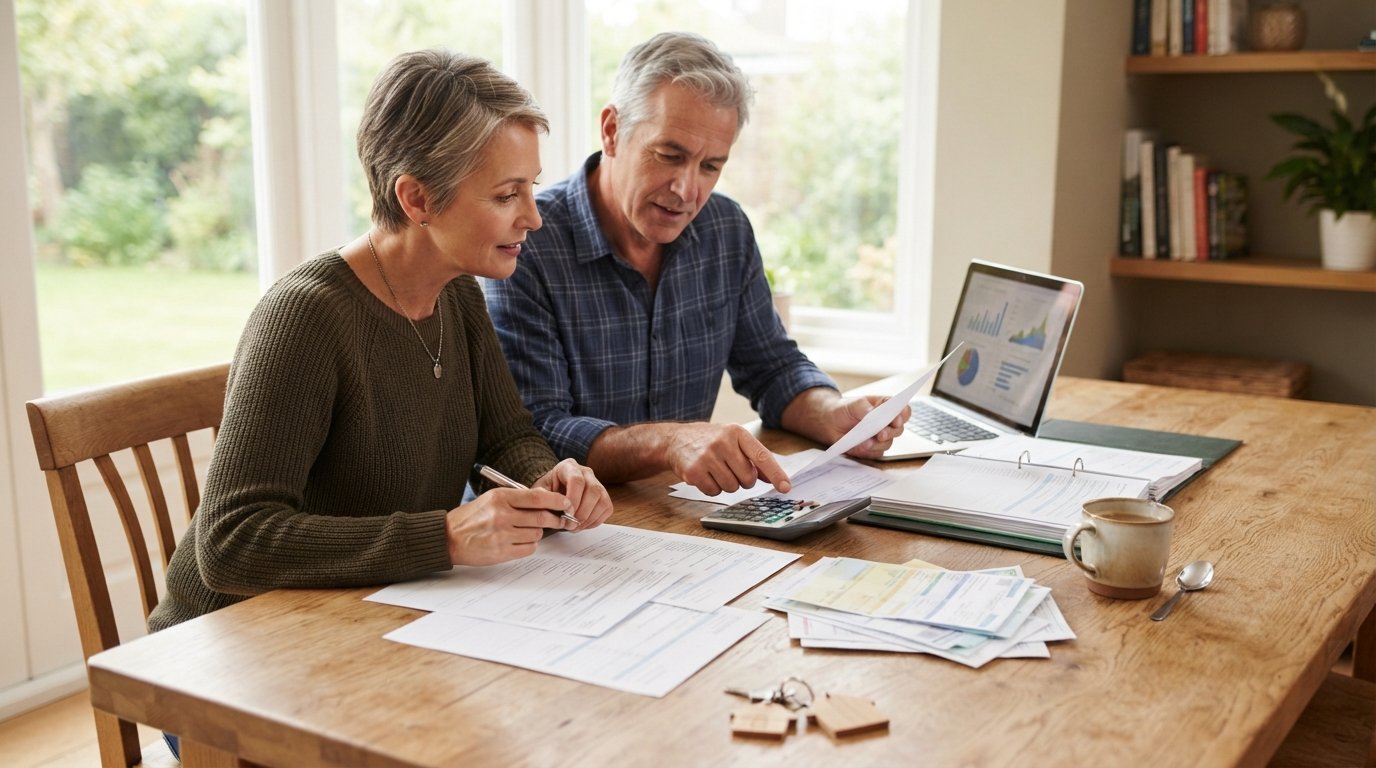
Start by calculating your annual carrying costs. Add up property taxes, insurance premiums, HOA fees, and a realistic maintenance budget. Compare that total to your retirement income sources, such as Social Security, pensions, and investment withdrawals. If there is a gap, consider ways to close it before you apply. You might downsize other expenses, increase income through part-time work, or build a dedicated reserve fund for housing costs.
Here are key steps to prepare for ongoing costs:
- Gather your most recent property tax bill and insurance declarations page to know your exact annual costs.
- Create a separate savings account for housing expenses and fund it monthly, even if the amount is small.
- Review your insurance coverage annually to avoid premium spikes and ensure you are not overpaying.
- If you have an HOA, read the rules on special assessments and factor potential increases into your budget.
Taking these steps not only strengthens your application but also gives you confidence that you can meet the loan obligations long-term. Remember that failing to pay taxes or insurance can lead to default, so a solid plan is essential.
Manage Debts and Credit History Strategically
While a reverse mortgage does not require a minimum credit score, your credit history and debt load affect the lender's assessment. They want to see that you have managed credit responsibly and that your monthly obligations leave room for housing costs. High balances on credit cards, personal loans, or auto loans can signal financial strain. If possible, pay down high-interest debt before applying. Reducing your debt-to-income ratio can lower the risk that the lender requires a large set-aside.
Check your credit reports for errors and dispute any inaccuracies. Late payments, collections, or judgments can linger and raise concerns. If you have negative items, work on improving your payment history and avoid taking on new debt in the months before you apply. A clean credit profile also gives you more options if you decide a reverse mortgage is not right for you.
Consider consolidating high-interest debt with a lower-rate personal loan or a home equity loan, but be cautious: adding new debt can complicate the reverse mortgage assessment. Sometimes the best move is to simply pay down what you can and avoid new credit obligations. If you are unsure, a nonprofit credit counselor can help you create a debt reduction plan.
Plan the Timeline for Counseling and Research
HUD requires that all reverse mortgage applicants complete independent counseling with a HUD-approved counselor before they can proceed. This counseling session covers the loan's costs, alternatives, and obligations. It is a valuable opportunity to ask questions and confirm your understanding. You can complete counseling up to six months before applying, but starting earlier gives you time to absorb the information and adjust your plan.
Begin researching reverse mortgage options at least a year before you turn 62. Attend informational sessions, read lender materials, and compare offers. Use online tools like RateChecker to explore current mortgage rate trends and understand how rates affect reverse mortgage costs. Rates influence the loan's interest charges and the amount you can borrow, so staying informed helps you time your application strategically.
Here is a suggested timeline:
- 12 to 24 months before age 62: Review your overall retirement plan, assess your home's condition, and start building a reserve for taxes and insurance.
- 6 to 12 months before: Complete HUD counseling, gather financial documents, and get quotes from multiple lenders.
- 3 to 6 months before: Address any credit or debt issues, finalize repairs, and choose a lender.
- At age 62: Submit your application and complete the appraisal and underwriting process.
Following this timeline reduces stress and gives you room to make informed decisions. It also allows you to pivot if you discover that a reverse mortgage is not the best fit for your situation.
Explore Alternatives and Understand the Trade-offs
A reverse mortgage is one tool among many for accessing home equity in retirement. Before you commit, compare it to alternatives such as selling and downsizing, taking out a home equity loan, or using a line of credit. Each option has different costs, risks, and implications for your estate. For example, a home equity loan requires monthly payments, while a reverse mortgage does not, but a reverse mortgage accrues interest and reduces the inheritance you can leave.
If you have significant equity but limited cash flow, a reverse mortgage might be appropriate. If you plan to move in a few years, the upfront costs may not be worth it. Discuss your goals with a financial advisor who understands reverse mortgages. They can help you model scenarios and see how each choice affects your long-term financial security.
Also consider the impact on your heirs. A reverse mortgage becomes due when the last borrower moves out or passes away. Your heirs can sell the home to pay off the loan or refinance it, but they may need to act within a certain timeframe. Keeping your family informed and documenting your wishes can prevent confusion later.
Final Steps to Get Your Finances in Order
As you approach age 62, finalize your preparations. Organize your financial documents, including tax returns, bank statements, and proof of income. Make sure your home is in good repair and that you have a clear budget for ongoing costs. If you have not already, complete the required counseling and gather quotes from at least three lenders. Compare not just interest rates but also fees, set-aside requirements, and payout options (lump sum, monthly payments, or line of credit).
Selecting the right lender is critical. Look for lenders with strong reputations and transparent pricing. LoanFinancing.com can connect you with multiple lenders for personalized quotes, helping you compare offers side by side. Remember that submitting an online application implies consent to be contacted by phone or email by network members, so read the terms carefully.
Finally, consider how the loan fits into your broader retirement income plan. A reverse mortgage can provide a safety net, but it should not be your only strategy. Maintain an emergency fund, keep other retirement accounts intact, and revisit your plan annually. With careful preparation, a reverse mortgage can be a valuable tool for a more secure retirement.