
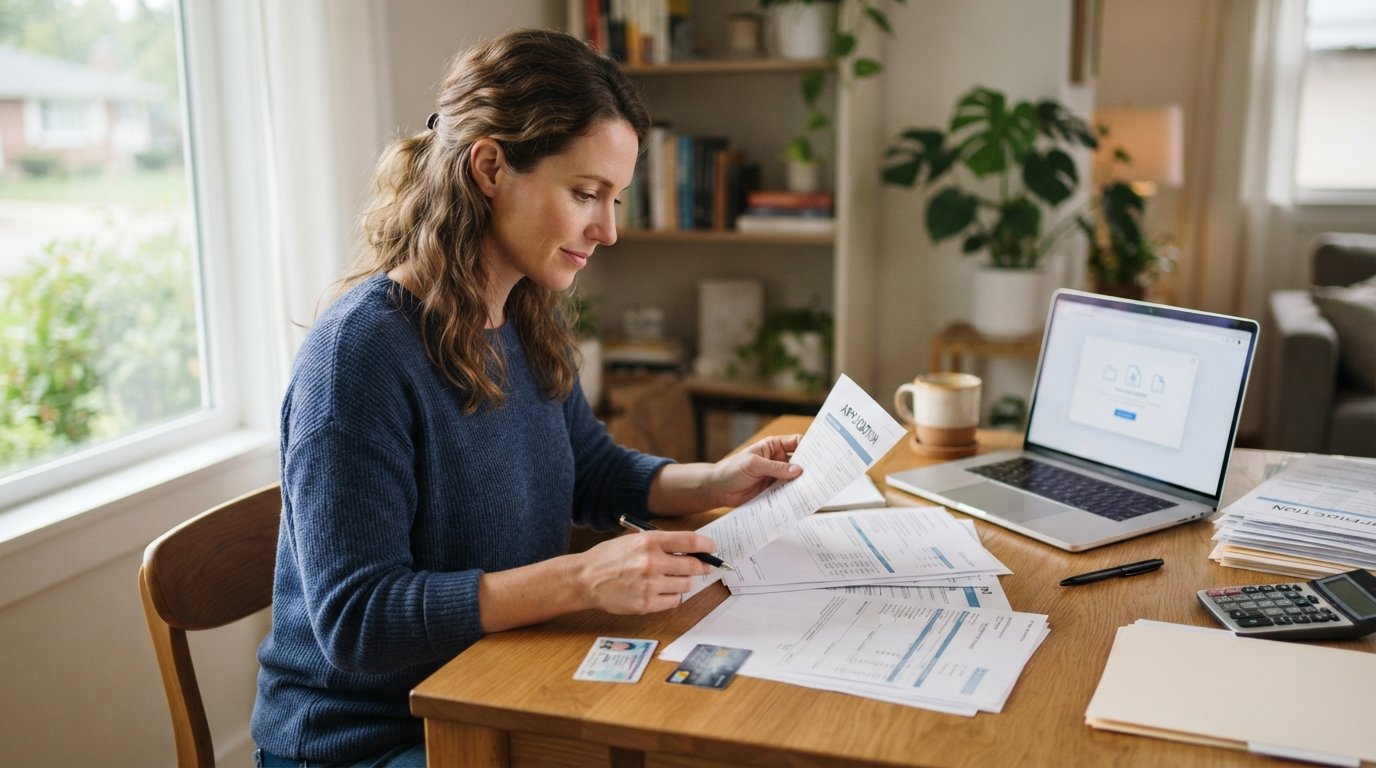
What Documents Do You Need for a Personal Loan?
A clear checklist of what documents do you need to apply for a personal loan, from ID and pay stubs to bank statements, so your application is approved faster.
By Priya Ingram
You have found the right rate, picked a repayment term that fits your budget, and you are ready to hit submit on your personal loan application. Then you see the document upload screen. Suddenly the process feels less like a quick online form and more like a paperwork marathon. The good news is that lenders are not asking for documents to create busywork. Each item on the list serves a specific purpose: proving who you are, showing you can repay the money, and giving the lender confidence that the loan is a reasonable risk. Knowing what to gather before you start can turn a stressful application into a smooth, same-day task.
Understanding what documents do you need to apply for a personal loan is one of the most practical steps you can take to avoid delays, declined applications, or last-minute scrambles. Lenders typically want a consistent package: government-issued identification, proof of income, employment verification, bank statements, and details about existing debts. The exact mix varies by lender, loan amount, and your employment situation. This guide walks through each category, explains how self-employed borrowers differ from salaried employees, and shows how prequalification fits into the picture so you can approach your application with confidence and the right paperwork in hand.
Identity and Contact Information: The Starting Point
Every personal loan application begins with confirming that you are who you say you are. Lenders are required by federal law to verify identity, and they use that information to run credit checks, comply with anti-money laundering rules, and protect against fraud. The most common identity documents include a valid state-issued driver's license or identification card, a U.S. passport, or a permanent resident card. Some lenders also accept a military ID. The document must be unexpired and clearly legible, since blurry photos are one of the most common reasons applications get kicked back.
Beyond the primary ID, lenders usually ask for your Social Security number and proof of address. A utility bill, lease agreement, or mortgage statement dated within the last 30 to 60 days often satisfies the address requirement. If you have recently moved, be prepared to explain the discrepancy between your current address and the one on your ID. Having a recent bill ready can speed up verification and prevent a manual review that could add days to your approval timeline.
Some lenders also request a secondary form of identification, especially for larger loan amounts or if your primary ID has been recently issued. A birth certificate or a second government-issued card can work. Keep in mind that online lenders may use knowledge-based authentication questions or photo verification through a mobile app, so a smartphone with a camera is often part of the process. Gathering these items first creates a clean foundation for everything that follows.
Income and Employment Documentation: Proving You Can Repay
Income verification is the heart of the personal loan application. Lenders want to see that you have a stable, reliable stream of money coming in so they can estimate how comfortably you can handle a new monthly payment. For salaried and hourly employees, this usually means recent pay stubs covering the last 30 to 60 days. Many lenders ask for two to three consecutive pay stubs, and some request a year-to-date pay summary. If you receive direct deposit, your bank statements can also serve as proof of income, though lenders often still want the pay stubs for consistency.
Employment verification typically comes in the form of a job offer letter, an employment contract, or a quick call or email to your employer's HR department. Lenders may also review your W-2 forms from the previous one or two years. If you have recently changed jobs, be ready to explain the move, especially if there was a gap in employment. A stable work history, even with a recent change, is viewed more favorably than long periods of unemployment.
For self-employed applicants, freelance workers, gig economy earners, and business owners, the documentation path looks different. Instead of pay stubs, lenders usually want tax returns from the last two years, including all schedules and K-1s if applicable. They may also request profit and loss statements, 1099 forms, and business bank statements covering six to twelve months. Some lenders accept a signed letter from a CPA verifying your income. Because self-employment income can fluctuate, lenders often calculate an average and may ask for more months of statements to establish consistency. Preparing a clean folder with tax returns and recent bank statements before you apply can make the self-employed path far less intimidating.
Bank Statements and Cash Flow Analysis
Bank statements do more than confirm income. They give lenders a window into how you manage money day to day. Most personal loan applications require at least two to three months of statements from your primary checking account. Lenders look for patterns: whether your balance stays positive, whether deposits are consistent, and whether there are signs of overdrafts or returned payments. A healthy cash flow history can strengthen an application, while frequent overdrafts may raise questions about your budget management.
If you have multiple accounts, you may need to provide statements from each one, especially if you use one account for income and another for bill payments. Some lenders accept PDF statements downloaded directly from your bank, while others use secure third-party verification services that connect to your account with your permission. Either way, redacting sensitive information like your full account number is usually acceptable as long as the lender can still see the account holder name, statement period, and transaction history.
Bank statements also help lenders verify that the money in your account is genuinely yours and not a temporary deposit from a loan or gift. Large, unexplained deposits may trigger additional questions. If you recently received a tax refund, a bonus, or a transfer from a family member, having a brief explanation ready can keep the review moving. The goal is transparency: the clearer your financial picture, the faster the lender can make a decision.
Debt and Credit Information: What Lenders Review
Lenders do not just look at income; they also look at what you already owe. Your credit report provides a detailed history of your credit cards, auto loans, student loans, mortgages, and any collections or public records. While you do not usually need to submit a copy of your credit report yourself, the lender will pull it, and you should review it beforehand to catch errors or surprises. You can access free reports from the major credit bureaus and dispute inaccuracies before applying.
In addition to the credit report, some lenders ask for a list of your monthly debt obligations, including minimum payments and outstanding balances. This helps them calculate your debt-to-income ratio, which compares your total monthly debt payments to your gross monthly income. A lower ratio signals that you have room in your budget for a new loan payment. If your ratio is on the higher side, the lender may ask for additional documentation or offer a smaller loan amount.
If you are using the loan to consolidate credit card debt, be prepared to provide statements for those accounts. Some lenders offer direct payoff to creditors, which can simplify the process and may even reduce your interest rate. Having those statements ready shows the lender exactly how much is needed and supports a clear repayment plan. For anyone exploring broader financing options, the team at Express Mortgage Quotes provides educational resources on home loans and refinancing that can complement your personal loan research, especially if you are weighing multiple financial goals at once.
Prequalification vs. Full Application: Why the Document List Changes
Many lenders offer a prequalification step before a full application. Prequalification is typically a soft credit inquiry that estimates how much you might qualify for and at what rate. It usually requires only basic information like your name, address, income, and Social Security number. Because it is not a formal application, you often do not need to upload pay stubs or bank statements at this stage. Prequalification is a useful way to shop around without affecting your credit score.
A full application, by contrast, is a formal request for credit. This is when the lender verifies everything you stated during prequalification. That means uploading identity documents, income proof, employment verification, and bank statements. The lender may also request additional documents if something needs clarification, such as a letter explaining a gap in employment or a large deposit. Understanding this difference helps you plan: you can prequalify with minimal paperwork, then gather the full document package only when you are serious about a specific offer.
If you are unsure how the application process unfolds from start to finish, our guide on how to apply for a personal loan in 7 steps walks through each stage, from checking your credit to receiving funds. It pairs well with this document checklist so you can see exactly when each piece of paperwork comes into play.
Additional Documents for Special Situations
Not every application fits the standard mold, and lenders have processes for unusual circumstances. If you are retired, you may provide Social Security award letters, pension statements, or investment account statements instead of pay stubs. If you receive disability income, a benefits letter works. If you are a student or a recent graduate with limited income history, a co-signer or proof of future employment may be required. Lenders may also ask for divorce decrees or child support orders if those affect your income or obligations.
For applicants with a history of bankruptcy or foreclosure, additional documentation such as a discharge letter or a explanation of the circumstances may be requested. Lenders want to see that the issue is behind you and that you have reestablished a stable financial footing. Similarly, if you are applying for a joint loan, both applicants typically need to provide the full document set. Co-signers may also need to submit identity and income verification.
Here is a quick checklist of the most commonly requested items so you can assemble your package efficiently:
- Government-issued photo ID (driver's license, passport, or state ID)
- Recent pay stubs covering 30 to 60 days, or W-2s and tax returns if self-employed
- Two to three months of bank statements from your primary checking account
- Proof of address (utility bill, lease, or mortgage statement)
- Debt statements for accounts you plan to consolidate or pay off
Keep in mind that this list is a general guide. Each lender sets its own requirements, and the loan amount, term, and your credit profile can influence what is requested. A small loan with strong credit may require less documentation than a large loan with a thinner credit file. Always check the lender's specific checklist before uploading to avoid back-and-forth delays.
How to Prepare Your Documents and Avoid Delays
The most effective way to streamline your personal loan application is to prepare a digital folder before you start. Scan or photograph each document in good lighting, save it as a PDF or high-resolution image, and name the files clearly (for example, "PayStub_Jan2026.pdf" or "BankStatement_Checking_Q1.pdf"). This makes uploading faster and reduces the risk of submitting an unreadable file. If a lender uses a secure portal, check the file size limits and accepted formats in advance.
Review your documents for consistency. Your name and address should match across your ID, pay stubs, and bank statements. If you have a hyphenated last name or a suffix, make sure it appears the same way on every document. Discrepancies, even minor ones, can trigger manual reviews. If you recently changed your name, have a marriage certificate or court order ready to explain the difference. Small details like these can save you days of waiting.
Finally, be honest and complete. If a document is missing or a detail is unclear, do not guess or leave it blank. Contact the lender's customer service team and ask what they need. Most lenders appreciate proactive communication and will tell you exactly which document will satisfy the requirement. A transparent, well-organized application signals reliability and can improve your chances of approval at a competitive rate.
Gathering the right documents does not have to be overwhelming. With a clear checklist, a few minutes of scanning, and a basic understanding of what each item proves, you can move through the personal loan application with confidence. Whether you are salaried, self-employed, or navigating a special financial situation, the effort you put into preparation now can pay off with faster approvals, better terms, and fewer surprises down the road.