
How to Use a HELOC as an Emergency Fund for Homeowners
A HELOC can serve as a standby emergency reserve for homeowners, but only with the right draw period strategy, cost awareness, and repayment plan.
By Priya Ingram
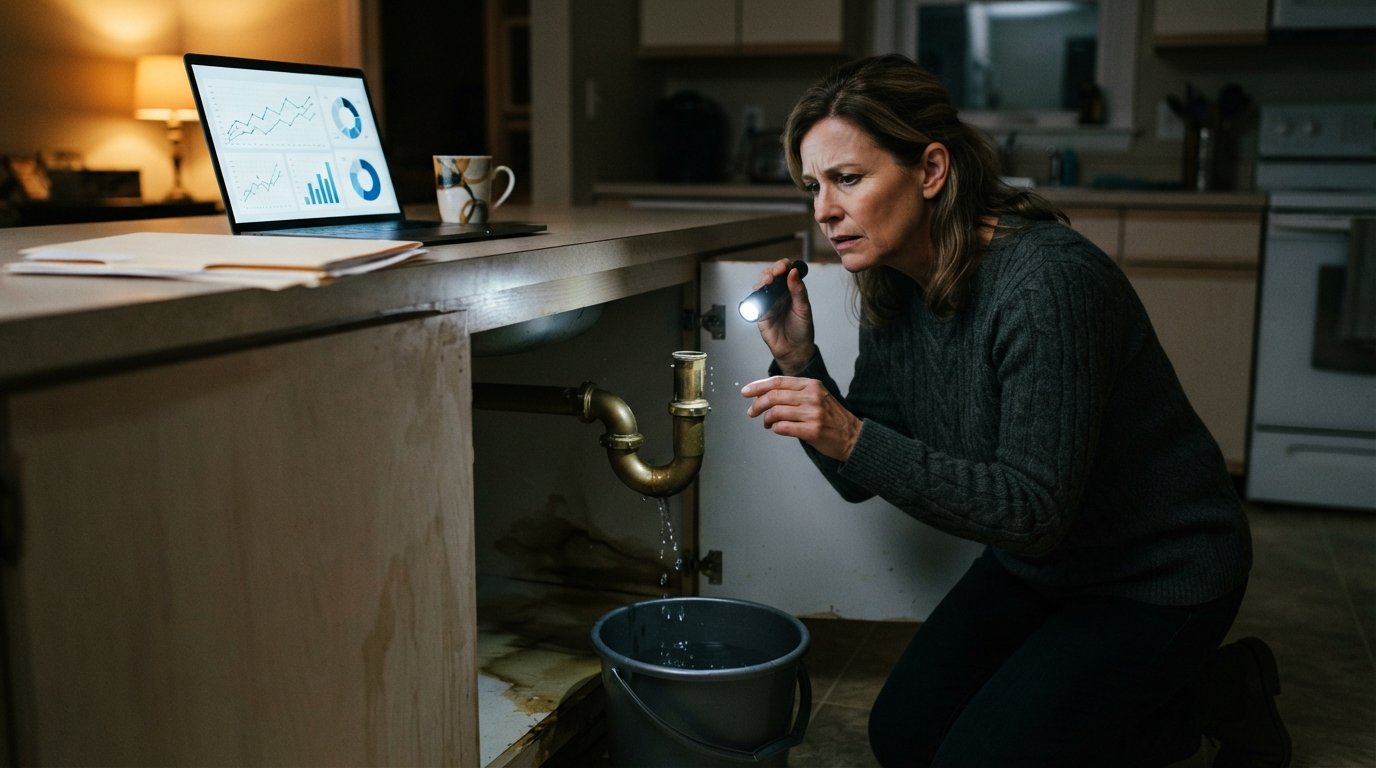
A plumbing leak at 2 a.m. A sudden job loss. A roof that starts sagging after a brutal storm. Homeowners face financial surprises that rarely arrive at a convenient time, and many families do not keep six months of expenses sitting in a savings account. That gap between what life demands and what cash on hand can cover is exactly where a home equity line of credit, or HELOC, enters the conversation. Tapping your home equity as a backup reserve is not the same as spending it, and that distinction matters enormously. Used correctly, a HELOC can act as a financial shock absorber, giving you access to a pre-approved pool of money without forcing you to liquidate investments or swipe a high-interest credit card at the worst possible moment.
The strategy is not without tradeoffs. A credit line tied to your house carries costs, variable interest, and lender behavior you cannot fully control. The goal of this guide is to walk through how to use a HELOC as an emergency fund for homeowners in a way that is deliberate rather than reactive: understanding the draw period, the repayment structure, the true cost of an untouched line, and the moments when a plain cash reserve still wins. By the end, you will know whether a HELOC belongs in your safety net and how to deploy it without turning a temporary setback into a long-term debt problem.
What a HELOC Really Is and Why Homeowners Consider It
A HELOC is a revolving line of credit secured by your home. Unlike a home equity loan, which delivers a lump sum with a fixed repayment schedule, a HELOC lets you borrow, repay, and borrow again during an initial draw period, typically lasting ten years. Interest is charged only on the amount you actually use, which is why an untouched line costs little compared to a lump-sum loan. For homeowners with substantial equity, this makes the HELOC a flexible standby tool: you establish it while your income and credit are strong, then leave it alone until a genuine need appears.
The appeal is easy to understand. Emergency savings in a high-yield account might earn a modest return, but building a full six-month cushion can take years. A HELOC can be arranged in a few weeks and provides immediate access to a much larger sum than most households could park in cash. It also preserves liquidity elsewhere: you do not have to sell stocks during a market dip or cash out retirement accounts to handle a furnace replacement or a medical bill. For households whose equity is large but whose cash flow is tight, the line functions as a bridge rather than a lifestyle upgrade.
That said, a HELOC is debt secured by your primary residence. If you draw on it and cannot repay, the lender has a claim on your home. That single fact should shape every decision about how large a line to open, when to draw, and how quickly to repay. Treating the HELOC as a true emergency reserve, not a shopping account, is the dividing line between a smart safety net and a slow-motion foreclosure risk.
Availability, Draw Period, and Repayment: The Lifecycle of Your Line
Understanding the timeline of a HELOC is essential before you sign anything. Most lines move through two phases. During the draw period, which commonly runs five to ten years, you can borrow against the line as needed. Many lenders require interest-only payments during this time, which keeps monthly obligations low but also means the principal balance does not shrink unless you deliberately pay it down. When the draw period ends, the line enters repayment: you can no longer borrow, and the outstanding balance must be paid back over a set term, often ten to twenty years, at which point payments can jump substantially.
That payment shock is one of the most underestimated risks of using a HELOC as an emergency fund. A household that draws heavily during the draw period and pays only interest could face a monthly payment several times larger once amortization begins. The fix is to plan for repayment from day one: whenever you draw for an emergency, build a realistic schedule to restore the balance, ideally before the draw period closes. Some lenders allow interest-only payments but do not require them, so paying principal voluntarily during the draw period keeps the eventual reset manageable.
Lenders also differ in how they structure closing costs and annual fees. Some waive closing costs entirely but charge an annual maintenance fee or require a minimum draw at opening. Others charge a modest origination fee or a cancellation fee if you close the line within a few years. None of these costs is fatal, but they should be compared across at least two or three lenders before you commit. A line you never use still needs to be cheap enough that keeping it open does not feel like a leak in your budget.
The Costs of Opening a Line You May Never Use
One of the most common questions homeowners ask is whether it makes sense to open a HELOC they hope never to touch. The honest answer is that it can, provided the carrying cost is low and the line is large enough to matter. A standby HELOC is insurance, and like any insurance, it has a premium. That premium usually takes the form of an annual fee, occasional closing costs, and the opportunity cost of having your home equity earmarked for a lender's claim.
Before opening a line, add up the total cost of keeping it for five years without drawing a dollar. Include the application fee, any appraisal cost, annual fees, and the possibility of a cancellation penalty. If the total is a few hundred dollars over several years, the line is probably worth maintaining for the peace of mind. If fees pile up into the thousands, a smaller cash reserve plus a modest personal loan option may be more economical. The point is to make the decision with numbers rather than vibes.
There is also a subtler cost: the psychological effect of having a large credit line available. Research on household finance consistently shows that easy access to credit can increase spending. A homeowner who views the HELOC as a backup emergency fund must be disciplined about what counts as an emergency. Roof failures, medical bills, and sudden income loss qualify. Vacations, furniture upgrades, and impulse renovations do not. Naming the line something boring, like "house reserve," and keeping it out of daily banking apps can help reinforce that boundary.
How to Use the Line: Draws, Interest-Only Payments, and Rate Risk
When an actual emergency arrives, how you draw matters. Most HELOCs come with a checkbook, a debit card, or online transfer capability, and the funds are available almost immediately. The best practice is to draw only what the emergency requires, not the full available limit. Drawing the entire line "just in case" converts a flexible reserve into a large interest-bearing balance and removes the buffer you might need for a second surprise a few months later.
Interest on most HELOCs is variable, tied to an index such as the prime rate plus a margin. That means your monthly cost can rise when the Federal Reserve raises rates, even if your emergency has not changed. During periods of rate volatility, a homeowner carrying a large HELOC balance can see payments climb quickly. The practical response is to prioritize repayment aggressively whenever income allows and to consider converting portions of the balance into a fixed-rate home equity loan if the lender offers that option. Fixed-rate conversion removes uncertainty, though it also closes off the revolving feature for that amount.
Interest-only payments deserve special caution. They keep the monthly bill small, which feels helpful during a crisis, but they also mean the balance stays at its peak. A household that loses income and draws $30,000 from a HELOC could pay only interest for a year and still owe $30,000 when the crisis ends. Building a repayment plan into the emergency response itself, even a modest extra principal payment each month, shortens the tail of the debt and reduces the total interest paid.
When a Cash Reserve Still Beats a Credit Line
For all its flexibility, a HELOC is not a substitute for cash in every situation. Lenders can freeze or reduce a line with little notice, particularly if home values fall in your area or if your credit profile deteriorates. During the 2008 financial crisis, many homeowners watched HELOCs shrink or disappear precisely when they needed them most. A credit line that exists on paper is not the same as money in the bank, and any emergency plan that relies solely on a lender's continued goodwill carries hidden risk.
Cash also wins for small, frequent emergencies. A $600 car repair or a $900 veterinary bill does not justify the paperwork and interest of a home equity draw. A modest emergency fund of one to three months of expenses, held in a liquid savings account, handles those events without touching the house. The HELOC then becomes a second layer of defense for larger, rarer shocks, such as a six-month job loss or a major structural repair that exceeds the cash reserve.
A layered approach works best for most homeowners: a small cash cushion for everyday surprises, a HELOC for mid-sized or prolonged emergencies, and long-term investments left untouched unless the situation is truly catastrophic. If you are still building your cash reserves and want to understand how home-related emergencies fit into a broader savings plan, our guide on creating an emergency fund for home repairs and maintenance walks through sizing and funding strategies that pair well with a standby credit line.
The Risk of a Frozen or Reduced Line and How to Prepare
The single most important vulnerability of a HELOC-based emergency plan is lender discretion. Most HELOC agreements allow the lender to freeze the line or reduce the credit limit if the value of your home declines significantly, if your credit score drops, or if the lender decides the risk profile has changed. You may not receive much warning, and you have limited recourse. Homeowners who treat the full available limit as guaranteed money are setting themselves up for a rude surprise.
Preparing for that possibility means keeping the line healthy even when you are not using it. Pay all bills on time, avoid opening unnecessary new credit accounts, and keep your credit utilization low. If you draw on the HELOC, make at least the required payments promptly and never let the balance drift toward the maximum limit. A line that is used lightly and repaid steadily signals to the lender that you are a low-risk borrower, which reduces the chance of a freeze.
It also helps to diversify your emergency resources. A cash reserve, a HELOC, and access to a retirement account (as a last resort) create redundancy. If the HELOC is frozen, the cash reserve buys time while you explore alternatives. If the cash reserve is depleted, the HELOC provides a bridge. No single tool should carry the entire weight of your family's financial safety net, and a homeowner who understands that is far better positioned than one who assumes a credit line will always be there.
A Practical Framework for Homeowners
Putting the pieces together requires a sequence. First, size the reserve: aim for three to six months of essential expenses in cash if possible, and treat the HELOC as a supplement for costs that exceed that cushion. Second, open the line while your finances are strong, not after a crisis has already begun. Third, compare at least three lenders on fees, rate margins, draw period length, and repayment terms. Fourth, set a personal rule for what qualifies as an emergency and write it down. Fifth, plan repayment before you ever draw, including a target date for restoring the balance.
Homeowners who want to compare HELOC options alongside refinancing and other home equity products can use educational resources to understand how rates and terms differ across lenders. Sites such as RefinancingCo offer mortgage calculators, lender comparisons, and step-by-step guides that help clarify the tradeoffs before you apply. The key is to gather information early, while you have time to think, rather than in the middle of a crisis when pressure favors whichever offer is fastest.
Finally, revisit the plan annually. Home values change, rates change, and your financial situation changes. A HELOC that made sense three years ago may no longer be the best backup, and a cash reserve that felt adequate may need to grow. An annual review of your emergency strategy, including the HELOC's balance, rate, and fees, keeps the safety net intact and prevents small oversights from becoming large problems.
Using a HELOC as an emergency fund is not about maxing out a credit line or pretending debt is savings. It is about building a deliberate, layered reserve that gives your household options when the unexpected arrives. Open the line responsibly, keep cash on hand for the small stuff, draw only for genuine emergencies, and repay with discipline. Done that way, a HELOC can be a quiet, reliable backstop that protects your home and your peace of mind without becoming a burden of its own.