Personal Finance Guide: Master Loans, Budgeting, and Credit
Taking control of your personal finance is one of the most empowering decisions you can make, yet it often feels overwhelming. Between rising interest rates, complex loan terms, and the constant pressure to save more while spending wisely, many Americans struggle to know where to start. The good news is that financial stability does not require a degree in economics or a six-figure salary. It requires a clear understanding of how money moves through your life and a willingness to make intentional choices about borrowing, saving, and investing. Whether you are a first-time homebuyer exploring mortgage options, someone considering debt consolidation through a personal loan, or simply trying to build an emergency fund, the principles remain the same. This guide walks you through the essential pillars of personal finance, with practical steps you can apply today.
Building a Foundation: Budgeting and Cash Flow Management
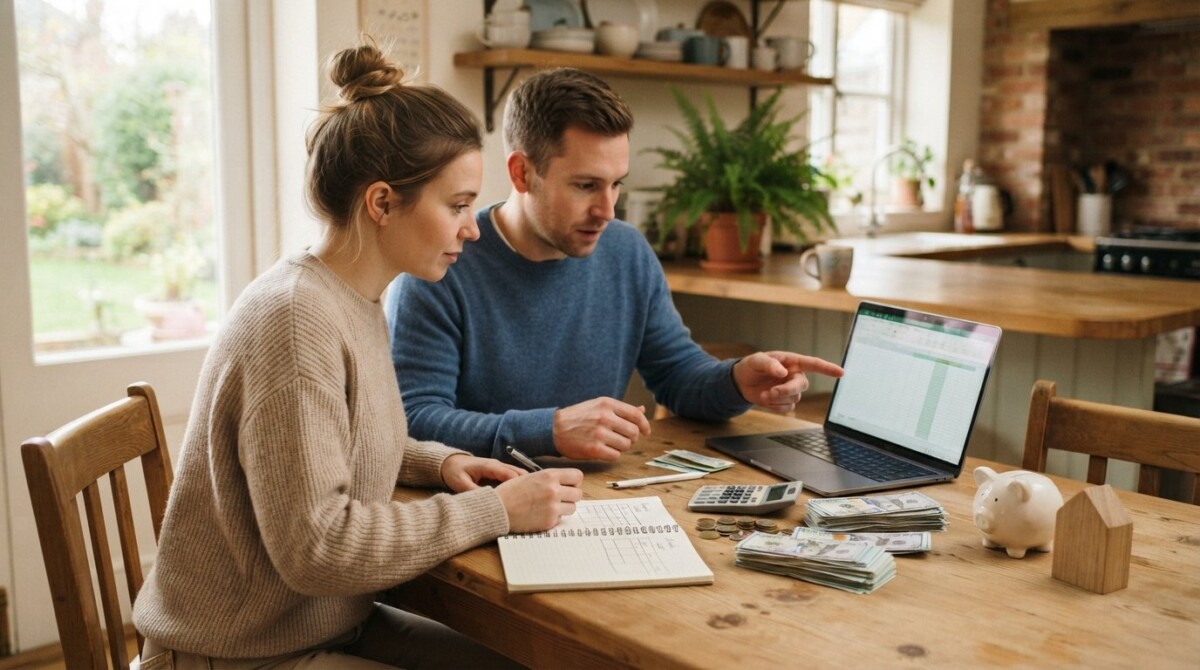
Before you can think about investing or taking out a loan, you need to understand where your money is going. Budgeting is not about restriction; it is about awareness. When you track your income and expenses, you gain the power to redirect your dollars toward what matters most. A simple approach is the 50/30/20 rule: allocate 50 percent of your after-tax income to needs (housing, groceries, utilities, insurance), 30 percent to wants (dining out, entertainment, hobbies), and 20 percent to savings and debt repayment. This framework provides flexibility while ensuring you are always making progress toward financial goals.
Cash flow management goes beyond just tracking spending. It involves timing your bills, building a buffer for irregular expenses, and ensuring you never miss a payment due to poor planning. One effective strategy is to automate your savings and bill payments. Set up automatic transfers to a high-yield savings account on payday, so you save before you have a chance to spend. Similarly, schedule automatic payments for recurring bills to avoid late fees and protect your credit score.
If your budget feels tight, look for areas where you can reduce costs without sacrificing quality of life. This might mean refinancing a high-interest auto loan, negotiating your internet bill, or meal planning to cut grocery expenses. Small changes compound over time. For those with significant debt, a debt consolidation loan can simplify payments and potentially lower your interest rate. Loan Financing offers educational resources and calculators to help you compare options and understand the true cost of borrowing.
Emergency Funds: Your Financial Safety Net
An emergency fund is the cornerstone of financial resilience. Without one, a single unexpected expense, such as a car repair or medical bill, can derail your entire budget and force you to rely on high-interest credit cards. Aim to save three to six months of living expenses in a readily accessible account. If that feels daunting, start small. Even $500 can provide a buffer against minor emergencies and give you peace of mind.
Keep your emergency fund in a separate savings account that you do not touch for non-emergencies. High-yield savings accounts offer better interest rates than traditional checking accounts, helping your money grow while remaining liquid. Once your emergency fund is fully funded, you can shift your focus to other financial goals, such as paying down debt or saving for a down payment on a home.
Understanding Credit and How It Shapes Your Financial Life
Your credit score is one of the most important numbers in your financial life. It influences everything from the interest rate you pay on a mortgage to whether you can rent an apartment or even get a job in some industries. A higher credit score saves you money by unlocking lower interest rates and better loan terms. A lower score can cost you thousands of dollars over the life of a loan.
Credit scores are calculated based on several factors, including payment history, credit utilization, length of credit history, types of credit, and new credit inquiries. Payment history and credit utilization carry the most weight. To improve your score, focus on paying every bill on time and keeping your credit card balances below 30 percent of your available limit. If you carry high balances, consider paying them down aggressively or using a balance transfer to a lower-interest card.
Building credit from scratch or rebuilding after a financial setback takes time and patience. Secured credit cards, credit-builder loans, and becoming an authorized user on a family member’s account are all viable strategies. The key is to demonstrate responsible borrowing over time. Avoid closing old accounts, as this can shorten your credit history and lower your score. Instead, keep them open with a small recurring charge that you pay off each month.
Monitoring Your Credit Report
You are entitled to a free copy of your credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) every year through AnnualCreditReport.com. Review these reports carefully for errors, such as accounts that do not belong to you or incorrect late payments. Disputing errors can improve your score and prevent identity theft. Consider using a credit monitoring service to alert you to changes in your report, but be wary of services that charge high fees for features you can access for free.
If you are planning a major purchase, such as a home or car, check your credit score several months in advance. This gives you time to address any issues and improve your profile before applying for a loan. Loan Financing provides tools and guides to help you understand your credit and explore financing options that fit your situation.
Smart Borrowing: Loans, Mortgages, and Debt Management
Not all debt is created equal. Some debt, like a mortgage or student loan, can be an investment in your future. Other debt, like high-interest credit card balances, can quickly become a burden. Understanding the difference is crucial for making informed borrowing decisions. Before taking on any loan, ask yourself: Does this debt have the potential to increase my net worth or income? If the answer is no, proceed with caution.
When evaluating a loan, consider the Annual Percentage Rate (APR), which includes both the interest rate and any fees. The APR gives you a more accurate picture of the true cost of borrowing than the interest rate alone. Also, consider the loan term. A longer term means lower monthly payments but more interest paid over time. A shorter term means higher monthly payments but less total interest. Choose a term that balances your monthly cash flow needs with your long-term financial goals.
For homeowners, refinancing can be a powerful tool to lower your interest rate, reduce your monthly payment, or tap into home equity for major expenses. However, refinancing comes with closing costs and fees, so you need to calculate the break-even point, the time it takes for your monthly savings to exceed the cost of the refinance. If you plan to stay in your home beyond that point, refinancing may be worthwhile. Loan Financing offers a mortgage calculator to help you run these scenarios and see the potential savings.
Debt Consolidation and Payoff Strategies
If you are juggling multiple high-interest debts, consolidation can simplify your finances and potentially save you money. A debt consolidation loan combines your balances into a single loan with one monthly payment, ideally at a lower interest rate. This can make it easier to stay on track and pay off your debt faster. However, consolidation only works if you commit to not accumulating new debt on the cards you have paid off.
There are two popular methods for paying down debt: the snowball method and the avalanche method. The snowball method focuses on paying off the smallest balance first, which provides a psychological boost as you see quick wins. The avalanche method focuses on paying off the highest-interest debt first, which saves you the most money in interest over time. Both methods work; the best one is the one you will stick with.
- Snowball method: Pay minimums on all debts, then throw every extra dollar at the smallest balance. Once it is paid off, roll that payment into the next smallest debt.
- Avalanche method: Pay minimums on all debts, then focus on the debt with the highest interest rate. This minimizes the total interest you pay.
- Consolidation loan: Combine multiple debts into one loan with a fixed rate and a single payment. Best for those with good credit who can qualify for a lower rate.
- Balance transfer: Move high-interest credit card balances to a card with a 0 percent introductory APR. Best if you can pay off the balance before the promotional period ends.
Whichever strategy you choose, the most important factor is consistency. Set up automatic payments, track your progress, and celebrate milestones along the way. If you feel overwhelmed, consider speaking with a nonprofit credit counselor who can help you create a personalized plan.
Investing and Saving for Long-Term Goals
Once you have a solid budget, an emergency fund, and a plan for managing debt, you can turn your attention to investing. Investing is how you build wealth over time and ensure you can retire comfortably. The earlier you start, the more time your money has to grow through the power of compound interest. Even small amounts invested regularly can grow into substantial sums over decades.
If your employer offers a 401(k) match, contribute at least enough to get the full match. This is essentially free money. Beyond that, consider opening an Individual Retirement Account (IRA), either traditional or Roth, depending on your tax situation. Traditional IRAs offer tax deductions now, while Roth IRAs offer tax-free withdrawals in retirement. For most people, a diversified portfolio of low-cost index funds or exchange-traded funds (ETFs) is a simple and effective way to invest. These funds spread your money across hundreds of companies, reducing risk and minimizing fees.
Do not try to time the market. Studies consistently show that time in the market beats timing the market. Invest regularly, stay diversified, and avoid making emotional decisions based on short-term market fluctuations. If you are unsure where to start, consider consulting a fee-only financial advisor who can help you create an investment plan tailored to your goals and risk tolerance.
Saving for Major Purchases
Whether you are saving for a down payment on a home, a new car, or a dream vacation, having a dedicated savings account for each goal can help you stay motivated. Name your accounts (for example, “House Down Payment” or “Japan Trip”) and set up automatic transfers. When you see your progress, you are more likely to keep going. For short-term goals (under five years), keep your savings in a high-yield savings account or certificates of deposit (CDs) to protect your principal. For longer-term goals, investing in a diversified portfolio may offer better returns, but be prepared for market volatility.
If you are saving for a home, look into first-time homebuyer programs and down payment assistance programs in your state. Many states offer grants or low-interest loans to help with down payments and closing costs. Loan Financing provides resources and guides to help you navigate the homebuying process, from understanding mortgage options to calculating how much house you can afford.
Protecting Your Finances: Insurance and Estate Planning
Insurance is a critical but often overlooked part of personal finance. It protects you and your family from financial ruin in the event of an accident, illness, or death. Health insurance, auto insurance, and homeowners or renters insurance are essential. Disability insurance can replace a portion of your income if you are unable to work due to illness or injury. Life insurance, particularly term life insurance, is important if you have dependents who rely on your income.
Estate planning is another area that many people neglect. A will, a durable power of attorney, and a healthcare proxy ensure that your wishes are respected and your loved ones are cared for if something happens to you. These documents do not have to be complicated or expensive. Online tools and legal services can help you create basic estate planning documents affordably. Review your beneficiaries on retirement accounts and insurance policies regularly to ensure they reflect your current wishes.
Finally, protect your identity and personal information. Use strong, unique passwords for financial accounts, enable two-factor authentication, and monitor your credit report for signs of fraud. Be cautious about sharing personal information online and shred documents that contain sensitive data. If you suspect identity theft, act quickly to freeze your credit and report the issue to the Federal Trade Commission.
Mastering personal finance is a journey, not a destination. Start with a budget, build your emergency fund, and tackle debt one step at a time. As you gain confidence, expand your focus to investing, insurance, and estate planning. The habits you build today will pay dividends for decades to come. For more tools, calculators, and educational resources, explore Loan Financing and take the next step toward financial freedom.
About Sloane Parker
Borrowing Money Wisely: A Guide to Smarter Loans
Borrowing money can build wealth or drain it. Compare rates, understand APR, and use free calculators to cut the total cost of your next loan.
Excellent Credit Loans: How to Secure the Best Rates
Excellent credit loans reward strong scores with lower rates and waived fees. Learn how to qualify and capture the best terms available.
Loan Terms Explained: What Borrowers Must Know
Understand loan terms before you sign. Learn how rates, fees, and repayment schedules affect your total cost and protect your finances.
Find a Loan!