
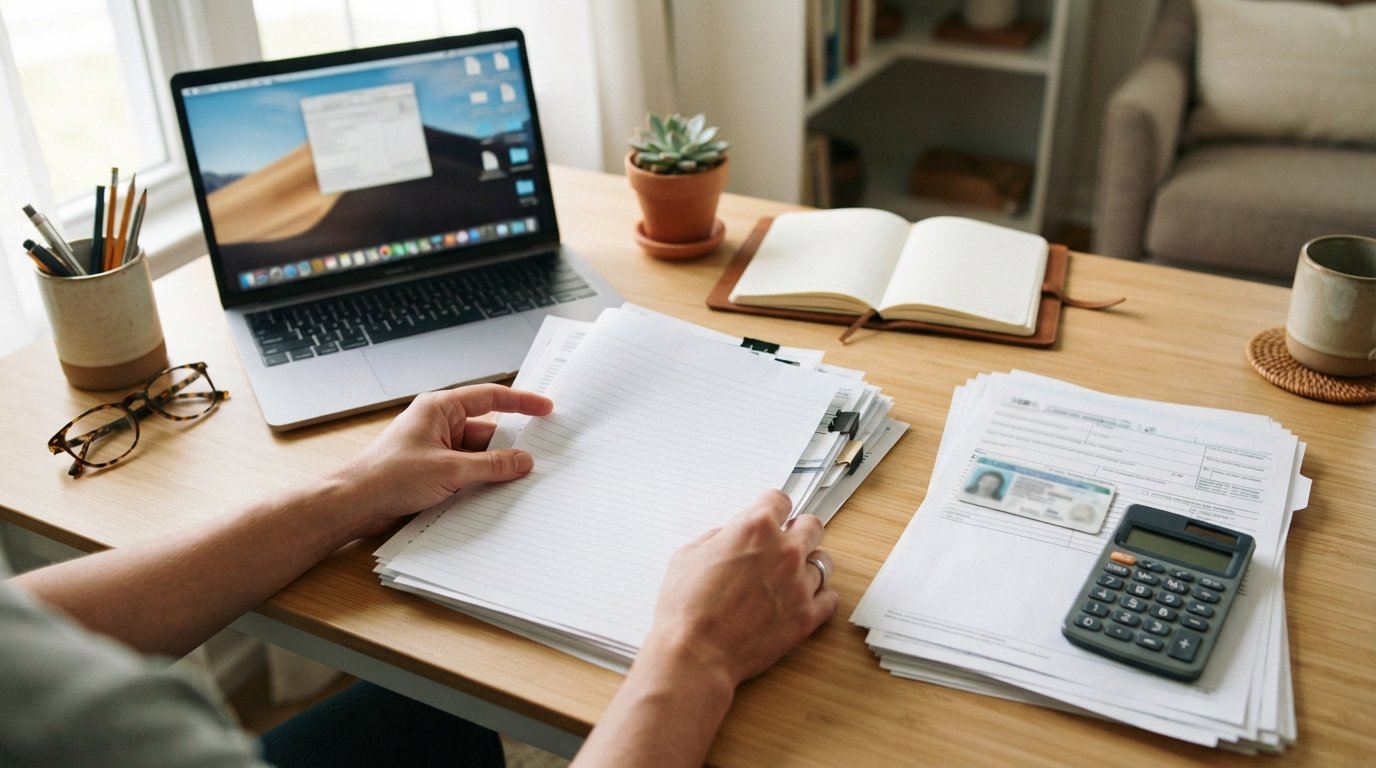
What Documents Do You Need for a Loan Application?
Gather the right documents upfront to avoid delays. This guide covers what documents do you need for a loan application, from income proof to asset statements.
By Yara Adler
You have found the right home, negotiated the price, and are ready to apply for a mortgage. Then your lender hands you a document checklist that looks like a small novel. Suddenly the excitement turns into paperwork anxiety. The same thing happens with personal loans, auto loans, and refinancing. Knowing what documents do you need for a loan application before you start can turn a stressful scramble into a smooth process. This guide walks you through the standard paperwork, explains why lenders ask for it, and shows you how to prepare so your application does not stall.
The Core Document Checklist for Any Loan Application
Most lenders follow a similar framework when verifying your eligibility. They want to confirm three things: who you are, that you can repay the loan, and that the asset backing the loan (if any) is properly secured. While specific requirements vary by loan type and lender, the core set of documents rarely changes. Preparing these in advance will cover the majority of requests.
Here is a practical list to gather before you apply:
- Government-issued photo ID: A driver's license, passport, or state ID. Lenders use this to prevent identity fraud.
- Proof of income: Recent pay stubs (usually the last 30 days), W-2 forms, or tax returns for self-employed borrowers.
- Employment verification: Contact information for your employer or recent offer letters if you are starting a new job.
- Bank statements: Typically two to three months of statements for all accounts you want considered.
- Proof of residence: A utility bill, lease agreement, or mortgage statement showing your current address.
Having these items digitized and organized in a folder on your computer or phone will speed up the process. Many lenders now allow you to upload documents directly through a secure portal, which is a feature of modern digital loan applications. In fact, understanding how a digital loan application works and why to use one can help you avoid common delays caused by missing signatures or unreadable scans. The key is to treat document collection as the first step, not an afterthought.
Income and Employment Documentation: Proving You Can Repay
Your income is the backbone of your loan application. Lenders calculate your debt-to-income ratio (DTI) by comparing your monthly debt obligations to your gross monthly income. A lower DTI signals that you have room in your budget to take on a new payment. To verify income, lenders require documentation that shows consistency and stability. For salaried employees, this usually means the most recent 30 days of pay stubs and the last two years of W-2 forms. If you receive bonuses or overtime, be prepared to show a history of that income as well.
Self-employed borrowers and independent contractors face a higher documentation bar. Lenders typically ask for two years of personal and business tax returns, including all schedules and K-1s. They may also request a year-to-date profit and loss statement and business bank statements. The goal is to confirm that your income is ongoing and sufficient to cover the new loan payment. If your income has recently changed (for example, you switched from a salaried job to freelancing), be ready to provide additional context and possibly a letter of explanation.
For those using alternative income sources, such as rental income, disability payments, or retirement distributions, documentation requirements differ. You might need to provide lease agreements, award letters, or account statements showing consistent deposits. Regardless of the source, the principle is the same: document the money trail. Lenders are not trying to make your life difficult; they are following regulations that require them to verify your ability to repay.
Asset and Down Payment Verification
Lenders want to see that you have funds available for a down payment and closing costs, and they need to confirm that the money is legitimately yours. For a mortgage, you will typically need to provide two to three months of statements for checking, savings, and investment accounts. If you are receiving a gift for the down payment, you will need a gift letter signed by the donor, plus documentation showing the transfer of funds. Lenders may also ask for a paper trail if you made a large deposit recently; they want to ensure the funds are not from an undisclosed loan.
For personal loans, asset verification is less common unless you are using a secured loan, but some lenders still ask for bank statements to assess your overall financial picture. If you are applying for a home equity loan or line of credit, the lender will order an appraisal of your property to determine its value. In that case, you will need to provide access to your home and possibly documentation related to your current mortgage, such as your latest statement.
When preparing asset documents, be thorough. Provide all pages of each statement, even the ones that seem blank. Redact sensitive information like account numbers if you are uploading to a portal, but do not obscure the transactions or balances. Inconsistent or incomplete statements are one of the most common reasons for underwriting delays. If you have multiple accounts, consolidate them into a single PDF for easier review.
Credit and Debt Documentation
Your credit report is pulled by the lender, so you do not need to provide it yourself. However, you should review your credit reports before applying to catch any errors or identify potential issues. If you have a credit freeze in place, you will need to lift it temporarily so the lender can access your file. Additionally, if you have any derogatory marks, such as a recent late payment or collection, be prepared to write a letter of explanation. Lenders appreciate transparency and may be more forgiving if you can demonstrate that the issue was a one-time event.
For debt obligations, lenders will see your minimum monthly payments on your credit report. But if you are paying child support, alimony, or other obligations not reported to the credit bureaus, you may need to provide court orders or divorce decrees. Similarly, if you are using a co-signer, that person will need to submit their own documentation, including income, asset, and identity verification. Remember that co-signing does not remove your responsibility; both parties are on the hook.
If you are applying for a loan to consolidate debt, the lender may ask for statements from the accounts you plan to pay off. This helps them understand your current debt load and ensure that the new loan will actually improve your financial situation. Keep these statements handy, as they are often requested during the underwriting stage.
Property-Specific Documents for Mortgages
When you apply for a mortgage, the property itself becomes part of the documentation package. Lenders need to confirm that the home is worth the amount you are borrowing and that it meets their collateral requirements. The first item is the purchase contract, fully signed by all parties. This contract outlines the sale price, closing date, and any contingencies. If you are refinancing, you will provide your current mortgage statement and homeowners insurance policy instead.
The lender will also order an appraisal, but you may need to provide a copy of the appraisal if you already have one. Additionally, you will need to show proof of homeowners insurance with a policy that meets the lender's requirements. In some cases, you may need to provide a flood certification or proof that the property is not in a flood zone. For condominiums, the lender may request HOA documents, including budgets and meeting minutes, to assess the financial health of the association.
If you are buying a new construction home, the documentation may include builder contracts, specifications, and a certificate of occupancy. For investment properties, you will need to provide lease agreements and a rent roll. The list can seem long, but each document serves a purpose: protecting both you and the lender by ensuring the property is a sound investment.
Special Situations: Self-Employment, Gifts, and Foreign Nationals
Certain borrowers face additional documentation requirements. Self-employed individuals, as mentioned, need to provide business tax returns and possibly a profit and loss statement. If you own rental properties, you will need to document rental income with lease agreements and tax returns. If you are using gift funds, the gift letter must state that the funds are not a loan and do not need to be repaid. The donor may also need to provide bank statements to show the source of the gift.
Foreign nationals applying for a U.S. loan may need to provide a copy of their passport, visa, and possibly a credit report from their home country. Some lenders require a U.S. credit history, while others offer programs for foreign nationals with alternative documentation. If you are a permanent resident, your green card serves as identification. Always check with your lender about specific requirements for your situation, as they can vary widely.
Another special situation involves borrowers with no credit score. Some lenders offer non-traditional credit verification, which may require letters from landlords, utility companies, or insurance providers confirming timely payments. This is more common with personal loans or certain first-time homebuyer programs. Be proactive in asking your lender what alternatives they accept, as gathering these letters can take time.
How to Organize and Submit Your Documents Efficiently
The way you organize and submit your documents can significantly affect the speed of your approval. Start by creating a digital folder structure on your computer or cloud storage. Label each file clearly, for example, "2025 W-2" or "January 2026 Bank Statement." Scan documents at a high resolution so they are easy to read, and save them as PDFs. Avoid taking photos with your phone unless you have a scanning app that produces clean, legible images.
When you are ready to apply, use the lender's secure portal to upload your documents. Do not email sensitive information unless the lender explicitly provides a secure email option. Most lenders will send you a list of required documents through their portal, and you can check off items as you upload them. Keep a copy of everything you submit for your records. If you are working with a loan officer, ask them to confirm receipt and review the documents for completeness before the file goes to underwriting.
One often overlooked step is to write a cover letter or a brief explanation for any unusual items. For example, if you had a gap in employment, a large deposit, or a change in income, a short letter can preempt questions from the underwriter. This simple act can save days of back-and-forth. Remember, the underwriter's job is to assess risk, and providing context helps them understand your unique situation.
Finally, stay responsive. If the lender requests additional documents, provide them promptly. Delays in submitting paperwork are a leading cause of missed closing dates. Set aside time each day to check your email and portal for updates. By treating document collection as a priority, you demonstrate to the lender that you are a serious and reliable borrower.
Common Mistakes to Avoid
Even well-prepared borrowers can stumble on a few common pitfalls. First, do not provide incomplete statements. If a bank statement has multiple pages, include all of them, even the pages with just a few lines. Lenders need to see the full picture. Second, do not alter documents. Photoshop or correction fluid can be grounds for denial and may even be considered fraud. If a document has an error, contact the issuing institution to get a corrected version.
Third, do not wait until the last minute. Gathering tax returns, bank statements, and other records can take days or weeks, especially if you need to request them from third parties. Start the process as soon as you decide to apply. Fourth, do not assume that an online application means no paperwork. Digital applications still require you to upload scanned documents, and the same verification rules apply.
Lastly, be honest. If you have a previous bankruptcy, foreclosure, or late payments, disclose them upfront. Lenders will find out anyway, and hiding information can lead to denial or worse. A candid explanation, along with evidence of financial recovery, can sometimes turn a red flag into a non-issue. Remember, lenders want to say yes, but they need to manage risk. Your transparency helps them do that.
When you are comparing loan offers, whether for a mortgage, personal loan, or refinance, having your documents ready can also give you leverage. You can quickly respond to multiple lenders and compare terms side by side. For those exploring mortgage options, platforms like ExpressMortgageQuotes can help you understand loan products and gather quotes from verified lenders, all while you have your paperwork organized and ready to submit. This approach saves time and reduces stress.
In summary, the documents you need for a loan application are not meant to be a barrier but a bridge to your financial goal. By knowing what to gather and how to present it, you can navigate the application process with confidence. Start early, stay organized, and communicate openly with your lender. Your future self will thank you for the effort.