Family Emergency Loans: Fast Options When Crisis Hits
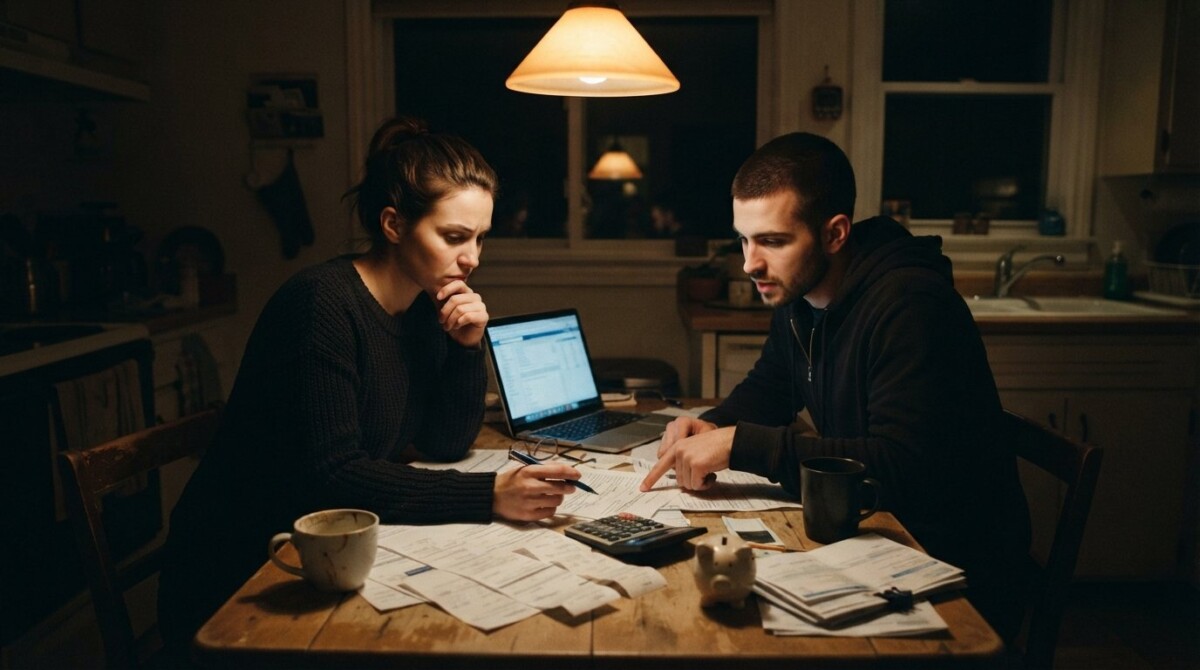
A burst pipe at midnight, a sudden hospital stay, or a car that will not start before work: emergencies rarely announce themselves, and they almost never wait for payday. When a family crisis collides with an empty bank account, the pressure to find money fast can feel overwhelming. The good news is that you have more options than you might think, and understanding them before you sign anything can save you hundreds or even thousands of dollars. This guide breaks down how family emergency loans work, where to find them, what they truly cost, and how to protect your household from long-term financial damage.
What Are Family Emergency Loans and Who Needs Them
Family emergency loans are simply loans used to cover urgent, unplanned expenses that affect your household. The category is defined by the purpose, not the lender. A personal loan from a bank, a small short-term loan from a credit union, or even a credit card cash advance can all function as a family emergency loan if the money goes toward an immediate need. Common triggers include medical bills, urgent home repairs, funeral costs, travel for a family crisis, and replacing a vehicle you depend on for work.
What separates a genuine emergency from ordinary spending is timing and necessity. A leaking roof that threatens your belongings is an emergency. A kitchen remodel is not, even if it feels urgent in the moment. Before you borrow, ask one honest question: will waiting two weeks cause real harm to my family or my finances? If the answer is yes, it is worth exploring loan options. If the answer is no, saving first or using a smaller line of credit may be smarter.
Families often turn to emergency borrowing because they lack a fully funded emergency fund. Financial planners typically suggest setting aside three to six months of living expenses, but the reality is that many U.S. households could not cover a $1,000 surprise expense without borrowing. That gap is exactly why the emergency loan market exists, and why knowing how it works matters so much.
Common Types of Family Emergency Loans
There is no single product called a “family emergency loan.” Instead, you choose among several borrowing tools, each with different speeds, costs, and qualification requirements. The right choice depends on how much you need, how fast you need it, and how strong your credit profile is. If you want a broader overview of rapid funding options, our guide on emergency loans for unexpected bills walks through the fastest paths to cash.
Here are the main categories most families consider, along with their trade-offs:
- Personal loans: Unsecured installment loans from banks, credit unions, or online lenders. They offer fixed rates and predictable monthly payments, with funding often in one to three business days.
- Credit union small loans: Many credit unions offer PALs (payday alternative loans) with capped fees and more forgiving credit requirements than banks.
- Credit card cash advances: Instant access but expensive, with high APRs, upfront fees, and no grace period on interest.
- Home equity lines of credit: Lower rates for homeowners, but approval takes weeks and your home secures the debt.
- Family loans: Money from relatives, ideally documented with a simple written agreement to protect relationships.
Payday loans and title loans deserve special caution. They can deliver cash within minutes, but their annual percentage rates frequently exceed 300 percent, and borrowers often roll them over into a cycle of debt. For most families, these products should be a last resort, not a first stop.
How to Qualify and What Lenders Look For
Qualification standards vary widely by lender and product, but nearly every application boils down to three questions: can you repay, will you repay, and what happens if you do not? Lenders answer those questions using your credit history, income, debt-to-income ratio, and collateral. Understanding this framework helps you target the lenders most likely to approve you instead of applying everywhere and collecting rejections.
For an unsecured personal loan, most lenders want a credit score in at least the mid-600s, though some online lenders work with scores in the 580 to 620 range at higher rates. They will verify employment or income, check your rent or mortgage payment history, and calculate how much of your monthly income goes toward existing debts. A debt-to-income ratio below 43 percent is a common cutoff, and a lower ratio usually earns a better interest rate.
If your credit is damaged, you still have paths forward. Options include applying with a cosigner who has strong credit, using a secured loan backed by a savings account, or borrowing from a credit union that weighs your relationship and payment history more heavily. Before applying anywhere, pull your credit reports, dispute any errors, and gather recent pay stubs or tax returns so you can move quickly if an emergency hits.
How to Get a Family Emergency Loan Fast: A Step-by-Step Plan
Speed matters in a crisis, but panic-borrowing is how people end up with 400 percent APR loans they cannot escape. A short, disciplined process keeps you fast without being reckless. The goal is to compare at least three offers and choose the one with the lowest total cost, not just the lowest monthly payment.
- Define the exact amount you need, including a small buffer for fees, and write down your deadline for receiving the funds.
- Check your credit score and reports so you know which lenders are realistic before you apply.
- Gather documents: government ID, proof of income, bank statements, and any bills tied to the emergency.
- Request quotes from at least three lenders, including a local credit union, and compare APR, fees, and repayment terms side by side.
- Review the loan agreement carefully, confirm there is no prepayment penalty, and sign only when the total cost is clear.
After you complete these steps, set up automatic payments for the day after your paycheck lands. On-time payments protect your credit score and remove the risk of late fees during an already stressful period. If your situation changes and you cannot pay, contact the lender immediately to discuss hardship options rather than ignoring the bill.
What Family Emergency Loans Really Cost
The sticker price of a loan is rarely the full story. Interest is only one component; origination fees, late fees, prepayment penalties, and the length of the repayment term all shape what you ultimately pay. A loan with a lower rate but a five-year term can cost more in total interest than a slightly higher-rate loan repaid in two years. Always compare the APR, which bundles most fees into a single percentage, and ask for the total repayment amount in dollars.
Consider a simple example. Borrowing $3,000 at 12 percent APR over 24 months costs roughly $141 per month and about $390 in total interest. The same $3,000 at 36 percent APR over 36 months, a rate common among lenders serving weaker credit, costs about $137 per month but more than $1,900 in total interest. The monthly payments look almost identical, yet one loan costs five times more. This is why reading the full terms matters more than focusing on the payment.
If you own a home and the emergency is large, a home equity option may offer a far lower rate, but it converts unsecured debt into debt secured by your house. That trade-off can be reasonable for a disciplined borrower and dangerous for someone already stretched thin. Our overview of refinancing a mortgage explains how homeowners can evaluate whether tapping equity makes sense, including the closing costs and timeline involved. Running the numbers with a mortgage calculator before committing can show you the real monthly impact on your household budget.
Alternatives to Borrowing When Money Is Tight
Before signing a loan agreement, confirm that borrowing is genuinely your best option. Several alternatives can cover an emergency without adding debt, and they are worth a few phone calls even when you are in a hurry. The key is to match the solution to the size and urgency of the expense.
Start by negotiating directly with the party you owe. Hospitals frequently offer interest-free payment plans or charity care for qualifying patients, and many contractors will accept partial payment to begin urgent work. Utility companies often have hardship programs, and landlords may allow a short delay on rent if you communicate early. These conversations cost nothing and can eliminate the need to borrow entirely.
If you still need funds, explore these lower-cost sources in order: a small withdrawal from an emergency fund, a 0 percent introductory credit card offer if you can repay before the promo period ends, a loan against your 401(k) if your plan allows it, or a personal loan from a credit union. Each has drawbacks, but all are generally cheaper and safer than payday or title loans. Selling unused items or taking on short-term gig work can also close a small gap without creating a new monthly obligation.
Protecting Your Family From the Next Emergency
Once the immediate crisis passes, shift your attention to prevention. The families who handle emergencies best are not necessarily wealthier; they are simply prepared. Building even a modest cushion changes the math entirely, because $1,000 in savings can replace a high-interest loan and its fees. Start with a goal of $500, then grow it steadily with automatic transfers of any amount you can sustain.
Review your insurance coverage annually, including health, auto, and homeowners or renters policies. Many “emergencies” are actually coverage gaps: a low deductible you cannot afford, a policy exclusion you never noticed, or no disability coverage if your income suddenly stops. An hour spent reviewing documents with your insurer or a financial advisor can prevent a future crisis from becoming a debt crisis.
Finally, keep a simple emergency binder or digital folder with key documents: insurance policies, loan agreements, account numbers, and contact information for your bank and credit union. When the next surprise arrives, you will be able to act in hours instead of days. Preparedness will not stop emergencies from happening, but it will stop them from derailing your family’s financial future.
About Sloane Parker
Mortgage Refinance: When Does It Actually Pay Off?
Discover when a mortgage refinance truly pays off, including break-even analysis, credit score tips, and cash-out strategies to lower payments.
Financing Options That Match Your Credit Profile
Explore financing options that match your credit profile, from FHA loans to debt consolidation, and learn how to secure the best rate for your situation.
How Credit Building Loans Work: A 2026 Playbook
Credit building loans let you establish on-time payment history while saving money. See how they work and how to use them to lift your score.
Find a Loan!