Loan Calculator Guide: Estimate Monthly Payments
A loan calculator turns an intimidating borrowing decision into a clear, numbers-based picture. Instead of guessing whether a monthly payment fits your budget, you can see the exact figure in seconds, along with the total interest you will pay over the life of the loan. That single advantage, knowing the real cost before you sign, is why borrowers who run the numbers first consistently negotiate better terms and avoid unpleasant surprises. Whether you are comparing personal loan offers, testing mortgage scenarios, or checking whether refinancing makes sense, a reliable calculator is the fastest path from question to answer.
What a Loan Calculator Actually Does
At its core, a loan calculator applies a standard amortization formula to three inputs: the loan amount (principal), the interest rate, and the repayment term. The output is your fixed monthly payment, assuming a standard installment loan with equal payments. Behind that simple result, the tool is doing something valuable: it separates your payment into two very different buckets. One bucket pays down the money you borrowed. The other pays the lender for the privilege of borrowing. Early in the loan, most of your payment goes to interest. Later, the balance shifts toward principal.
Understanding that split changes how you think about borrowing. A 60-month auto loan at 8 percent and a 72-month auto loan at 8 percent can look nearly identical on a dealership lot, because the longer term lowers the monthly payment. But the calculator reveals the trade-off: the 72-month version can cost you well over a thousand dollars more in total interest. That is the kind of insight a calculator delivers in one glance, and it is nearly impossible to replicate with mental math.
Most calculators also display the total cost of the loan (principal plus interest) and sometimes an amortization schedule showing each payment over time. Some include extra fields for taxes, insurance, and fees, which matter enormously for mortgages. The more complete the input set, the more realistic the output. A payment estimate that ignores property taxes and homeowners insurance is not wrong, but it is incomplete, and incomplete numbers are how borrowers end up with surprise bills at closing.
The Inputs That Matter Most
Every result a calculator produces is only as good as the numbers you feed it. Three inputs drive the output, and each one deserves a moment of attention before you start comparing scenarios.
- Loan amount: The principal you borrow, after any down payment. For a mortgage, this is the purchase price minus your down payment; for a personal loan, it is the amount you request.
- Interest rate: The annual cost of borrowing, expressed as a percentage. This is where your credit score, income, and debt-to-income ratio do their work.
- Loan term: How long you have to repay, usually expressed in months or years. Longer terms lower the payment but raise total interest.
The interest rate is the input borrowers most often underestimate. A single percentage point can swing a monthly payment by tens or hundreds of dollars depending on the loan size. On a $300,000 mortgage, the difference between 6.5 percent and 7.5 percent is roughly $200 per month, which adds up to more than $70,000 over 30 years. That is why rate shopping is not a formality; it is the highest-leverage move in the entire borrowing process.
The term deserves equal respect. Stretching a loan from 15 to 30 years can cut a mortgage payment nearly in half, but you will pay interest for twice as long. There is no universally correct answer here. The right term depends on your cash flow, your plans for the property or purchase, and how aggressively you want to eliminate debt. A calculator lets you test all of these scenarios side by side in minutes, which is far better than committing to one structure and hoping it works out.
How to Use a Loan Calculator Step by Step
Running the numbers takes less time than making a cup of coffee. The value comes from doing it consistently, the same way each time, so your comparisons are apples to apples.
- Gather your numbers: the amount you need, the rate you have been quoted (or expect), and the term you are considering.
- Enter the figures into the calculator and note the monthly payment and total interest.
- Change one variable at a time. Try a shorter term, then a lower rate, then a smaller loan amount, and watch how each change moves the result.
- Compare at least three scenarios side by side, including one aggressive option (shorter term or larger down payment) and one conservative option.
- Save or screenshot your results so you can reference them when you talk to lenders.
Step three is where most of the learning happens. Changing one variable at a time isolates its effect, which teaches you which lever matters most for your situation. For some borrowers, the rate is everything because their credit is on the borderline. For others, the loan amount dominates because they are stretching to afford a home. Once you know your sensitive variable, you know where to focus your negotiation energy.
If you are working through a personal loan scenario, a focused tool makes this process even faster. Our walkthrough on how to estimate payments fast with a personal loan calculator covers the exact inputs and shortcuts that produce accurate results in under a minute. Pairing that with a mortgage-focused tool gives you full coverage across the two most common borrowing situations.
Loan Calculator vs. Mortgage Calculator: What Is the Difference
The two tools share the same mathematical engine, but they serve different purposes and accept different inputs. A general loan calculator handles any installment loan: personal loans, auto loans, student loans, and simple fixed-rate mortgages. You enter principal, rate, and term, and you get a payment. It is clean, fast, and universal.
A mortgage calculator goes further because mortgage payments are not a single number. Your monthly housing cost typically includes four components, often called PITI: principal, interest, taxes, and insurance. Property taxes vary by county and can add several hundred dollars per month. Homeowners insurance is required by most lenders. PMI (private mortgage insurance) applies if your down payment is under 20 percent. HOA dues apply in many neighborhoods. A mortgage calculator that ignores these costs will understate your real payment, sometimes by 20 percent or more.
This is why Loan Financing pairs its educational content with a dedicated mortgage calculator tool that accounts for the full picture of homeownership costs. For first-time buyers especially, seeing the complete PITI figure before house hunting prevents the painful scenario of falling in love with a home you cannot actually afford once taxes and insurance are included. The general loan calculator tells you what the loan costs; the mortgage calculator tells you what the house costs.
Reading the Amortization Schedule
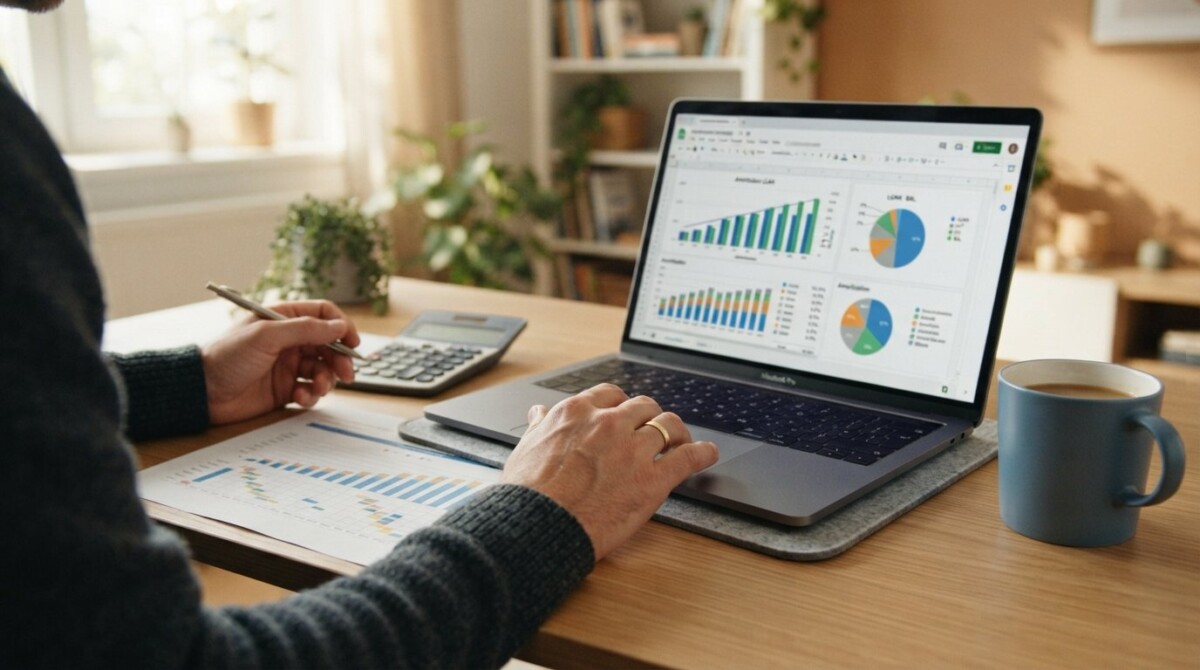
An amortization schedule is a table showing every payment over the life of the loan, split into principal and interest portions. It looks boring and it is quietly one of the most useful documents in personal finance. The schedule shows you exactly when your balance will cross certain thresholds, which matters for several real decisions.
For mortgages, the schedule tells you when you will reach 20 percent equity and can request PMI cancellation. It shows how much you would save by making one extra payment per year, which on a 30-year mortgage can shorten the term by four to six years. For auto loans, it reveals how quickly you build equity relative to depreciation, which determines whether you can sell the car without owing more than it is worth. For personal loans, it clarifies whether paying off early actually saves meaningful interest or whether the loan is front-loaded with fees.
Most online calculators generate the schedule automatically. If yours does not, run the same calculation with a slightly smaller balance to approximate the effect of extra payments. The habit of checking the schedule once a year keeps you informed about your true payoff timeline rather than the one printed on your original statement.
Common Mistakes When Using Loan Calculators
The tool is only as smart as its operator. A few recurring errors undermine the value of even the best calculator, and each one is easy to avoid once you know it exists.
The first mistake is using the advertised rate instead of your actual rate. Lenders advertise their best rates, reserved for borrowers with excellent credit. If your credit score is average, your real rate could be two or three points higher. Enter the rate you realistically qualify for, not the one on the banner.
The second mistake is ignoring fees. Origination fees, closing costs, and prepaid interest are real money that a basic calculator may not capture. On mortgages, closing costs typically run 2 to 5 percent of the loan amount. On personal loans, origination fees of 1 to 8 percent are common. When comparing offers, look at the APR rather than the interest rate, because APR folds most fees into a single comparable number.
The third mistake is treating the result as a budget approval. A calculator tells you what a payment would be, not what you can comfortably afford. Lenders will often approve you for more than is wise. A useful rule of thumb is to keep total housing costs under 28 percent of gross monthly income and total debt payments under 36 percent. If the calculator output pushes past those lines, the loan may technically be affordable but financially risky.
The fourth mistake is running the numbers once and never again. Rates move, your credit improves, and your income changes. Recalculating every few months, especially before a major borrowing decision, keeps your assumptions current. For anyone planning to refinance, our guide to refinancing a mortgage explains how to use calculator outputs to determine your break-even point, which is the month when refinancing savings finally exceed the closing costs.
Using Calculator Results to Negotiate Better Terms
Walking into a lender conversation with calculator results changes the dynamic. You are no longer asking what a loan might cost; you are presenting specific scenarios and asking the lender to beat them. That posture tends to produce better offers, because lenders know you have done the work.
A practical approach: run three scenarios (your target term, a shorter term, and a larger down payment version), then request quotes for each. Ask each lender for the APR, not just the rate, and ask whether any fees are negotiable. Compare the quotes against your calculator outputs. If a lender’s numbers come in higher than expected, ask why. Sometimes the answer is a fee you can eliminate; sometimes it is a rate you can negotiate with a competing offer in hand.
This process works for auto loans, personal loans, and mortgages alike. The borrowers who save the most are rarely the ones with perfect credit; they are the ones who compare systematically and ask informed questions. A calculator is the tool that makes those questions possible.
Frequently Asked Questions
Is a loan calculator accurate?
For fixed-rate installment loans, a calculator using the standard amortization formula is highly accurate, matching lender figures to the penny when the inputs are correct. Accuracy drops when fees, variable rates, or escrow items are excluded, so always confirm the final numbers with the lender.
What is the difference between interest rate and APR?
The interest rate is the cost of the borrowed principal. The APR includes the interest rate plus most lender fees, expressed as a single annual percentage. APR is the better comparison tool when shopping between offers.
Can I use a loan calculator for an adjustable-rate loan?
Yes, but with caution. Enter the initial fixed rate to see the starting payment, then run separate calculations at higher rates to stress-test what the payment could become after the rate adjusts. Budgeting for the higher figure is the safer approach.
Does a longer loan term ever make sense?
Yes, when cash flow is tight or when the borrowed money is invested in an appreciating asset. The key is entering the decision with full knowledge of the extra interest cost, which the calculator provides instantly.
How often should I recalculate?
Before any new borrowing, after any significant credit score change, and whenever market rates move meaningfully. A quick recalculation takes seconds and keeps your assumptions grounded in current reality.
A loan calculator will not make a borrowing decision for you, and it should not. What it does is remove the guesswork, replace vague estimates with concrete numbers, and give you the confidence to compare offers like an informed participant rather than a hopeful applicant. Start with the amount you need, the rate you expect, and a term you can live with. Then let the numbers guide the rest. The few minutes you spend running scenarios today can save you thousands of dollars over the life of the loan, and that is a return no other five-minute task can match.
About Sloane Parker
Rent Assistance Loans: Options When You Can’t Pay
Rent assistance loans can fill a shortfall, but grants and payment plans are often cheaper. Compare costs, risks, and repayment options first.
Loan Options Explained: Find Your Best Financing Path
Understand loan options before you apply. Compare rates, avoid costly mistakes, and find financing that fits your budget and goals.
Loan Calculator Guide: Estimate Monthly Payments
A loan calculator shows your exact monthly payment and total interest before you borrow, so you can compare offers and avoid costly surprises.
Find a Loan!